Does Health Insurance Cover Dry Needling in the USA by 2026?
Dry needling has moved from a niche physical therapy technique to a mainstream treatment for muscle pain, trigger points, and movement restrictions. As more clinics advertise it, patients keep asking the same expensive question: will my health plan actually pay for this? The short answer is that coverage in the USA depends heavily on your plan type, your diagnosis, and where you live, and the landscape is shifting as we approach 2026. Understanding these variables before you book a session can save you hundreds of dollars in surprise bills. This guide breaks down how insurers view dry needling, what to check in your policy, and how to build a strategy that protects your wallet while you get the care you need.
What Dry Needling Is and Why Insurers Treat It Carefully
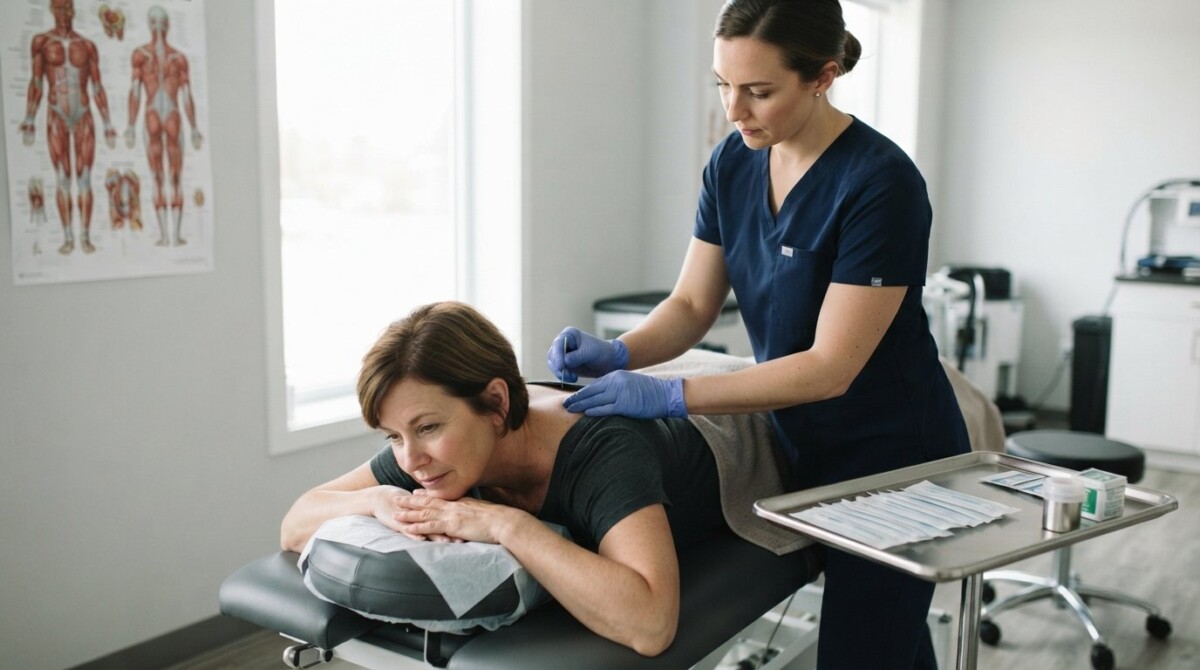
Dry needling involves inserting thin filiform needles into tight muscle bands, often called trigger points, to release tension and reduce pain. It is performed by physical therapists, chiropractors, and some physicians. Unlike acupuncture, which follows traditional Chinese medicine meridians, dry needling is grounded in Western anatomy and targets specific muscular dysfunction. That distinction matters enormously to insurance companies because acupuncture and dry needling are often classified differently, even though the needles look identical.
Insurers treat dry needling carefully for three reasons. First, it is frequently bundled into a physical therapy visit, so the billing codes used determine whether it is covered as therapy or as a separate procedure. Second, some plans explicitly exclude dry needling as “investigational” or “experimental,” language that lets them deny claims even when a licensed provider performs the service. Third, state scope-of-practice laws vary, and insurers often follow state guidance when deciding whether a provider is eligible for reimbursement.
For patients, the practical takeaway is that you cannot assume coverage just because a doctor referred you. You need to verify the specific billing code, the provider type, and your plan’s medical policy. If you are shopping for coverage right now, our guide on where to buy individual health insurance in USA explains the marketplaces and brokers that let you compare these details before you enroll.
How Different Plan Types Handle Dry Needling
Not all health insurance is created equal when it comes to complementary and alternative treatments. The type of plan you hold is the single strongest predictor of whether dry needling will be reimbursed. Below is how the major categories typically behave.
- ACA Marketplace plans: Essential health benefits must cover physical therapy, but dry needling itself is rarely listed as a mandated benefit. Coverage depends on the individual insurer’s medical policy.
- Employer-sponsored PPOs: More likely to cover dry needling when it is medically necessary and performed during a covered physical therapy visit, though prior authorization is common.
- HDHPs paired with an HSA: You usually pay the full negotiated rate until the deductible is met, so the effective cost can feel like no coverage at all.
- Medicare: Original Medicare does not recognize dry needling as a covered service, though some Medicare Advantage plans add it as a supplemental benefit.
- Medicaid: Coverage is state-specific and often limited to certain diagnoses or provider types.
Even within a single insurer, two plans can treat the same procedure differently. A Blue Cross Blue Shield PPO in one state may cover dry needling for chronic neck pain but deny it for plantar fasciitis. That is why reading the medical policy document, not just the summary of benefits, is essential.
Cost also varies widely by plan design. Our breakdown of the average health insurance cost USA monthly 2026 shows how premiums and out-of-pocket limits interact, which helps you estimate whether a plan with a higher premium but broader therapy coverage is worth it.
Key Factors That Determine Your Coverage in 2026
As we move toward 2026, several factors will shape whether your dry needling claim is approved. Insurers are increasingly using clinical guidelines from organizations like the American Physical Therapy Association, and they are tightening prior authorization requirements for pain management procedures. At the same time, more states are passing laws that require coverage for non-opioid pain treatments, which could work in your favor.
Here are the variables that matter most:
- Medical necessity documentation: Your provider must show that conservative treatments failed and that dry needling is expected to improve function.
- Diagnosis codes: Myofascial pain syndrome and specific muscle strains are more likely to be approved than vague chronic pain codes.
- Provider credentials: Some plans only reimburse licensed physical therapists, not chiropractors or acupuncturists.
- Place of service: A hospital outpatient department may bill differently than a private clinic, changing your cost-sharing.
- Prior authorization: Many plans require approval before the first session, and skipping this step guarantees a denial.
If you are self-employed and buying your own coverage, these details become even more important because you cannot rely on an employer’s benefits team to sort them out. Our article on self employed health insurance options USA 2026 walks through how to choose a plan that matches your expected therapy needs.
How to Verify Coverage Before You Get Treated
Never assume that a referral equals a covered service. The most reliable approach is to verify benefits in writing before your first appointment. Start by calling the member services number on your insurance card and asking three specific questions: Is dry needling covered under my plan? What billing code will be used? And does it require prior authorization? Write down the representative’s name and the reference number for the call.
Next, ask your provider’s office for the exact CPT codes they will submit. Common codes for dry needling include 20560 and 20561, which describe the number of muscles treated. With those codes in hand, you can ask your insurer to check the medical policy directly. If the service is covered, confirm your deductible, copay, and coinsurance so you know your expected out-of-pocket cost.
If you receive a denial, do not stop there. You have the right to appeal, and many denials are overturned when a provider submits additional documentation. Ask your therapist to include progress notes, a treatment plan, and evidence that less invasive options were tried first. For patients with high-deductible plans, it sometimes makes sense to ask for a cash-pay rate, which can be lower than the negotiated insurance rate before the deductible is met.
Subsidy eligibility can also change your calculus. If your income qualifies you for savings, our guide to the health insurance subsidy chart USA 2026 explains how to estimate your premium tax credit, which may free up room in your budget for therapies that fall outside standard coverage.
State Laws and 2026 Trends to Watch
State regulation is one of the most underappreciated factors in dry needling coverage. Some states require insurers to cover treatments that reduce reliance on opioids, and dry needling often qualifies under those statutes. Other states have no such mandate, leaving coverage entirely to the insurer’s discretion. If you live in a state with an active pain-management mandate, you may have stronger grounds to appeal a denial.
Looking ahead to 2026, three trends are likely to influence coverage. First, more insurers are adopting telehealth follow-ups and bundled therapy packages, which can change how dry needling is billed. Second, value-based care arrangements are pushing providers to document outcomes more rigorously, which may improve approval rates for well-documented cases. Third, consumer demand for non-pharmacological pain relief continues to rise, and insurers are slowly responding by expanding therapy benefits in competitive markets.
That said, nothing is guaranteed. The safest strategy is to treat dry needling coverage as a plan-specific question rather than a universal yes or no. Review your plan documents each year during open enrollment, and if dry needling is important to you, prioritize plans that explicitly list it as a covered benefit.
Frequently Asked Questions
Does Medicare cover dry needling in 2026?
Original Medicare generally does not cover dry needling because it is not recognized as a covered service under Part B. Some Medicare Advantage plans include it as a supplemental benefit, so check your plan’s evidence of coverage. If you have a Medicare Advantage plan, call member services and ask for the specific medical policy on dry needling.
Can I get dry needling covered under an ACA plan?
ACA Marketplace plans must cover essential health benefits, which include physical therapy, but dry needling is not a mandated benefit. Coverage depends on the insurer’s medical policy and whether the service is billed as part of a covered physical therapy visit. Always verify with your specific insurer before treatment.
What should I do if my claim is denied?
File an internal appeal with your insurer and include documentation from your provider showing medical necessity. If the internal appeal fails, you may request an external review. Many denials are reversed when providers submit detailed progress notes and evidence that other treatments were unsuccessful.
Is dry needling covered by HSA funds?
If dry needling is a qualified medical expense, you can typically use HSA funds to pay for it even if your insurance does not cover the service. Keep receipts and confirm with your HSA administrator, since rules can vary based on your plan and the diagnosis.
Dry needling can be a valuable tool for recovery, but whether your health insurance pays for it in the USA by 2026 is a question only your specific policy can answer. By verifying benefits early, understanding your plan type, and using the appeal process when necessary, you can avoid surprise bills and get the treatment you need. For more guidance on comparing plans and understanding your options, explore the resources at InsuranceShopping.com and make your next coverage decision with confidence.
Share This Story, Choose Your Platform!
About the Author: Theo Merrick