Condo Insurance vs Homeowners: Key Coverage Gaps
Condo insurance covers interior building elements and loss assessments that homeowners policies do not. Call 8332146397 to compare quotes and close coverage gaps.
By Everett Hale
Buying a condo feels a lot like buying a house, until you sit down to insure it. The confusion is understandable: both are homes, both hold your belongings, and both expose you to liability. But the insurance products built for each are not interchangeable. If you assume your condo association's master policy works like a homeowners policy, you could end up paying thousands out of pocket for a loss you thought was covered. The question of what does condo insurance cover that homeowners insurance does not is really a question about walls, shared structures, and who is responsible when something breaks. Getting this wrong is one of the most common and costly mistakes condo owners make.
The short answer is that condo insurance (often called an HO-6 policy) fills the gap between your association's master policy and your personal property. A homeowners policy (typically HO-3) insures the entire dwelling structure, inside and out, because you own it outright. Condo owners do not own the building shell, so their policy is built differently. It covers interior building elements, personal property, liability, and loss assessment, among other things. Those categories, especially interior building elements and loss assessment, are where condo coverage does things a homeowners policy simply was not designed to do. This guide breaks down each difference, explains the master policy puzzle, and shows you how to size your coverage so you are never caught underinsured.
The Master Policy Puzzle: Why Condo Coverage Starts Where Homeowners Coverage Ends
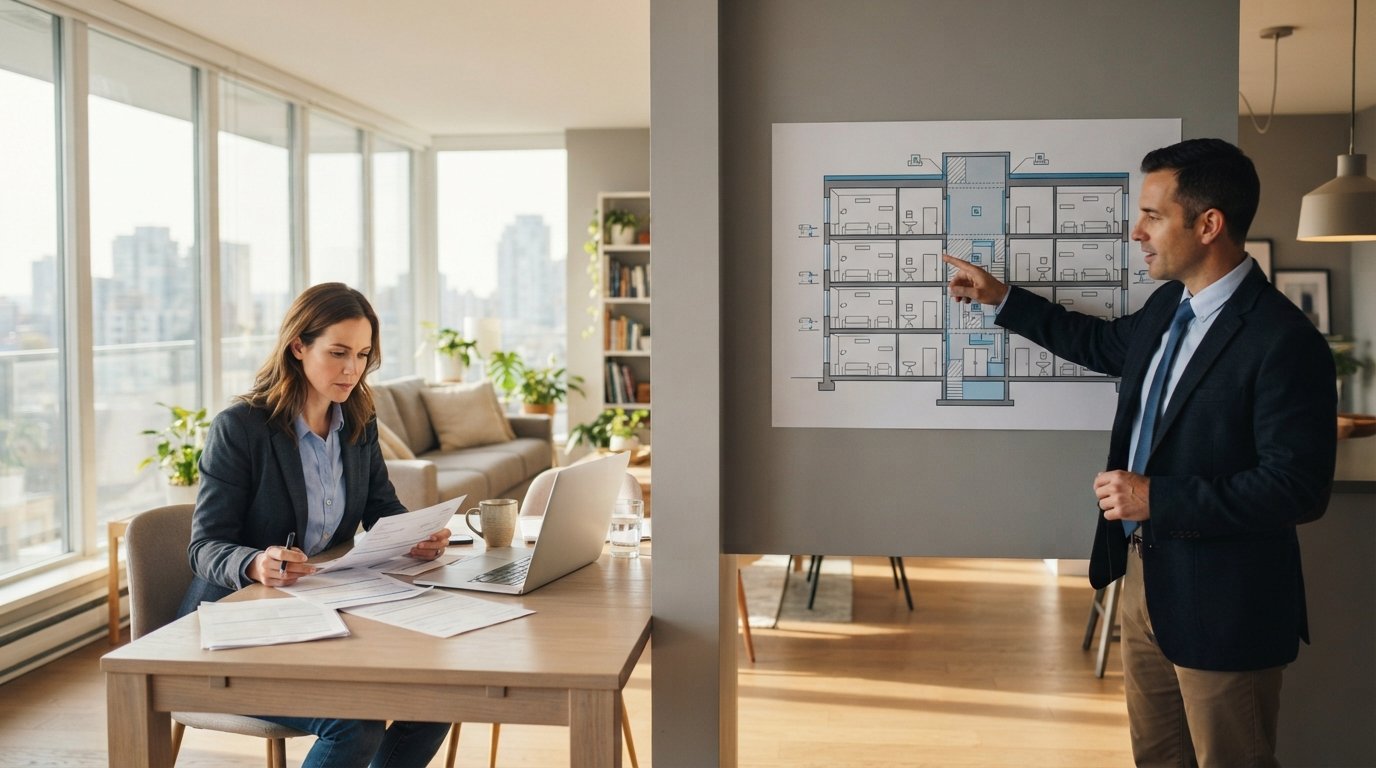
Every condo building has a master policy, purchased by the condo association or HOA, that covers the shared structure: the roof, the exterior walls, the foundation, elevators, and common areas like hallways and pools. What that master policy does not automatically cover is the inside of your unit. That is where the coverage gap opens up. A homeowners policy covers the dwelling, meaning the entire physical structure of a single-family home. A condo policy does not cover the building shell, because you do not own it. Instead, it covers your share of the interior and your personal interests.
The complication is that master policies come in different flavors. A bare walls-in policy covers only the original structure and common elements, leaving you responsible for essentially everything inside your unit, including cabinets, flooring, fixtures, and sometimes even drywall. A single entity or all-in policy covers the unit as originally built, including standard fixtures and finishes, so you only need to insure upgrades and personal property. Most associations fall somewhere in between, which means you have to read the master policy or ask your HOA for a copy before you buy coverage. The difference between these two structures can swing your premium and your out-of-pocket exposure dramatically.
This is the first and most important way condo insurance diverges from homeowners insurance. A homeowners policy has no master policy sitting above it, so the dwelling coverage limit is set to rebuild the whole house. A condo policy is designed to sit in a specific layer of a stacked system: the master policy below, your HO-6 in the middle, and your personal assets above. If you buy homeowners-style dwelling coverage for a condo, you are overpaying for protection you do not need. If you buy none, you are exposed to the bare walls-in scenario. Understanding this stack is the foundation for everything else in this article.
Interior Building Coverage: The Condo-Specific Protection Homeowners Policies Lack
Here is a concrete example. A pipe bursts in the unit above yours and water pours through your ceiling. The drywall, paint, and ceiling fan are damaged. Under a bare walls-in master policy, the association fixes the pipe and maybe the structural framing, but the drywall, paint, and fan are your problem. A condo policy with interior building coverage (sometimes called building property or unit improvements and betterments) pays to repair those items. A homeowners policy would also pay, but only because it insures the entire dwelling. The difference is structural: homeowners coverage is built for the whole house, while condo interior building coverage is built for the parts of the unit you actually own.
Interior building coverage typically includes:
- Drywall, paint, and wallpaper inside your unit
- Flooring, including hardwood, tile, or carpet
- Cabinets, countertops, and built-in appliances
- Light fixtures, ceiling fans, and plumbing fixtures
- Upgrades you made after purchase, such as a renovated kitchen or bathroom
That last item matters more than most owners realize. Even under an all-in master policy, your custom upgrades are usually not covered. If you spent $30,000 remodeling your kitchen, you need interior building coverage sized to rebuild that kitchen at today's prices. Standard homeowners policies handle this automatically through dwelling coverage, but condo owners have to consciously select a limit for interior building property. Many lenders require at least some interior building coverage as a condition of the mortgage, but the minimum is rarely enough. Review your upgrades, get contractor estimates, and set your limit accordingly. If you are also shopping for vehicle protection, the same principle of matching coverage to actual ownership applies, and our guide on whether car insurance covers repairs walks through how to avoid the same kind of gap on the road.
Loss Assessment Coverage: A Protection Homeowners Rarely Need
Loss assessment coverage is one of the clearest answers to what does condo insurance cover that homeowners insurance does not. When a covered loss hits the common elements, such as a fire in the clubhouse or a liability lawsuit against the HOA, the association may pay the claim and then assess each unit owner for the shortfall. Those assessments can run into the thousands of dollars per unit. Loss assessment coverage on a condo policy pays your share of that assessment, up to your limit. Homeowners policies sometimes include a small amount of loss assessment coverage, but it is rarely meaningful for condo-style shared ownership because the exposure is different.
Consider a real-world scenario: a guest slips and falls in the community pool area and sues the HOA for $500,000. The master policy covers part of it, but the association's deductible and any uncovered portion get passed to owners as a special assessment of $5,000 each. Without loss assessment coverage, that $5,000 comes straight out of your pocket. With it, your insurer reimburses you up to your limit, which is commonly $1,000 to $50,000 depending on the policy. For a relatively small premium, you transfer a risk that could otherwise wipe out your emergency fund.
Homeowners in a single-family house do not face this exposure because there is no association to levy assessments. That is why loss assessment is a condo-specific coverage line. If your HOA has ever raised dues for a major repair or if the building is older, this coverage deserves serious attention. Ask your agent what limit is appropriate given your association's deductible and reserve fund status. A well-funded HOA with a large reserve needs less loss assessment coverage; an underfunded one needs more.
Personal Property and Liability: Similar Names, Different Limits and Needs
Both condo and homeowners policies cover personal property (your furniture, electronics, clothing, and similar items) and personal liability (if someone is injured in your home or you damage someone else's property). The names are the same, but the sizing logic differs. In a homeowners policy, personal property coverage is often set at 50 to 70 percent of the dwelling limit, which scales automatically with the size and value of the house. In a condo policy, there is no dwelling limit to anchor to, so you choose a personal property limit directly. That means you have to do the math yourself, and many owners underestimate.
A simple inventory framework helps:
- Walk through each room and list major items with replacement costs.
- Add up electronics, furniture, clothing, kitchenware, and tools.
- Note high-value items like jewelry, art, or musical instruments, which often need scheduled coverage.
- Compare the total to your current limit and adjust upward if needed.
Liability limits also deserve a fresh look. Condo living means shared walls, shared floors, and shared systems. If your bathtub overflows and damages three units below, you could be liable for their repairs and temporary housing. A $100,000 liability limit may not be enough in a dense building. Many condo owners choose $300,000 to $500,000, and some add an umbrella policy for extra protection. Homeowners face similar liability risks, but the shared-structure environment of a condo can multiply the number of people affected by a single incident.
Additional Living Expenses and Unit Rental: Where Condo Policies Adapt
If your condo becomes uninhabitable after a covered loss, additional living expenses (ALE) coverage pays for a hotel, rental apartment, and extra food costs while repairs are underway. Homeowners policies have the same coverage, so this is not a unique difference. What is different is the timeline. Condo repairs often take longer because they may involve the association, multiple units, and coordination with the master policy insurer. ALE limits that seem generous for a house may run out faster in a condo claim, so review your limit with that in mind.
Another condo-specific wrinkle is rental to others. Many condo owners rent their units seasonally or long-term. Standard condo policies may limit or exclude coverage for a unit you rent out, and homeowners policies have similar restrictions. If you rent your condo, you likely need a landlord endorsement or a dedicated rental dwelling policy. The key point is that condo insurance can be adapted to rental use through endorsements, and those endorsements are built with condo ownership in mind. Always disclose rental activity to your insurer to avoid a denied claim.
How to Choose the Right Condo Coverage Without Overpaying
The best way to avoid both gaps and overpayment is a three-step review. First, get the master policy documents from your HOA and identify whether it is bare walls-in, single entity, or something in between. Second, inventory your personal property and document your interior upgrades with photos and receipts. Third, set your HO-6 limits to match: interior building coverage for your upgrades and finishes, personal property for your belongings, loss assessment for HOA shortfalls, and liability high enough to protect your assets. Revisit this every year or after any renovation.
Comparison shopping matters because condo premiums vary widely by state, building age, claims history, and coverage limits. An independent resource like NewAutoInsurance.com shows how consumer-focused comparison sites organize coverage education and quote tools, and the same shopping discipline applies to condo insurance. Gather at least three quotes, ask each agent to explain how their HO-6 interacts with your specific master policy, and confirm that interior building and loss assessment limits are adequate. Do not simply accept the lender's minimum, because the lender is protecting its collateral, not your belongings.
Finally, remember that condo insurance and homeowners insurance are tools for different ownership structures. Neither is better in the abstract; they are matched to what you own. If you own the whole structure, homeowners insurance is the right fit. If you own the interior of a unit within a shared building, condo insurance covers the exposures that a homeowners policy was never designed to address: interior building elements, loss assessment, and a layered relationship with a master policy. Understanding those differences is the difference between a claim that gets paid and a bill you never saw coming.
Take fifteen minutes this week to pull your master policy, list your upgrades, and call your insurer with one question: does my HO-6 limit actually match what I own inside these walls? That single conversation can save you thousands and give you confidence that your coverage fits your condo, not a house you do not own.