How to Prove a Dependent for Health Insurance Enrollment
Need to add a family member to your plan? Call 8332146397 for expert assistance. We explain how to prove a dependent for health insurance enrollment step by step.
By Daniel Greene
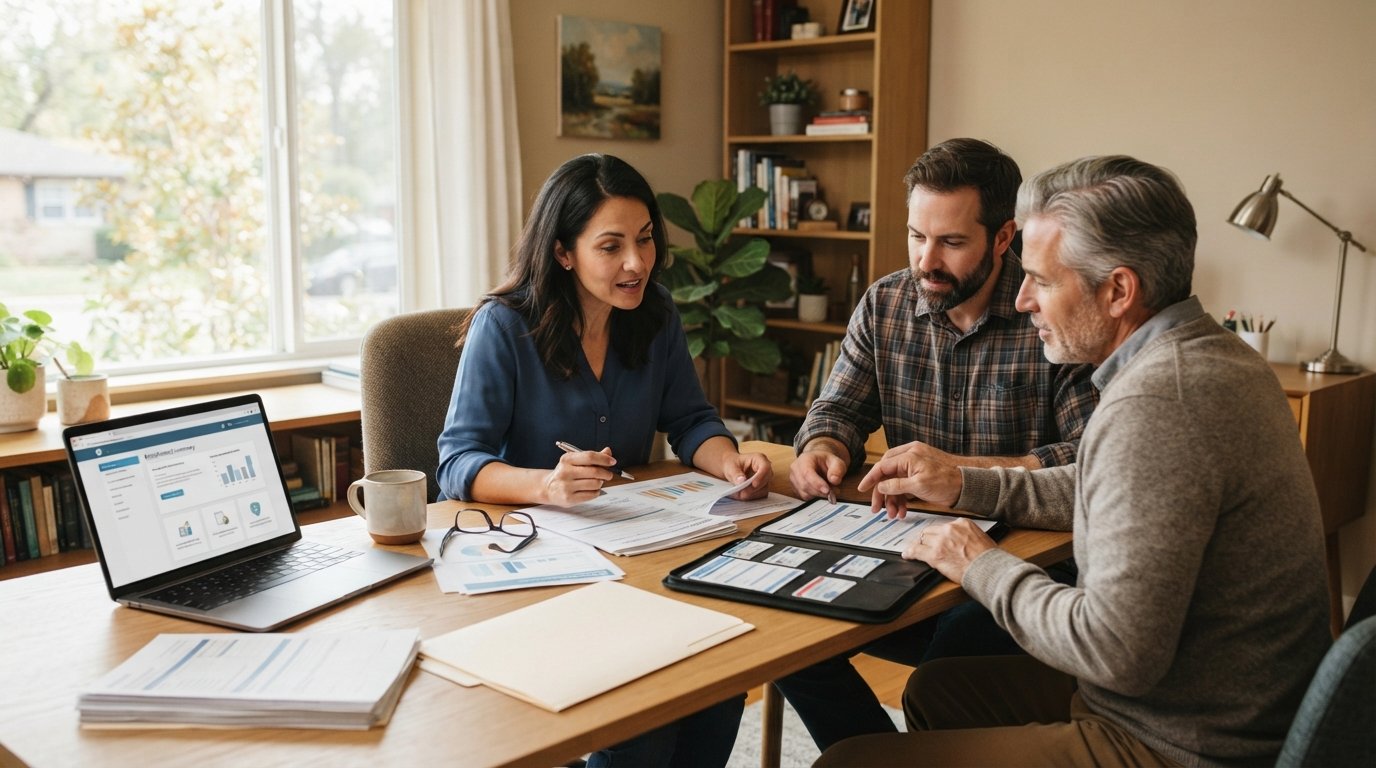
Adding a family member to your health plan can feel like a race against the clock. You have a narrow window after a qualifying life event, and if you cannot produce the right paperwork, the insurer may deny coverage or delay your effective date. That delay can leave you paying cash for doctor visits, prescriptions, or even a hospital stay. Understanding exactly how to prove a dependent for health insurance enrollment removes the guesswork and helps you lock in coverage without expensive gaps.
The process is not complicated once you know which documents count and how to submit them. Insurers want evidence that the person you are adding truly meets their definition of a dependent. They are not trying to trap you. They are verifying eligibility so that premium tax credits and plan rules are applied correctly. In this guide, you will learn which documents work, which ones get rejected, and how to handle special situations like stepchildren, domestic partners, and adult dependents with disabilities.
What Counts as a Dependent for Health Insurance
Before you gather paperwork, confirm that the person you want to add actually qualifies. Health insurers generally use the same core definition as the IRS, though some plans add their own rules. A dependent is typically a spouse, a biological or adopted child, a stepchild, or a foster child who relies on you for financial support. The Affordable Care Act also requires most plans to cover adult children up to age 26, even if they are married, live elsewhere, or are not claimed on your tax return.
For tax purposes, a qualifying child or relative must meet residency, support, and relationship tests. The health insurance definition is broader in some ways and narrower in others. For example, a domestic partner is not a tax dependent under federal rules, but some employers and insurers allow domestic partner coverage if you can show a shared residence and financial interdependence. Always check your specific plan document or summary of benefits to see which categories it recognizes.
Here are the most common dependent categories you will encounter:
- Spouse or legal spouse under state law
- Biological, adopted, or foster child under age 26
- Stepchild or legal ward under age 26
- Domestic partner (if your plan offers this option)
- Adult child with a disability who cannot self-support
If your relationship falls outside these categories, you may still be able to add the person through a private plan or a non-ACA policy, but the documentation requirements will be different. The key is to match your situation to the plan's written eligibility rules before you submit anything.
Documents That Prove a Dependent Relationship
Insurers want documents that are current, legible, and issued by a government or institutional authority. A handwritten note from you will not work. A screenshot of a text message will not work. The strongest evidence comes from official records that show names, dates, and the relationship between you and the dependent.
For a spouse, the gold standard is a marriage certificate. A marriage license alone is usually not enough because it only shows that you applied, not that the marriage was completed. If you recently married, request a certified copy from the county clerk or state vital records office. Some insurers accept a marriage certificate plus a joint tax return or a shared bank statement, but the certificate alone is typically sufficient.
For a child, a birth certificate is the most common document. It shows the parent-child relationship and the child's date of birth. If you are adding a stepchild, you will need the birth certificate plus a marriage certificate showing your marriage to the child's parent. For an adopted child, provide the adoption decree or a birth certificate that lists you as the parent. For a foster child, you will need a placement agreement or a court order.
For a domestic partner, documentation varies by plan. Common accepted proofs include a domestic partnership registration, a joint lease or mortgage, a joint bank account statement, and a signed affidavit of financial interdependence. Some insurers require at least two or three of these items. Because rules differ, call the insurer's member services line before you gather everything so you do not waste time on documents they will not accept.
For an adult child with a disability, you will need the birth certificate plus medical records or a letter from a physician confirming the disability. Some plans also require proof that the child is financially dependent on you, such as a tax return showing you provide more than half of their support. This category often requires a manual review, so submit your documents early.
How to Submit Proof During Open Enrollment vs. Special Enrollment
Timing matters as much as the documents themselves. During open enrollment, you can add dependents without a qualifying life event. The insurer will still ask for proof, but you usually have more flexibility. During special enrollment, you must have a qualifying life event such as marriage, birth, adoption, or loss of other coverage. You also have a limited window, typically 30 to 60 days from the event, to complete the enrollment and submit your documents.
If you miss the special enrollment window, you may have to wait until the next open enrollment period. That is why it is critical to start the process immediately after the event. Do not wait for the insurer to ask for documents. Gather them as soon as possible and upload them through your online account or submit them by mail, fax, or secure email, depending on what the insurer allows.
Here is a simple sequence that works for most enrollment situations:
- Confirm your qualifying life event and the deadline for your special enrollment period.
- Review your plan's dependent eligibility rules and document requirements.
- Order certified copies of marriage certificates, birth certificates, or court orders.
- Submit your enrollment application and upload or mail your proof documents together.
- Follow up within one week to confirm the insurer received and accepted your documents.
Following up is not optional. Insurers process thousands of enrollments, and documents can get lost or mislabeled. A quick phone call or secure message can confirm that your dependent is approved and that your coverage effective date is correct. If you are also shopping for other types of coverage during this busy period, you can compare options for auto insurance guidance and comparisons to keep your household protected without adding stress.
Common Mistakes That Delay or Derail Enrollment
Even people with the right documents run into problems. The most common mistake is submitting a document that does not show the relationship clearly. For example, a birth certificate that lists only the mother's name will not prove that you are the father. In that case, you may need a voluntary acknowledgment of paternity, a court order, or a DNA test result. Similarly, a marriage certificate that is handwritten or not certified may be rejected.
Another frequent issue is name mismatches. If your last name changed after marriage but your Social Security record still shows your maiden name, the insurer may flag the application. Update your records with the Social Security Administration first, then submit your enrollment documents. If your dependent's name is spelled differently on two documents, provide a correction or an explanatory letter.
People also forget that some plans require proof of financial dependence for certain dependents. A domestic partner or an adult child with a disability may need tax returns, bank statements, or affidavits. If you skip these, the insurer will send a request for more information, which restarts the clock and can push your effective date back by weeks.
Finally, do not assume that uploading a document once is enough. Some insurers require you to resubmit proof every year during open enrollment. Set a calendar reminder so you do not lose coverage for a dependent because you forgot to re-verify their eligibility.
Special Situations: Stepchildren, Foster Children, and Legal Guardianship
Stepchildren are generally eligible for coverage if they are under age 26 and you are married to their parent. The insurer will typically ask for the child's birth certificate and your marriage certificate. If you are not married but have legal guardianship, you will need a court order establishing guardianship. Some plans also accept a power of attorney or a notarized caregiver affidavit, but this is less common.
Foster children are eligible for coverage under most ACA-compliant plans, but the documentation is different. You will need a placement agreement from the state child welfare agency or a court order. If the child is in your care temporarily, the insurer may require a letter from the agency confirming the placement and your role as the caregiver. This category often requires manual review, so submit your documents as early as possible.
Legal guardianship is another path. If you have a court order appointing you as the guardian of a child, you can usually add that child to your health plan. The court order must be current and show that you have legal responsibility for the child's care. Some insurers also require proof that the child lives with you, such as a school record or a utility bill in your name.
If you are unsure whether your situation qualifies, call the insurer before you enroll. A five-minute conversation can save you hours of paperwork and prevent a denial. You can also review how dental insurance with health insurance USA coverage guide explains dependent documentation for ancillary products, which often follows similar rules.
What to Do If Your Dependent Is Denied
A denial is not the end of the road. Insurers must tell you why they denied the dependent and what you can do to fix it. Common reasons include missing documents, a name mismatch, or a failure to meet the plan's definition of a dependent. If you receive a denial letter, read it carefully and respond within the deadline. You can usually appeal by submitting additional documents or a written explanation.
If the denial is based on a factual error, such as a misspelled name or a wrong date of birth, correct it and resubmit. If the denial is based on eligibility rules, you may need to provide more evidence or consider a different plan. Some families find that a private plan or a short-term policy is a better fit when a dependent does not qualify for the group plan. Just remember that short-term plans may not cover pre-existing conditions and do not satisfy the individual mandate in states that still have one.
If you believe the denial was unfair or violated your rights, you can file a complaint with your state department of insurance or the U.S. Department of Labor if your plan is employer-sponsored. Keep copies of everything you submit, including dates, names of representatives, and confirmation numbers. This paper trail will help you resolve the issue faster.
Frequently Asked Questions About Proving Dependents
Can I add a dependent without a Social Security number? Yes, in some cases. Insurers may accept a tax identification number, a green card, or a passport. If your dependent is undocumented, some plans allow coverage, but they may not qualify for premium tax credits. Check the plan's rules before you apply.
Do I need to prove dependency every year? Many insurers require annual verification during open enrollment. If you fail to provide documents, your dependent may be dropped from the plan. Set a reminder and keep digital copies of all documents.
What if I have a domestic partner but we are not married? Some plans offer domestic partner coverage, but you will need to prove shared residence and financial interdependence. Common proofs include a joint lease, joint bank account, and a signed affidavit. Not all plans offer this option, so confirm before you enroll.
How long does it take to approve a dependent? Most approvals take 3 to 10 business days after the insurer receives complete documents. During busy enrollment periods, it can take longer. Submit early and follow up to avoid delays.
Can I add a parent as a dependent? Generally, no. Health plans do not allow you to add a parent as a dependent unless you have legal guardianship or a court order. Parents may qualify for Medicare or Medicaid instead. If you need coverage for a parent, explore separate plans or Medicare options.
Proving a dependent for health insurance enrollment comes down to preparation and follow-through. Know your plan's rules, gather official documents, submit them on time, and confirm receipt. If you hit a snag, appeal with additional evidence and keep a record of every conversation. With the right approach, you can secure coverage for your family and avoid the financial shock of an unexpected gap.