Long Term Care Insurance: What It Covers and Who Needs It
Understand long term care insurance what it covers and who needs it, plus how to compare policies. Call (833)-214-6397 for guidance.
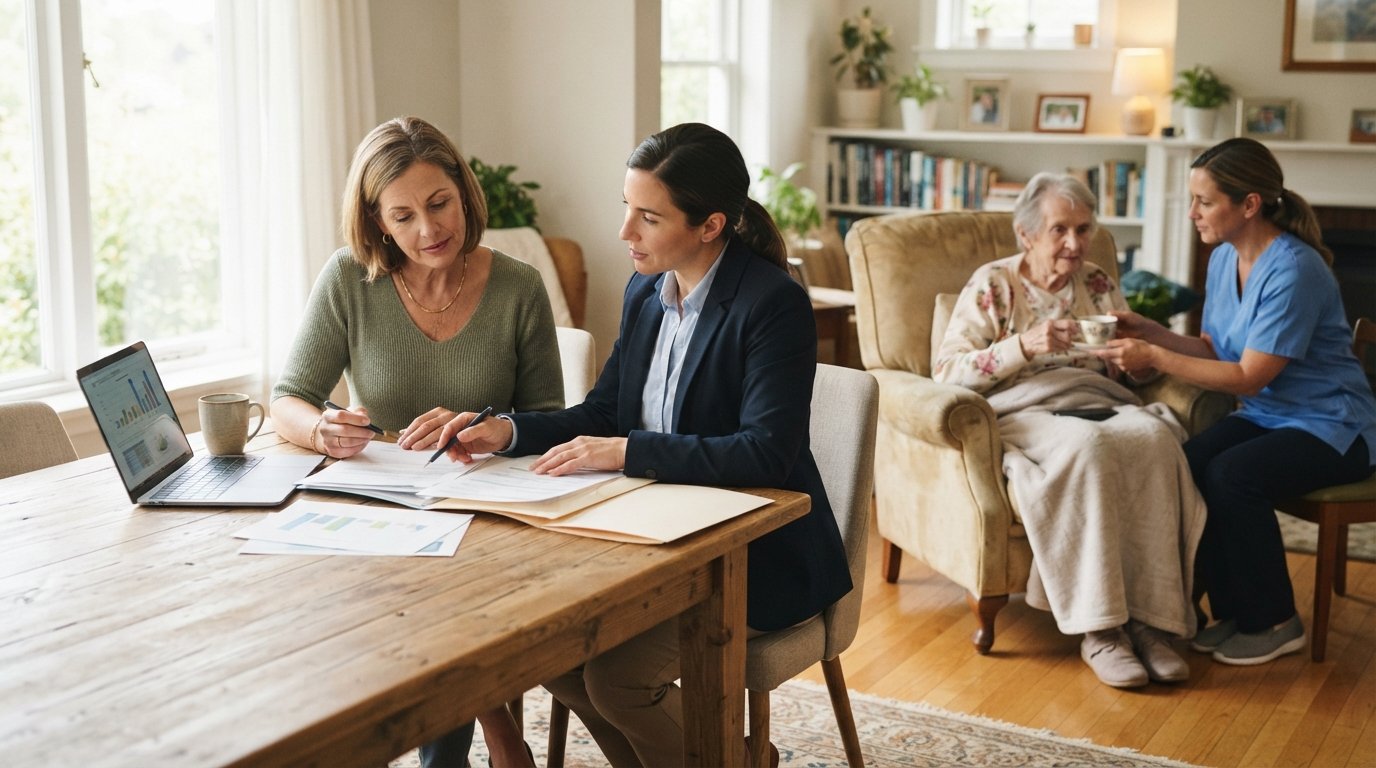
Most people picture retirement as a stretch of years filled with travel, family, and freedom. What they rarely picture is the possibility that they might need help with basic tasks like bathing, dressing, or eating for months or even years. Yet the odds are higher than many expect: someone turning 65 today has roughly a 70 percent chance of needing some form of long-term care in their lifetime, according to federal estimates. That reality is why long term care insurance what it covers and who needs it has become one of the most searched questions among adults planning for their financial future. This guide breaks down the services these policies pay for, how claims are triggered, the fine print that shapes payouts, and how to decide whether coverage belongs in your plan.
What Long Term Care Insurance Typically Covers
Long term care insurance is designed to pay for help with everyday activities when a chronic illness, disability, or cognitive decline makes it impossible to manage on your own. Unlike health insurance, which focuses on medical treatment, long term care coverage addresses the custodial and personal care that medical plans usually exclude. That distinction matters because Medicare and most major medical plans do not pay for extended help with bathing, dressing, or supervision.
Policies generally reimburse a set dollar amount per day for covered services, up to a maximum benefit pool. The specific services covered vary by policy, but most comprehensive plans include the following:
- Home care: assistance from home health aides, personal care attendants, and sometimes informal caregivers such as family members, depending on the policy.
- Adult day care: supervised programs that provide social activities and personal care during daytime hours.
- Assisted living facilities: room and board plus help with activities of daily living in a residential setting.
- Nursing home care: skilled nursing care and personal assistance in a licensed facility.
- Respite care and caregiver training: short-term relief for family caregivers and education on providing care safely.
Less common benefits may include home modifications, emergency alert systems, and care coordination services. Some policies also cover hospice care or provide a bed reservation benefit if you need to leave a facility temporarily. When comparing plans, read the schedule of benefits carefully: a policy that covers only nursing home care offers far less flexibility than one that reimburses home care and assisted living at the same rate.
It is also worth noting what long term care insurance does not cover. Policies typically exclude care related to self-inflicted injuries, war, or acts of war, and many exclude care provided outside the United States. Some plans will not pay family members directly unless they are licensed professionals. Understanding these exclusions up front prevents unpleasant surprises at claim time.
How Benefit Triggers Work: When Does Coverage Start?
You cannot simply decide you need long term care and start collecting benefits. Every policy has specific benefit triggers that must be met before the insurer pays. The most common trigger is a loss of functional capacity: you cannot perform at least two of six activities of daily living (ADLs) without substantial help. Those six activities are bathing, dressing, eating, toileting, transferring (moving from bed to chair), and continence.
The second major trigger is cognitive impairment. If a physician diagnoses you with a severe cognitive condition such as Alzheimer's disease or another form of dementia, benefits can begin even if you can still physically perform all six ADLs. Insurers usually require a licensed health care professional to certify your condition, and some policies require periodic re-certification.
Understanding these triggers is essential because they define the boundary between independent living and a claim. A policy might advertise generous benefits, but if the trigger requires two ADL losses and your situation involves only one, the insurer will not pay. When shopping, ask how the insurer assesses ADL loss and whether a doctor's certification is sufficient or whether the company sends its own assessor. The clearer the trigger language, the easier it is to plan.
Elimination Periods, Benefit Amounts, and Inflation Protection
Three levers determine how much a long term care policy actually pays and when. The first is the elimination period, which is essentially a deductible measured in days. A 90-day elimination period means you pay for the first 90 days of care yourself before benefits begin. Elimination periods can be based on calendar days or service days, and the difference matters: a 90-service-day period can stretch far longer than 90 calendar days if you receive care only a few times a week. Shorter elimination periods lower your out-of-pocket exposure but raise premiums.
The second lever is the benefit amount. Policies state a daily or monthly maximum, such as $150 per day or $4,500 per month. That amount is not a blank check: it caps what the insurer will reimburse for covered services. If your actual care costs $200 per day and your benefit is $150, you pay the difference. The benefit pool is the total dollar amount available over the life of the policy, often expressed as a multiple of the daily benefit (for example, a $150 daily benefit with a three-year benefit period equals roughly $164,250).
The third lever is inflation protection, and it is arguably the most important for anyone buying coverage before retirement. The cost of care rises over time, often faster than general inflation. A policy with a $150 daily benefit purchased at age 55 may look adequate today but could be woefully insufficient at age 80 if care costs have doubled. Inflation riders, such as 3 percent or 5 percent compound annual increases, raise both the daily benefit and the pool over time. They add to the premium, but they preserve the purchasing power of the policy. A simple framework for evaluating these levers:
- Choose an elimination period you could comfortably self-fund (90 days is common).
- Set the daily benefit based on local care costs in your area, not national averages.
- Select a benefit period that matches your risk tolerance (two to three years covers many situations; longer periods cost more).
- Add compound inflation protection, especially if you are buying before age 65.
- Compare the total premium against the potential pool of benefits to see the leverage.
Running these numbers side by side across several insurers is where many shoppers get stuck. Tools that let you compare quotes from multiple carriers can simplify the process, and resources like QuoteComparison offer a starting point for understanding how premiums and benefits stack up. Remember that any quote is an estimate, and actual rates depend on underwriting.
Who Actually Needs Long Term Care Insurance?
There is no single profile that fits every buyer, but certain factors make coverage more compelling. The first is assets: long term care insurance is primarily an asset-protection tool. If you have substantial savings, a home, and investments you want to pass to heirs, a policy can shield that wealth from being drained by care costs. The second is family history: a parent or sibling with dementia or a prolonged disability raises your own statistical risk. The third is geography: care costs vary dramatically by state, and in high-cost areas the financial exposure is larger. The fourth is marital status: single individuals have no spouse to provide unpaid care, while married couples face the risk that one spouse's care needs consume the couple's shared resources.
On the other hand, some people may reasonably skip traditional long term care insurance. Those with very limited assets may qualify for Medicaid, which covers long-term care for people who meet income and asset limits, though the process involves spend-down rules and limited choices. Very wealthy individuals may choose to self-insure, paying for care out of pocket while preserving other assets. And some people simply cannot qualify for coverage due to existing health conditions, or they find the premiums unaffordable on a fixed income.
Age is another factor. Buying coverage in your 50s or early 60s is generally cheaper and easier than waiting until your 70s, when health issues may lead to denial or higher rates. Many people consider long term care insurance before retirement age precisely because underwriting is more favorable and premiums are locked in. That said, the decision should be part of a broader retirement plan, not an impulse purchase.
When evaluating whether you need coverage, ask yourself a few practical questions: Could I pay $100,000 or more per year for care without jeopardizing my spouse's security? Do I have family who could provide care, and would I want them to? What would happen to my savings if I needed three years of assisted living? The answers will clarify whether insurance is a useful tool or an unnecessary expense. If you are unsure how long term care fits with your other health coverage, our guide on finding the best long term health insurance plan walks through the comparison process step by step.
Alternatives to Traditional Long Term Care Coverage
Traditional standalone long term care policies are not the only option. Several alternatives have emerged, each with different trade-offs. Hybrid policies, for example, combine life insurance or an annuity with a long term care benefit. If you never need care, your beneficiaries receive a death benefit; if you do need care, you can accelerate the policy's value to pay for it. Hybrids typically require a single premium or a limited number of payments, and they avoid the use-of-it-or-lose-it concern that bothers some buyers. The trade-off is a higher upfront cost and less flexibility in benefit design.
Another alternative is self-insuring through a dedicated savings account or investment portfolio earmarked for care. This approach gives you full control and no premium risk, but it requires discipline and sufficient assets. A third option is relying on family caregivers, though this can strain relationships and finances. Finally, some states offer Partnership programs that allow certain long term care policies to protect assets from Medicaid spend-down, which can make coverage more attractive for middle-income buyers.
Each alternative has strengths and weaknesses. Hybrid policies suit people who want a guaranteed payout either way. Self-insuring suits those with high net worth and a high tolerance for risk. Medicaid planning suits those with limited assets, though it involves complex rules. The key is to match the solution to your financial situation and your family's ability to provide care.
Practical Steps Before You Buy
If you decide to explore coverage, approach the process methodically. First, gather information about local care costs from home care agencies, assisted living facilities, and nursing homes in your area. Second, review your finances to determine how much of a daily benefit you could self-fund and how long you could pay out of pocket. Third, speak with a licensed insurance agent who can explain policy details and run quotes from multiple carriers. InsuranceShopping.com connects consumers with licensed professionals who can help compare options, but the site does not issue policies or guarantee rates.
Fourth, read the outline of coverage carefully. This document summarizes benefits, exclusions, limitations, and premium. Pay attention to the elimination period definition, the inflation protection feature, and the claims process. Fifth, consider whether a hybrid policy might better fit your goals. Finally, review your choice every few years as your health, assets, and care costs change. A policy that made sense at 55 may need adjustment at 70.
Long term care insurance is not for everyone, but for many people it fills a gap that health insurance and Medicare leave wide open. Understanding what it covers, how triggers work, and who benefits most helps you make a decision grounded in your own circumstances rather than fear or sales pressure. Start with education, compare carefully, and choose coverage that protects the life you have built.