Umbrella Insurance Extra Liability Protection Explained
Umbrella insurance extra liability protection explained: get a second layer of coverage beyond auto and home limits. Call 8332146397 to compare options.
By Scott Thompson
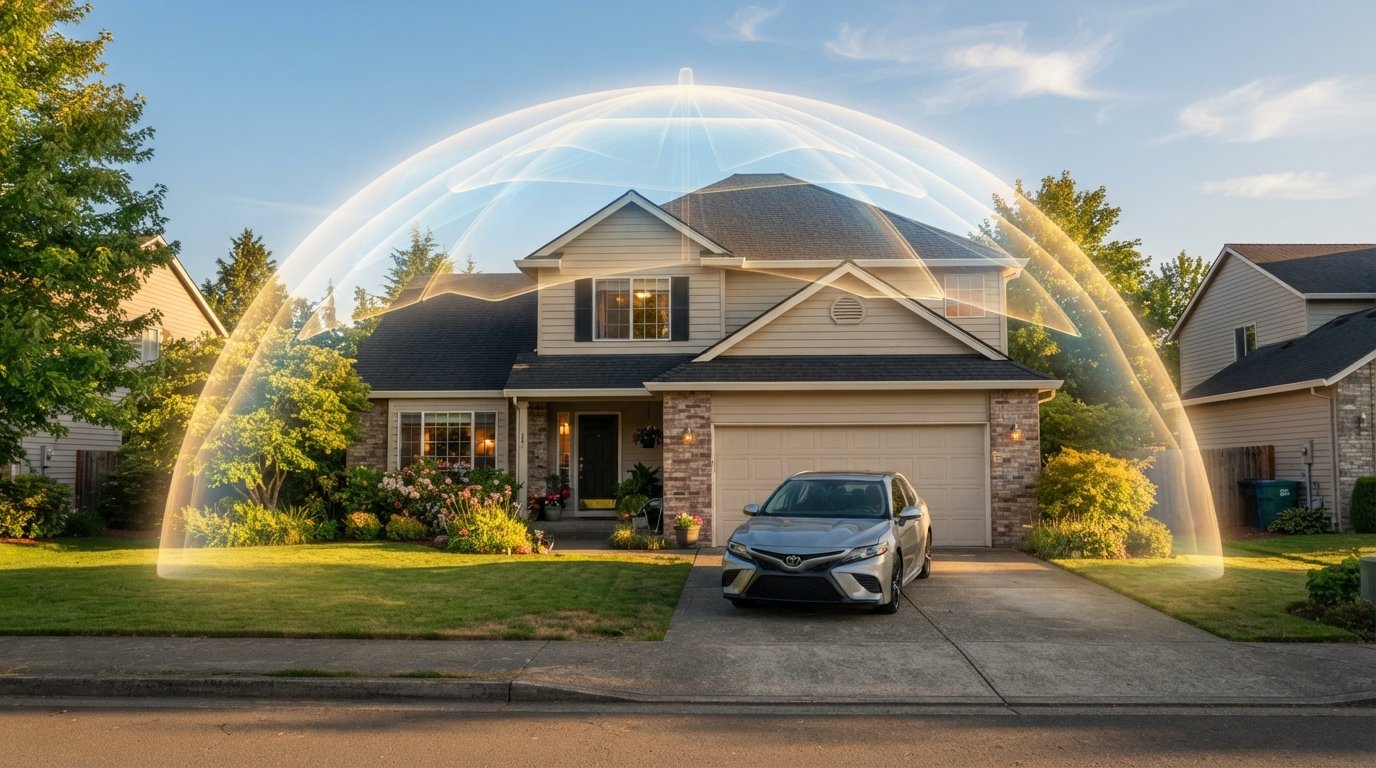
Your standard auto, home, or renters policy includes liability coverage, but that protection has a ceiling. If a serious accident or lawsuit pushes costs past that ceiling, you become personally responsible for the difference. Umbrella insurance extra liability protection explained simply is a second layer of coverage that sits above your existing policies and shields your income, savings, and future earnings from catastrophic claims. This guide breaks down how umbrella policies work, who needs them, what they cost, and how to choose the right limits for your situation.
What Umbrella Insurance Is and How It Works
An umbrella policy is a form of personal liability insurance that provides coverage beyond the limits of your underlying auto, homeowners, or renters insurance. When a covered claim exceeds the liability limit on your primary policy, the umbrella policy kicks in to pay the remaining costs, up to its own limit. Most umbrella policies are sold in increments of one million dollars, and they typically cover both you and members of your household.
The mechanics are straightforward. Suppose you carry 250,000 dollars in bodily injury liability per person on your auto policy, and you cause an accident that results in a 600,000 dollar judgment against you. Your auto insurer pays its 250,000 dollar limit, and your umbrella policy covers the remaining 350,000 dollars, assuming the claim is covered. Without the umbrella, you would be personally responsible for that 350,000 dollar gap, which could mean liquidating savings, tapping retirement accounts, or facing wage garnishment.
Umbrella coverage also handles claims that your primary policies may not cover at all, such as libel, slander, false arrest, and invasion of privacy. It can apply to incidents that occur away from home, including accidents involving rental cars or watercraft, and it may extend to certain lawsuits related to your personal activities. The key requirement is that you maintain the underlying policies at the minimum liability limits specified by the umbrella insurer, which are often higher than state minimums.
Why Standard Liability Limits Fall Short
Many drivers and homeowners carry liability limits that feel adequate until a serious claim occurs. State minimums for auto liability are often surprisingly low. In some states, the minimum bodily injury liability requirement is 25,000 dollars per person and 50,000 dollars per accident. A single hospital stay after a serious collision can easily exceed those amounts, and that does not include lost wages, pain and suffering, or future medical care.
Homeowners policies have similar constraints. A typical policy might include 300,000 dollars in personal liability coverage, which sounds substantial until you consider a lawsuit involving a serious injury on your property or a claim related to your teenager causing harm to someone else. Jury awards in liability cases can reach into the millions, and your personal assets become the target once policy limits are exhausted.
Even if you do not have substantial assets today, a large judgment can follow you for years. Wages can be garnished, and future income can be affected. An umbrella policy provides a buffer that protects not just what you have now, but also what you will earn in the future. This is why financial advisors often recommend umbrella coverage for anyone with meaningful income or assets to protect.
Who Needs Umbrella Insurance Most
Umbrella policies are not just for the wealthy. Anyone with assets, income, or exposure to liability risk can benefit from the extra layer of protection. The following groups are particularly strong candidates:
- Homeowners and renters: Property ownership or occupancy creates liability exposure, from slip-and-fall accidents to dog bites and injuries caused by household members.
- Drivers with significant commutes: More time on the road increases the chance of an at-fault accident, especially in high-traffic areas where serious injuries are more likely.
- Families with teenagers: New drivers are statistically more prone to accidents, and the resulting claims can quickly exceed standard auto liability limits.
- Owners of rental properties or vacation homes: Additional properties mean additional liability exposure that a single homeowners policy may not fully address.
- Individuals with high income or visible assets: High earnings and accumulated savings make you a more attractive target for lawsuits and increase the financial impact of an uncovered claim.
Beyond these categories, anyone who participates in activities that carry liability risk, such as coaching youth sports, hosting events at home, or owning a boat or ATV, should evaluate whether an umbrella policy makes sense. The cost is often modest relative to the protection provided, and the peace of mind can be significant.
What Umbrella Policies Typically Cover
Umbrella insurance covers a range of personal liability claims that go beyond the limits of your underlying policies. While specific coverage varies by insurer and policy form, common covered claims include:
- Bodily injury caused by you or a household member, including accidents on your property or away from home
- Property damage for which you are legally responsible
- Personal injury claims such as libel, slander, defamation, false arrest, and invasion of privacy
- Legal defense costs, which can be substantial even when you are not ultimately found liable
- Claims arising from certain personal activities, such as renting a car or operating a boat or watercraft
It is important to understand what umbrella policies generally do not cover. Business-related liability, intentional acts, and certain professional activities are typically excluded. If you run a business from home or provide professional services, you may need separate commercial or professional liability coverage. Some umbrella policies also exclude claims related to uninsured or underinsured motorist coverage, so it is worth reviewing the details with your agent.
Another key point is that umbrella coverage is not a substitute for adequate underlying limits. Most insurers require you to carry specific minimum liability limits on your auto and home policies before they will issue an umbrella policy. For example, an insurer might require 250,000 dollars per person and 500,000 dollars per accident in auto liability, along with 300,000 dollars in homeowners liability. Meeting these requirements ensures that your primary policies respond first, and the umbrella serves as the second layer of protection.
Cost of Umbrella Insurance and How to Evaluate It
One of the most appealing aspects of umbrella insurance is its cost relative to the protection it provides. A one million dollar umbrella policy often costs between 150 and 300 dollars per year for an individual, with additional increments of coverage available at a relatively low marginal cost. Several factors influence the premium, including the number of vehicles and properties you insure, the number of drivers in your household, and your claims history.
When evaluating whether an umbrella policy is worth the cost, consider the value of your assets and your future earning potential. If you have significant savings, equity in your home, or a high income, the financial downside of an uncovered liability claim can be devastating. The annual premium for an umbrella policy is often a small fraction of what you could lose in a single lawsuit.
It is also worth comparing umbrella policies from different insurers. Coverage terms, exclusions, and underlying limit requirements can vary, so reading the policy details is important. Working with a licensed insurance agent can help you understand the differences and choose a policy that fits your needs. For a broader look at how public and private coverage options compare, our guide on private vs public health insurance USA explained provides useful context on how different insurance structures protect consumers.
How to Choose the Right Umbrella Limits
Selecting the right umbrella limit is a balance between cost and protection. A common starting point is one million dollars, which covers many serious claims. However, if you have substantial assets or a high income, you may want to consider higher limits, such as two million or five million dollars. The additional premium for higher limits is often surprisingly affordable.
To determine an appropriate limit, add up your assets, including home equity, savings, investments, and retirement accounts. Then consider your future income and any foreseeable liability risks. If the total value at risk exceeds one million dollars, a higher umbrella limit may be appropriate. Some advisors suggest carrying an umbrella limit at least equal to your net worth, and possibly more if you have significant future earnings potential.
It is also important to review your underlying policies regularly. As your assets grow or your family situation changes, your liability exposure may increase. An annual review with your insurance agent can help ensure your umbrella coverage keeps pace with your needs.
Steps to Buy Umbrella Insurance
Purchasing an umbrella policy is a straightforward process, but it does require some preparation. The following steps outline a practical approach:
- Review your current policies: Check the liability limits on your auto, home, or renters insurance to see whether they meet the minimum requirements for an umbrella policy.
- Estimate your assets and income: Calculate your net worth and consider your future earnings to determine how much coverage you need.
- Compare quotes: Contact multiple insurers or work with an independent agent to compare umbrella policy quotes and coverage terms.
- Choose your limit: Select a limit that adequately protects your assets and income, keeping in mind that higher limits are often available at a modest additional cost.
- Maintain underlying coverage: Keep your auto and home liability limits at or above the levels required by your umbrella insurer, and review them annually.
After you purchase an umbrella policy, keep documentation of your coverage and review it whenever your circumstances change. If you acquire a new property, add a teenage driver, or significantly increase your income, revisit your umbrella limits to ensure they still provide adequate protection.
Common Misconceptions About Umbrella Insurance
There are several misconceptions about umbrella insurance that can lead people to overlook this valuable coverage. One common myth is that umbrella policies are only for the wealthy. In reality, anyone with income or assets to protect can benefit, and the cost is often quite low. Another misconception is that umbrella coverage duplicates existing liability coverage. In fact, it is designed to supplement, not replace, your primary policies by responding after those limits are exhausted.
Some people believe that their homeowners or auto policy will cover any liability claim, no matter how large. As discussed earlier, standard policies have limits, and those limits can be exhausted quickly in a serious claim. An umbrella policy fills that gap. Others assume that umbrella coverage is complicated or difficult to obtain. In practice, the application process is usually simple, and many insurers offer umbrella policies as an add-on to existing coverage.
Finally, some consumers worry that filing a claim under an umbrella policy will lead to higher premiums or cancellation. While any claim can affect your insurance history, umbrella claims are relatively rare, and the primary concern should be protecting your assets from a catastrophic loss. Discussing your specific situation with a licensed agent can help you understand how claims might affect your policies.
Umbrella Insurance and Your Overall Financial Plan
Umbrella insurance is one component of a comprehensive financial plan. It works alongside health insurance, life insurance, and disability coverage to protect your family from a range of risks. While health insurance addresses medical costs and life insurance provides for your loved ones after your death, umbrella insurance protects your assets and income from liability claims.
If you are reviewing your insurance coverage, consider how umbrella insurance fits into your overall strategy. For many families, the combination of adequate auto and home liability limits plus an umbrella policy provides a strong foundation of protection. As your financial situation evolves, revisiting your coverage ensures that your protection keeps pace with your needs.
For more information on auto insurance coverage options and how they interact with umbrella policies, independent resources such as NewAutoInsurance can provide additional educational content. However, the most personalized guidance comes from a licensed insurance agent who can review your specific circumstances and recommend appropriate limits.
Understanding umbrella insurance extra liability protection explained in practical terms helps you make informed decisions about your coverage. Whether you are a homeowner, a parent, or simply someone with assets to protect, an umbrella policy can provide an affordable layer of security against the unexpected. Review your current liability limits, assess your risk exposure, and consider whether an umbrella policy belongs in your insurance portfolio.