What Does Car Insurance Cover for Rental Cars?
Understand what car insurance covers for rental cars, from liability to damage waivers. Call (833)-214-6397 for expert guidance on your coverage.
By Sophia Chen
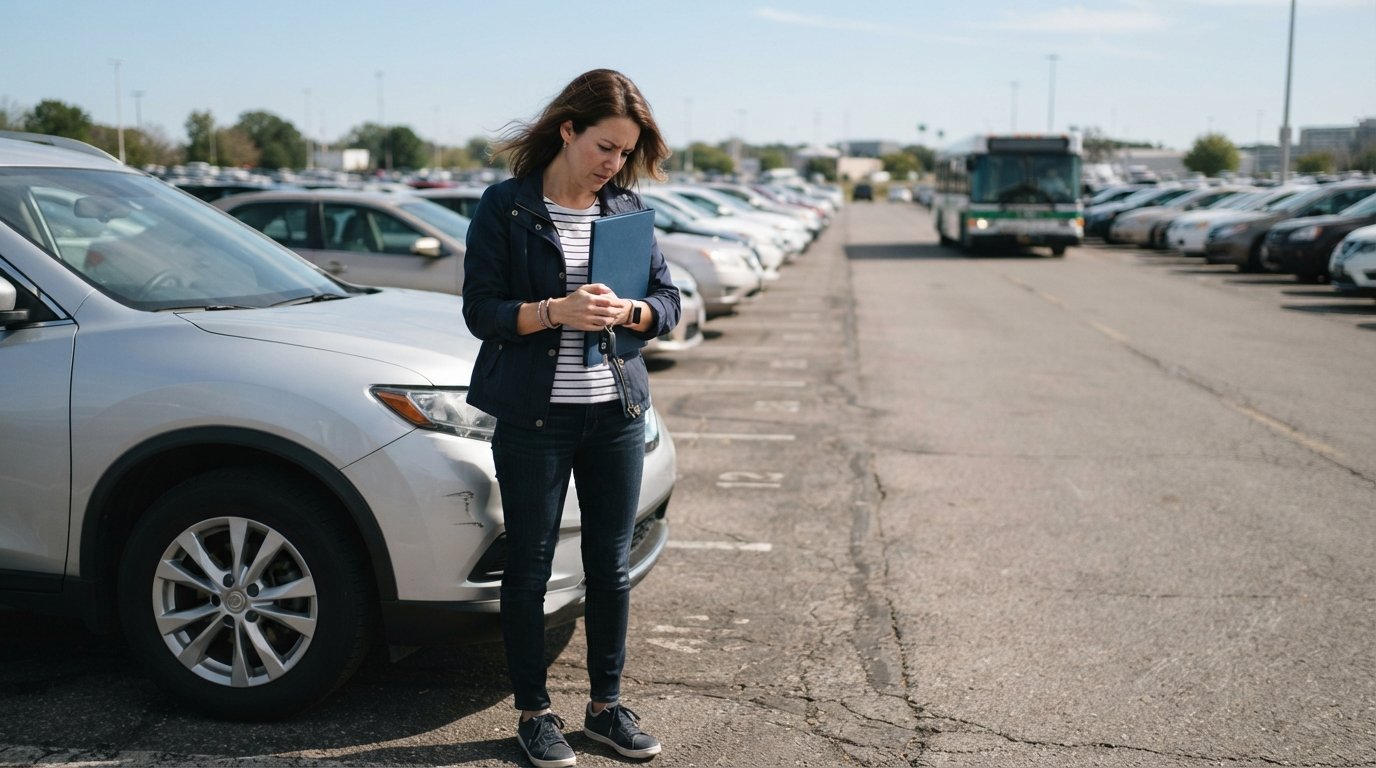
You step off the airport shuttle, keys in hand, and stare at the compact SUV you just rented. Before you drive off, a nagging question surfaces: if something happens to this car, will your personal auto policy pick up the tab, or are you on the hook for thousands in repairs? The answer is not a simple yes or no. It depends on the coverage you carry, the terms of your rental agreement, the country you are driving in, and sometimes even the credit card you used to book the reservation. Understanding what car insurance covers for rental cars can save you from expensive surprises at the counter and after you return home.
This guide breaks down how personal auto liability and collision coverage may extend to a rental, when the rental company's damage waiver makes sense, how domestic and international rentals differ, and how credit card benefits stack up against your own policy. Along the way, you will find practical steps to verify coverage before you drive off the lot.
How Personal Auto Insurance Usually Applies to Rental Cars
In most U.S. states, your personal auto policy extends certain coverages to a rental car you drive temporarily, as long as you are not using it for business purposes like rideshare driving or delivery work. This extension is not automatic in every situation, and it is not unlimited. The coverage you carry on your own vehicle typically follows you to a rental, but the limits and deductibles that apply are usually the same as those on your personal policy. If you carry state-minimum liability limits, for example, those low limits may not be enough to cover damage or injuries in a serious accident.
Two main types of coverage matter here: liability and physical damage (collision and comprehensive). Liability coverage pays for injuries or property damage you cause to others. Collision coverage pays to repair or replace the rental car itself if you hit something or another vehicle. Comprehensive coverage handles non-collision events like theft, fire, or weather damage. If you decline both collision and comprehensive on your personal policy, you likely have no physical damage protection for the rental, even if your liability coverage still applies.
There are exceptions and conditions to keep in mind. Your policy may not extend to rentals in certain countries, to long-term rentals beyond a specified number of days, or to vans and trucks above a certain weight. Some policies exclude coverage for rentals used for business purposes. Before you rely on your personal auto policy, read the rental car section of your policy or call your insurer to confirm exactly how your coverage applies to the vehicle class and rental duration you are considering. For a broader look at how different insurance products fit together, InsuranceAdvisers offers educational resources that can help you compare coverage options.
Here is a quick checklist to verify your personal auto coverage before renting:
- Confirm that your policy extends to rental cars and note any vehicle class restrictions (for example, no large vans or exotic cars).
- Check whether your liability limits are high enough to cover a serious accident; state minimums are often too low.
- Verify that you carry collision and comprehensive coverage, and understand the deductible that would apply to a rental claim.
- Ask whether your policy covers loss of use and administrative fees that rental companies may charge after an accident.
- Confirm the maximum rental period your policy allows (some policies limit coverage to 30 days or less).
If any of these points are unclear, get written confirmation from your insurer. A five-minute phone call can prevent a costly misunderstanding at the rental counter.
When the Rental Company's Damage Waiver Makes Sense
The rental company will almost always offer a collision damage waiver (CDW) or loss damage waiver (LDW), often at a daily rate that adds up quickly. This product is not insurance in the traditional sense; it is a waiver that shifts responsibility for damage to the rental company, subject to the terms of the agreement. The sales pitch can be aggressive, and the cost can add 20 to 50 percent to your daily rental rate. The question is whether the waiver is worth it given the coverage you already have.
For many travelers with solid personal auto coverage, the waiver is optional. Your collision and comprehensive coverage may already handle damage to the rental, and your credit card may provide secondary or primary coverage as a backup. However, there are situations where the waiver makes sense: you do not carry collision or comprehensive coverage on your personal policy; your deductible is very high; you are renting in a country where your U.S. policy does not apply; or you want the simplicity of walking away from the counter with no financial exposure for damage. The waiver also covers administrative fees and loss of use charges that your personal policy might not fully reimburse.
Consider a practical example. Suppose you carry a $1,000 deductible on your personal auto policy and rent a car for a week. If you decline the waiver and damage the bumper in a parking garage, you would file a claim with your insurer and pay the first $1,000 of the repair cost. The claim could also affect your premium at renewal. If the waiver costs $25 per day, that is $175 for the week, which may be less than your deductible and avoids a claim on your record. In that scenario, the waiver could be a reasonable purchase. On the other hand, if you have a $250 deductible and a clean claims history, self-insuring through your personal policy may be the more economical choice.
Before you decide, review the waiver terms carefully. Some waivers exclude certain types of damage, such as damage from driving on unpaved roads or damage to the roof or undercarriage. The waiver may be void if you violate the rental agreement, for example by letting an unauthorized driver operate the car or by driving under the influence. Read the fine print and ask the agent to clarify what is and is not covered.
Domestic Versus International Rentals: Coverage Differences
Your personal auto policy is a U.S. contract, and its territorial scope is usually limited to the United States, its territories and possessions, and sometimes Canada. If you rent a car in Mexico or Europe, your U.S. policy almost certainly will not provide coverage. Some policies extend liability coverage to Canada, but physical damage coverage may still be excluded or limited. International rentals require a different approach.
In many foreign countries, liability insurance is mandatory and is included in the rental rate or sold separately at the counter. That local liability insurance may provide only the minimum required by law, which can be low. You may be able to purchase supplemental liability insurance from the rental company or a third-party provider. For damage to the rental car itself, you will generally need to rely on the rental company's damage waiver or a separate rental car insurance policy purchased for the trip. Credit card coverage may help in some countries, but it often excludes certain countries and vehicle types, and it may be secondary to other coverage.
If you are renting internationally, plan ahead. Check your personal auto policy for territorial restrictions. Contact your credit card issuer to confirm whether rental coverage applies in the country you are visiting. Consider purchasing a standalone rental car insurance policy that specifically covers international rentals. And do not assume that your U.S. coverage will follow you across the border; in most cases, it will not.
For domestic rentals, the picture is generally simpler. Your personal auto policy likely applies, and your credit card may provide secondary coverage. The main variables are your policy limits, your deductible, and whether you carry collision and comprehensive coverage. Even within the United States, however, there can be variations. Some states have different rules for rental car coverage, and some policies treat rentals differently depending on whether they are in-state or out-of-state. Reading your policy and confirming with your insurer remains the safest approach.
Credit Card Rental Benefits Versus Your Own Policy
Many major credit cards offer rental car coverage as a benefit, but the details matter enormously. Some cards provide primary coverage, meaning they pay first for damage to the rental car without requiring you to file a claim with your personal auto insurer. Other cards provide secondary coverage, meaning they pay only after your personal auto insurance has paid its share, including your deductible. The distinction is critical: primary coverage can protect your personal policy from a claim, while secondary coverage mainly helps with out-of-pocket costs after your insurer pays.
Credit card coverage typically applies only when you use that card to pay for the entire rental and decline the rental company's damage waiver. It usually covers physical damage to the rental car, and sometimes towing and loss of use charges, but it rarely covers liability (injuries or property damage to others). The coverage is also subject to exclusions: it may not apply to certain vehicle types (exotic cars, large vans, trucks), to rentals longer than a specified period (often 15 to 31 days), or to rentals in certain countries (commonly Israel, Jamaica, and others). Some cards exclude coverage for rentals in Mexico altogether.
When comparing credit card coverage to your personal auto policy, consider the following factors:
- Primary versus secondary: Primary card coverage can keep a rental claim off your personal auto policy, protecting your premium and claims history.
- Deductible and limits: Your personal policy may have a deductible and coverage limits; card coverage may have its own limits and may not cover the full value of an expensive rental.
- Exclusions: Both your policy and your card have exclusions; read both sets of terms to identify gaps.
- Administrative burden: Filing a claim with a credit card issuer can involve more paperwork and take longer than filing with your auto insurer, but it may be worth it to avoid a personal policy claim.
A practical approach is to stack coverage intelligently. If your credit card offers primary rental coverage, you may be able to rely on it for physical damage and use your personal auto liability coverage for injuries or property damage to others. If your card offers only secondary coverage, your personal auto policy will be the first payer for damage, and the card may help with the deductible. If you do not carry collision and comprehensive coverage, your card's coverage may be your only protection for the rental car itself, so confirm its terms before you travel. For related guidance on how health insurance questions can arise during travel, see our article on does health insurance cover dry needling.
Practical Steps to Confirm Coverage Before You Rent
Coverage questions are best resolved before you arrive at the rental counter, when you have time to review documents and make calls. A few simple steps can clarify what car insurance covers for rental cars in your specific situation and help you avoid unnecessary purchases or dangerous gaps.
First, review your personal auto policy's declarations page and the rental car section of the policy jacket. Look for the territorial scope, the definition of a covered auto, and any exclusions related to rental vehicles. Second, call your insurer and ask directly: does my policy cover a rental car, and if so, what are the limits and deductible? Ask about loss of use and administrative fees, which rental companies often charge after an accident. Third, contact your credit card issuer and ask whether your card provides primary or secondary rental coverage, what vehicle types and countries are excluded, and what documentation is required for a claim. Fourth, decide whether to purchase the rental company's damage waiver based on the gaps you identify. If your personal policy and card together provide solid coverage, you can likely decline the waiver. If there are gaps, the waiver may be a reasonable cost.
Finally, keep documentation with you. Save a copy of your insurance card, your policy's rental car provisions, and your credit card benefit terms on your phone or in your travel folder. If an accident happens, you will need to report it promptly to the rental company, your insurer, and possibly your credit card issuer. Knowing the claims process in advance can make a stressful situation more manageable.
Renting a car does not have to be a gamble. By understanding how your personal auto policy, the rental company's damage waiver, and your credit card benefits interact, you can make an informed choice that fits your risk tolerance and budget. Whether you are renting for a weekend road trip or a week-long business travel, a few minutes of preparation can protect you from unexpected costs and give you confidence on the road.