Wildfire Risk Home Insurance Non-Renewal: What to Do Now
A wildfire risk home insurance non-renewal is not the end. Get a step-by-step plan to find coverage fast. Call 8332146397 for help.
By Seren Whitlock
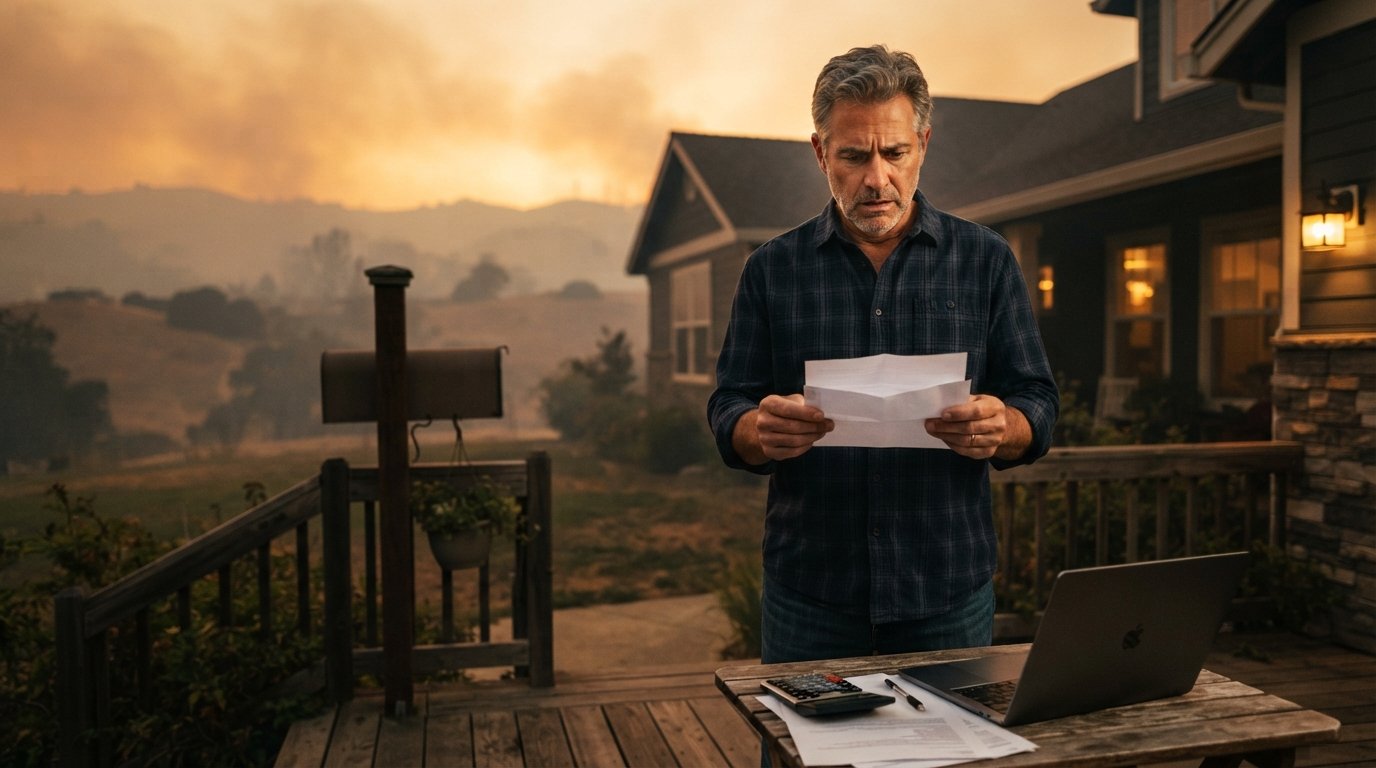
Receiving a non-renewal notice from your home insurance company is jarring, especially when you have lived in the same house for years and never filed a claim. In many wildfire-prone states, however, insurers are reassessing risk at scale, and thousands of homeowners are learning that a clean claims history no longer guarantees renewal. The notice usually arrives 45 to 120 days before your policy expires, depending on state law, and it can feel like a countdown clock. The good news is that you are not powerless. There are concrete, time-sensitive steps you can take to protect your coverage, your mortgage, and your financial stability.
This guide walks through why non-renewals happen, how to read the notice carefully, what to do in the first two weeks, how to shop for replacement coverage, and how to appeal or push back when a decision seems unfair. It also explains the role of state-backed insurers of last resort, the FAIR plans that operate in many high-risk areas, and the practical home-hardening steps that can make you a more attractive risk to a new carrier. If you are also new to homeownership and still learning how policies are structured, a primer on home insurance coverage for new homeowners can help you understand what is at stake before you start comparing quotes.
Why Insurers Are Sending Non-Renewal Notices in Wildfire Zones
Insurance companies do not cancel policies on a whim. A non-renewal is a business decision driven by actuarial models, reinsurance costs, and regulatory constraints. In wildfire-prone regions, three forces have converged to make certain ZIP codes nearly uninsurable through standard markets. First, catastrophic losses from recent fire seasons have drained carrier reserves and pushed reinsurance premiums sharply higher. Second, state regulators have limited how much insurers can raise rates in a single year, which pushes carriers to shrink their exposure instead by non-renewing policies in the highest-risk areas. Third, improved wildfire modeling now allows insurers to score individual properties with far more granularity than in the past, so a home that once passed underwriting can suddenly fall outside the carrier's appetite.
It is also important to understand the difference between a cancellation and a non-renewal. A cancellation typically happens mid-term and is often tied to non-payment, fraud, or a material change in the property. A non-renewal happens at the end of the policy term and is usually about risk. State laws treat these two events differently, and non-renewals generally come with more notice and more consumer protections. If your notice cites "underwriting guidelines" or "risk concentration" rather than a specific problem with your home, you are dealing with a portfolio decision, not a personal one.
Some states have also seen carriers withdraw entirely from the homeowners market. When that happens, every policy in the state is non-renewed, and the notice may come from a company that is exiting the line of business altogether. In those situations, appealing to the carrier is unlikely to help, and your energy is better spent finding a new policy through a surplus lines carrier, a regional insurer, or a state-backed plan.
Read Your Non-Renewal Notice Carefully Before You Do Anything Else
Before you call anyone, sit down with the notice and read it line by line. The document contains deadlines, contact information, and often a stated reason for the decision. Missing a deadline can cost you your right to appeal or to request an extension. Look for the effective date of the non-renewal, the number of days of notice provided, and whether the carrier offers a reconsideration process. Some notices include a checklist of mitigation steps that, if completed, may lead the carrier to reverse its decision.
You should also verify that the notice is compliant with your state's rules. Most states require 30 to 120 days of advance notice for non-renewal, and some require longer notice in wildfire zones. If the notice arrived late or omits required disclosures, you may have grounds to file a complaint with your state department of insurance. That complaint will not force the carrier to renew, but it can buy you time and sometimes triggers a review that reverses the decision.
Finally, check whether the non-renewal affects only your homeowners policy or also your auto, umbrella, or other lines. Some carriers non-renew the entire account when they exit a region, while others only drop the property policy. Knowing the scope helps you plan a coherent replacement strategy rather than piecing together coverage one line at a time.
Your First Two Weeks: A Step-by-Step Action Plan
The window between receiving a non-renewal notice and losing coverage is short, and the decisions you make in the first two weeks shape everything that follows. The goal is to avoid a lapse in coverage, because a gap of even one day can trigger your mortgage lender's force-placed insurance, which is typically far more expensive and far less protective than a standard policy. Work through the following steps in order.
- Confirm the deadline and your mortgage obligations. Contact your lender or escrow servicer and explain the situation. Most mortgages require continuous hazard insurance, and lenders can and will purchase force-placed coverage if you lapse. Ask what proof of replacement coverage they need and how quickly.
- Request a written explanation and your loss runs. Ask the carrier for the specific reason for non-renewal and a copy of your claims history. If the reason is a data error, such as an incorrect roof age or an incorrect wildfire score, you can correct it.
- Ask about reconsideration and mitigation credits. Some carriers will reconsider if you complete a home-hardening inspection or a defensible space evaluation. Ask whether a mitigation credit would change the underwriting decision.
- Start shopping immediately. Do not wait until the final week. Independent agents and online comparison tools can surface options from regional carriers, surplus lines markets, and state-backed plans that you may not find on your own.
- Document everything. Keep copies of every notice, email, and phone log. If you later need to file a complaint or prove continuous coverage, this record is your best evidence.
Once you have completed these steps, you will have a clearer picture of whether your current carrier can be persuaded to stay, and you will have started the parallel process of finding a replacement. Do not assume that the first quote you receive is the best or only option. In high-risk markets, pricing varies dramatically between carriers, and some insurers are actively writing new business in areas where others are retreating.
How to Shop for Replacement Coverage in a High-Risk Area
Shopping for homeowners insurance after a wildfire-related non-renewal is different from a routine annual review. You are not just comparing price. You are evaluating whether a carrier is genuinely willing to write in your area, whether it has the financial strength to pay claims after a major fire, and whether its coverage terms leave gaps that could cost you later. Start by working with an independent agent who represents multiple carriers, including regional and surplus lines insurers. Captive agents who represent a single company will only be able to offer that company's products, which may not include a viable option for your property.
When you request quotes, be upfront about the non-renewal and the reason. Hiding it will not help, because carriers share loss history through databases, and a misrepresentation on an application can void coverage later. Instead, present the non-renewal as a manageable event and emphasize any mitigation work you have done. Photos of cleared brush, a new Class A roof, ember-resistant vents, and a documented defensible space plan can all improve your odds of being accepted.
Pay attention to the details that matter in wildfire country: whether the policy includes replacement cost or actual cash value, whether debris removal is capped, whether additional living expenses have adequate limits and duration, and whether the carrier offers a wildfire-specific endorsement. Some policies exclude fire damage entirely in certain zones, which is a deal-breaker. Read the exclusions page before you sign anything.
State-Backed Insurers of Last Resort and FAIR Plans
If the standard market will not write your home, most wildfire-prone states offer a residual market option, often called a FAIR plan or a state-backed insurer. These programs exist to provide basic property coverage when no private carrier will. They are not charities, and they are not cheap. FAIR plans typically offer limited coverage, often on an actual cash value basis, and they may exclude liability, theft, or other perils that a standard policy would include. Many homeowners use a FAIR plan for the dwelling and then purchase a separate difference in conditions policy to fill the gaps.
Applying for a FAIR plan takes time, and the process varies by state. You will usually need proof that you have been declined by at least one admitted carrier, and you may need an inspection. Start the application as soon as you receive your non-renewal notice, because processing can take several weeks. Do not wait until the last minute, and do not assume that a FAIR plan is your only option. Some regional carriers and surplus lines insurers write in high-risk areas and offer broader coverage than a FAIR plan, even if the premium is higher.
It is also worth checking whether your state has a mitigation incentive program that offers grants or premium discounts for home-hardening. Several states fund these programs specifically to keep homes insurable in wildfire zones. A grant for a new roof or ember-resistant vents can lower your risk score and make you eligible for a private policy again.
Can You Appeal a Non-Renewal Decision?
Appeals do not always succeed, but they are worth attempting when the reason for non-renewal is factual and correctable. Common grounds for a successful appeal include an incorrect wildfire risk score, an outdated roof age, a misreported claims history, or a mitigation step that the carrier did not know about when it made its decision. To appeal, you typically need to submit a written request, supporting documentation, and sometimes a professional inspection report. Keep the tone factual and professional. Emotional arguments rarely change underwriting decisions, but evidence does.
If the carrier denies your appeal, you can escalate to your state department of insurance. A complaint will not force a carrier to renew, but it can prompt a review and, in some cases, reveal that the carrier failed to follow its own underwriting guidelines or state notice requirements. Regulators track these complaints, and persistent patterns can lead to broader action. Even if your individual case is not reversed, filing a complaint adds to the record that policymakers use when they consider market reforms.
In some states, you may also have the right to request a hearing or to participate in a mediation program. These options are not available everywhere, and they usually apply only to certain policy types or carriers. Your state department of insurance website is the best source for current rules and deadlines.
Home Hardening: Lower Your Risk and Improve Your Insurability
Home hardening is not just a talking point. It is one of the few levers you control when insurers are reassessing wildfire risk. The goal is to reduce the likelihood that your home ignites during a wildfire, and to make that reduction visible to underwriters. The most impactful steps include installing a Class A fire-rated roof, enclosing eaves, screening vents with ember-resistant mesh, clearing debris from gutters and roofs, and maintaining a defensible space zone of at least five feet immediately around the home and up to 100 feet in some areas.
Document your work with dated photos, receipts, and if possible a third-party inspection report. Some carriers offer premium discounts or even guaranteed renewal for homes that meet recognized wildfire mitigation standards, such as those published by the National Fire Protection Association or state-specific programs. Ask your agent which standards your carrier recognizes, and get the inspection in writing. A formal mitigation report can be the difference between a decline and an approval.
It is also worth reviewing your broader insurance portfolio while you are making changes. If you are also shopping for auto coverage, resources such as free auto insurance quotes online can help you compare rates and understand how bundling may affect your overall premium. Bundling homeowners and auto policies does not guarantee acceptance in a high-risk area, but it can sometimes improve pricing on the lines that are still available to you.
What to Do If You Cannot Find Coverage Before Your Policy Expires
If your deadline is approaching and you still do not have a replacement policy, you have a few options, none of them ideal but all of them better than a lapse. First, contact your current carrier and ask for a short extension. Some carriers will grant a 30-day extension while you finalize replacement coverage, especially if you can show that you are actively working with an agent. Second, contact your mortgage servicer and explain the situation before the lapse occurs. Lenders are often more flexible when they are informed in advance, and they may allow a brief gap if you can demonstrate that coverage is imminent.
Third, consider a surplus lines carrier as a bridge. Surplus lines insurers are not admitted in your state, which means they are not backed by the state guaranty fund, but they can write coverage that admitted carriers will not. They are regulated differently, and you should read the policy carefully, but they can provide legitimate coverage when no other option exists. Fourth, apply to the FAIR plan immediately if you have not already. Even if the policy is limited, it satisfies your mortgage requirement and keeps you from being force-placed.
Finally, do not give up on the standard market permanently. Wildfire risk is dynamic, and carriers re-enter markets when conditions change. Keep your mitigation documentation current, maintain a clean claims history, and re-shop every year. A policy that was unavailable this year may be available next year, especially if you can show that your home is a lower risk than the average property in your area.
Non-renewal is a stressful event, but it is not the end of your ability to protect your home. By acting quickly, reading your notice carefully, appealing when you have grounds, shopping aggressively, and investing in home hardening, you can often secure coverage and even improve your long-term position. Start with the deadlines, work the plan, and lean on licensed professionals who understand your state's market. The sooner you begin, the more options you will have.