Average Home Insurance Cost by ZIP Code: Key Factors
See how average home insurance cost by ZIP code factors like weather risk, crime, and rebuilding costs shape your premium, plus ways to lower it without moving.
By Liora Ashcroft
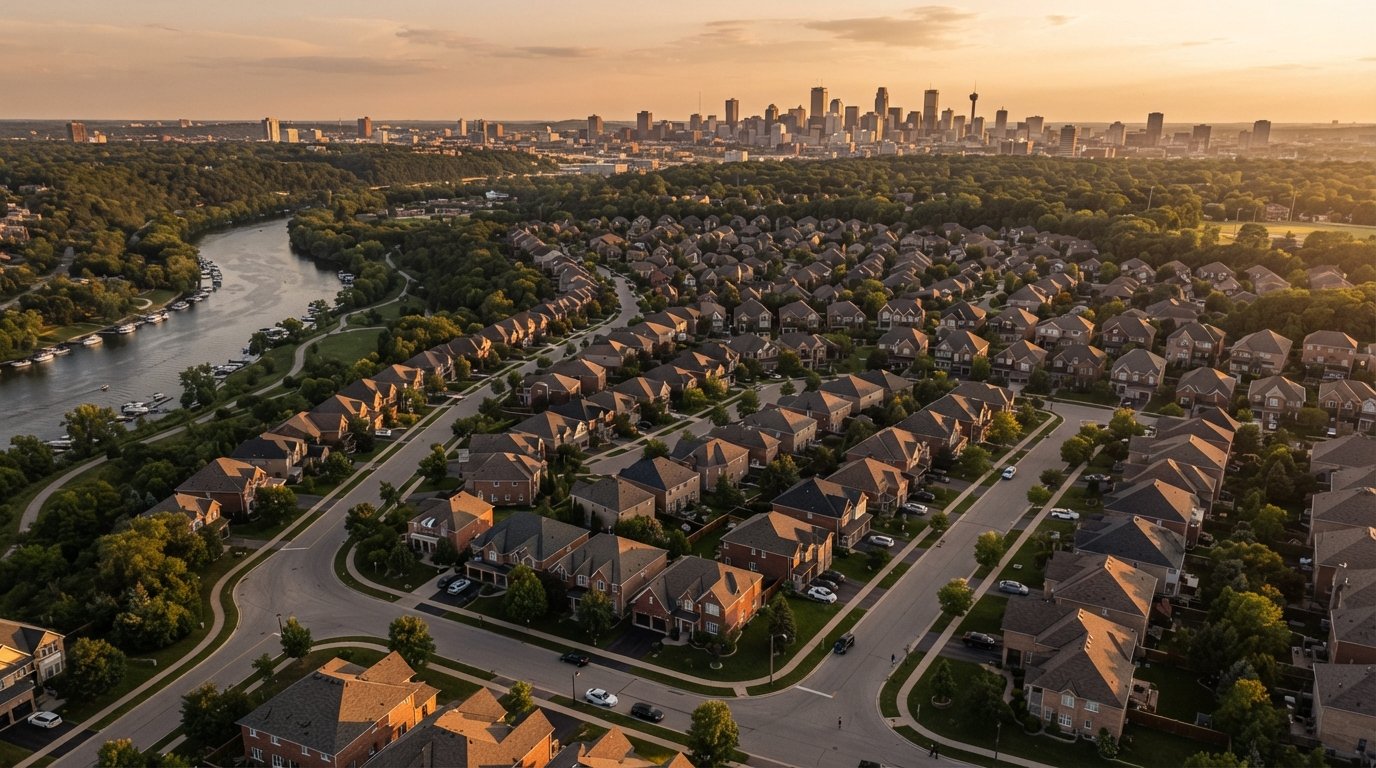
Your ZIP code is one of the most powerful predictors of what you will pay for homeowners insurance, often creating premium gaps of hundreds or even thousands of dollars between neighborhoods in the same metro area. Two identical houses with identical replacement costs can carry dramatically different annual premiums simply because one sits in a ZIP code exposed to hailstorms, wildfires, or coastal wind, while the other enjoys milder weather and stronger local fire protection. Understanding the average home insurance cost by ZIP code factors helps you see why your quote looks the way it does, and more importantly, it shows you where there is room to negotiate, adjust coverage, or shop more effectively. This guide breaks down the specific variables tied to your ZIP code, explains how insurers weigh them, and gives you a practical framework for comparing quotes without getting lost in the noise.
Why ZIP Code Matters More Than Most Homeowners Realize
Insurance is a business of predicting loss. When a carrier prices a homeowners policy, it is essentially asking one question: how likely is this home to generate a claim, and how expensive would that claim be? Your ZIP code acts as a shortcut for dozens of risk signals that would otherwise take weeks to evaluate individually. Catastrophe modeling, claims databases, fire station response times, building code enforcement, and even local litigation trends all get mapped to geographic areas, and your ZIP code is the smallest unit most insurers use for retail pricing.
That is why the same $350,000 house can cost $1,400 a year in one ZIP code and $4,200 a year ten miles away. It is rarely about the house itself. It is about what surrounds the house, what has happened to similar homes nearby, and what insurers expect to happen in the next twelve months. In states like Arkansas, where severe convective storms and tornadoes drive a large share of claims, geographic risk differences show up quickly in premiums, which is one reason regional cost guides such as Homeowners Insurance Cost in Arkansas vary so much from national averages.
ZIP code pricing is not perfectly precise. Some insurers use census tracts, rating territories, or even individual address-level models. But for the consumer, ZIP code remains the most visible and most comparable geographic factor, and it is the one you can actually research before you buy.
The Main ZIP Code Factors That Drive Home Insurance Costs
When you enter your ZIP code into a quote form, you are not just telling the insurer where to send mail. You are triggering a risk profile built from multiple overlapping data layers. The most influential factors fall into a handful of categories, and each one can move your premium meaningfully on its own.
- Severe weather and catastrophe exposure: Hail, wind, wildfire, hurricane, and winter storm risk are modeled at the ZIP level and can be the single largest premium driver in high-risk areas.
- Crime rates and theft risk: Property crime, vandalism, and theft claims raise premiums because they increase the frequency of smaller, predictable losses.
- Local construction and labor costs: Rebuilding costs vary by region due to labor wages, material availability, and contractor demand, which directly affects replacement cost estimates.
- Fire protection and emergency response: Distance to a fire hydrant or fire station, and the quality of local fire services, influence how much damage a home is expected to sustain.
- Building codes and enforcement: Stronger codes mean homes withstand storms better, which lowers expected losses and can reduce premiums.
Each of these factors is weighted differently depending on the insurer. One carrier may lean heavily on catastrophe models, while another gives more weight to local claims history. That is why the same ZIP code can produce quotes that differ by 40 percent or more between companies. It also explains why shopping multiple carriers is not just a nice idea, it is the single most effective way to control your premium within a given ZIP code.
There is also an important distinction between frequency and severity. A ZIP code with frequent small hail claims may see higher base rates, while a ZIP code with rare but catastrophic wildfire risk may see surcharges or restricted coverage. Understanding which type of risk dominates your area helps you ask better questions when comparing policies.
How Insurers Actually Use ZIP Code Data
Insurers do not simply look up a single number for your ZIP code and call it a day. They build rating territories, which are groups of ZIP codes or partial ZIP codes that share similar risk characteristics. A territory might cover an entire city, or it might split a city into three or four zones based on distance to the coast, flood zones, or crime patterns.
Within those territories, carriers layer additional data. They may pull loss runs from the past five to ten years, overlay catastrophe models from vendors like AIR or RMS, and adjust for reinsurance costs. Reinsurance is the insurance that insurers buy for themselves, and when reinsurance prices rise after a major disaster, those costs get passed down to homeowners in affected territories, sometimes across an entire state.
This is why premiums can change even when nothing about your home changes. If your ZIP code experiences a major hailstorm or wildfire season, every policy in that territory may see a rate adjustment at the next renewal. Conversely, if a territory goes several years without significant losses, some carriers may file for rate decreases to stay competitive. Your ZIP code is not a static input, it is a living risk score that updates as new data arrives.
For consumers, the practical takeaway is simple: your ZIP code sets a baseline, but your individual choices (deductible, coverage limits, roof age, claims history) determine where you land within that baseline. You cannot change your ZIP code easily, but you can change almost everything else.
Regional Examples: What Different ZIP Codes Actually Look Like
National averages hide enormous variation. According to typical industry data, the U.S. average annual homeowners insurance premium sits somewhere in the $1,700 to $2,500 range, but that number is almost meaningless without geographic context. In a low-risk Midwestern ZIP code, a $250,000 home might insure for $1,100 a year. In a Florida coastal ZIP code, the same home could easily exceed $6,000, and in some high-risk areas, private insurers may decline to write the policy at all, pushing homeowners into state-backed residual markets.
Wildfire zones in California and Colorado show a similar pattern. Insurers have grown more selective about which ZIP codes they will write, and in some cases they have paused new business entirely. Homeowners in those areas often face a choice between a high-priced surplus lines policy, a state FAIR plan, or going without coverage, which is rarely a good option given mortgage requirements.
Even within a single state, the spread can be striking. A ZIP code with a well-funded fire department, low crime, and modern building codes may see rates 30 to 50 percent below a neighboring ZIP code with older housing stock and weaker emergency services. This is not arbitrary. It reflects real differences in expected losses, and it gives you a concrete way to evaluate whether a quote is reasonable for your area.
If you are also shopping for auto coverage, the same geographic logic applies, and resources like new auto insurance guidance for U.S. drivers can help you see how ZIP code factors into vehicle premiums as well. Bundling home and auto is one of the few levers that can offset a high-risk ZIP code, often saving 10 to 25 percent across both policies.
How to Compare Home Insurance Quotes by ZIP Code
Comparing quotes effectively requires more than collecting a few numbers. You need to normalize the quotes so you are comparing the same coverage, the same deductible, and the same replacement cost estimate. Otherwise, a lower premium may simply reflect weaker coverage, and you will only discover that when you file a claim.
Here is a practical sequence that works for almost any ZIP code:
- Pull your replacement cost estimate first. Use a reputable estimator or ask each insurer for their dwelling coverage recommendation. If one quote uses $300,000 and another uses $400,000, the premiums are not comparable.
- Set a consistent deductible. Compare quotes at the same deductible, such as $1,000 or $2,500. A higher deductible lowers your premium, but you need to be able to cover it after a loss.
- Check coverage details, not just limits. Look at water backup coverage, wind and hail deductibles, roof valuation (actual cash value vs. replacement cost), and whether the policy includes ordinance or law coverage.
- Ask about ZIP-specific surcharges or restrictions. Some carriers apply wind or hail deductibles as a percentage of dwelling coverage in certain territories. Know this before you buy.
- Shop at least three to five carriers. Because each insurer weights ZIP code factors differently, the spread between the highest and lowest quote is often large enough to justify the extra effort.
After you have normalized the quotes, look at the pattern. If every carrier is high, your ZIP code is likely the dominant factor, and your best moves are raising your deductible, bundling policies, or improving your home's wind and water resistance. If only one or two carriers are high, you have found companies that do not want to write in your territory, and you can simply move on.
It also helps to re-shop every two to three years, even if you are happy with your current insurer. ZIP code risk models change, new carriers enter markets, and a company that was uncompetitive two years ago may now be the best option. Loyalty rarely pays in homeowners insurance, but informed shopping almost always does.
Ways to Lower Your Premium Without Moving
You cannot change your ZIP code, but you can change how your home is rated within it. Insurers reward certain behaviors and features, and many of these improvements pay for themselves within a few years through lower premiums.
Start with your roof, since it is the most common source of homeowners claims. A newer roof with impact-resistant shingles can qualify you for a significant discount in hail-prone ZIP codes. Similarly, storm shutters, reinforced garage doors, and wind-resistant construction can reduce premiums in coastal and tornado-prone areas. Some carriers offer specific Wind Mitigation or Fortified Home credits that stack on top of each other.
Your claims history also matters. Filing small claims, even if they are covered, can raise your premium at renewal and make you less attractive to new carriers. Many homeowners find that paying out of pocket for minor damage keeps their insurability intact and their rates lower over time. If you do file a claim, be prepared to explain it when shopping for new coverage.
Finally, consider your deductible strategically. Raising it from $1,000 to $2,500 or $5,000 can reduce your premium by 15 to 30 percent in high-risk ZIP codes. Just make sure you have that amount available in savings, because the deductible applies per claim, not per year. The goal is not the lowest premium, it is the best balance between premium savings and financial protection.
Home insurance is one piece of a broader insurance picture. If you are also reviewing health coverage, tools that help you compare U.S. insurance options across home, auto, health, and Medicare can save you time and help you spot bundling opportunities. And if a high-risk ZIP code is pushing your premium beyond what feels reasonable, it is worth getting quotes from several carriers before assuming the number is fixed. In most ZIP codes, it is not.