Does Homeowners Insurance Cover Foundation Damage?
Foundation damage coverage depends on the cause. Learn which perils are covered, which are excluded, and how to document a claim. Call (833)-214-6397 for guidance.
By Adnan Nazir
Foundation problems are among the most expensive and unsettling surprises a homeowner can face. A single crack in the basement wall or a sticking door can signal repairs that run into the tens of thousands of dollars. When that happens, the first question most people ask is simple: does homeowners insurance cover foundation damage? The answer is rarely a clean yes or no. It depends on what caused the damage, how your policy defines covered perils, and whether the loss falls inside a common exclusion such as earth movement or poor maintenance. Understanding those boundaries before a problem appears is the best way to avoid a financial shock later.
What Homeowners Insurance Typically Covers for Foundations
A standard homeowners policy, whether an HO-3 or HO-5 form, protects the dwelling and attached structures against specific risks known as perils. The foundation is part of the dwelling, so when a covered peril damages it, the policy can respond. The key word is covered. Insurers list the perils they pay for, and foundation damage caused by one of those listed events is generally eligible for a claim.
Common covered causes include fire, lightning, windstorms, hail, falling objects, and the weight of ice or snow. If a falling tree strikes the house and cracks the foundation, or a fire damages structural supports, the resulting foundation repair is usually part of the covered loss. Water damage from a sudden internal event, such as a burst pipe that saturates and destabilizes a section of footing, may also be covered, though the policy will typically pay to fix the pipe and the resulting damage, not the worn pipe itself.
It helps to think in terms of cause and effect. The foundation is rarely the direct target of a storm. More often, it is collateral damage from another covered event. That distinction matters because insurers evaluate the proximate cause, meaning the event that set the loss in motion. If that event is covered, the foundation repair usually follows. If it is excluded, the claim will likely be denied even when the visible damage looks severe.
Common Exclusions That Affect Foundation Claims
The reason so many foundation claims are denied is that the most frequent causes of foundation failure are explicitly excluded. Standard policies exclude earth movement, which covers earthquakes, landslides, mudslides, sinkholes, and settling or shifting of the ground. They also exclude damage from poor workmanship, faulty construction, and lack of maintenance. These exclusions exist because foundation deterioration is usually gradual and predictable, and insurers price policies around sudden, accidental events rather than long-term wear.
Water damage is another frequent source of confusion. Policies generally cover sudden and accidental water damage from inside the home, such as an appliance failure, but they exclude damage from repeated seepage, groundwater, surface water, and flooding. A foundation that slowly cracks because of poor drainage or a rising water table is usually not covered. Flood damage requires a separate flood policy, typically through the National Flood Insurance Program or a private carrier. Earthquake coverage is also a separate endorsement or policy in most states.
Here is a practical breakdown of how the most common causes are treated:
- Typically covered: fire, lightning, windstorm, hail, falling objects, and sudden internal water damage from a burst pipe.
- Typically excluded: earthquakes, landslides, sinkholes, settling, soil expansion, poor drainage, and groundwater seepage.
- Typically excluded: faulty workmanship, defective materials, and damage that developed slowly from neglected maintenance.
- Often available as an add-on: earthquake coverage, sinkhole coverage in select states, and limited water backup protection.
Because policy language varies by carrier and state, the exclusions section of your own contract is the authoritative source. Reading it before a loss occurs is far easier than arguing about it afterward. If you are comparing policy options, a resource such as this guide to insurance costs in Arkansas can help you understand how pricing and coverage levels interact, even though it focuses on a different line of insurance.
How Earth Movement and Settlement Exclusions Work
Earth movement exclusions are broad by design. They cover the shifting, rising, or sinking of land, and they apply whether the movement is natural or triggered by human activity such as excavation or blasting nearby. Settlement, which is the gradual sinking of a structure as soil compacts beneath it, is treated the same way. From an insurer's perspective, these are predictable geological processes rather than sudden accidents, and covering them would make standard policies unaffordable.
The settlement exclusion is the one that catches most homeowners off guard. A house built on expansive clay soil may experience cycles of swelling and shrinking as moisture levels change, and over years those cycles can crack a foundation. That is considered settlement or soil movement, not a covered peril. Even when the damage appears suddenly after a dry summer, the underlying process is gradual, and the claim is likely to be denied.
There are limited exceptions. Some states require insurers to offer sinkhole coverage, particularly in Florida and parts of the Southeast, and a few carriers sell endorsements that buy back certain earth movement risks. Earthquake coverage is widely available as a separate policy or endorsement. If you live in an area prone to these risks, ask specifically about buy-back options rather than assuming your standard policy will respond. The cost of an endorsement is almost always lower than the cost of a major foundation repair paid out of pocket.
Warning Signs of Foundation Problems and Documentation Tips
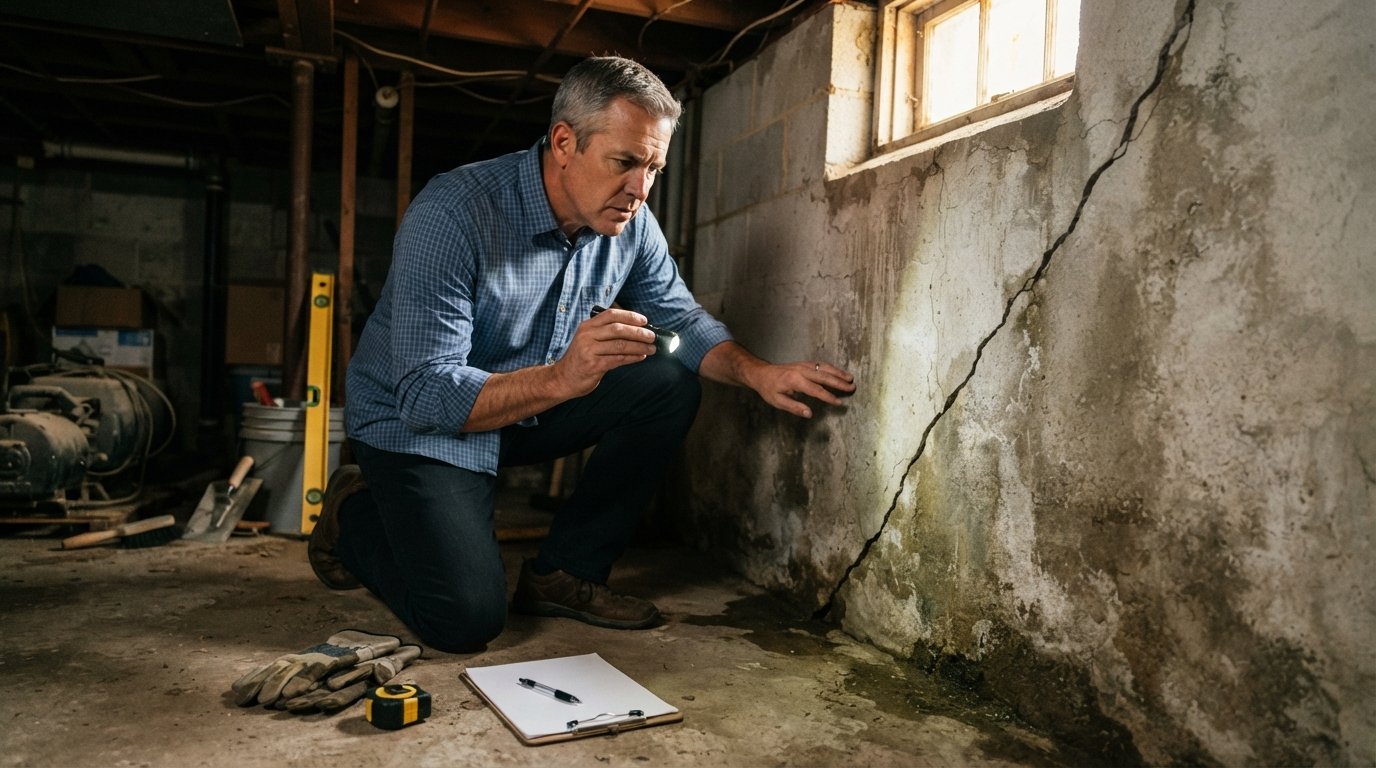
Foundation damage rarely appears overnight. Most problems announce themselves through a series of small clues that homeowners dismiss as cosmetic. Cracks in interior drywall, doors that no longer latch, uneven floors, and gaps around window frames are all worth noting. On the exterior, look for stair-step cracks in brick or block walls, separation where the foundation meets the siding, and visible tilting of chimneys or porches.
Documentation is your best protection if you ever need to file a claim. A dated record of the home's condition, ideally with photos taken at move-in and updated annually, establishes a baseline that helps distinguish a sudden covered event from long-term deterioration. Keep receipts for repairs and maintenance, and note the date any crack first appeared. If a storm or plumbing failure occurs, photograph the damage immediately, before any cleanup, and keep damaged materials until the adjuster has seen them.
A simple maintenance routine can reduce risk and strengthen your position with an insurer:
- Clean gutters and downspouts twice a year, and make sure water is directed at least six feet away from the foundation.
- Check the grading around the house and add soil where it slopes back toward the walls.
- Inspect the foundation and basement walls each spring for new cracks or moisture.
- Fix plumbing leaks promptly, especially slow drips under sinks and in crawl spaces.
- Keep a photo log with dates so any future claim has a clear timeline.
These steps do not just protect the house. They also demonstrate responsible maintenance, which matters if an insurer investigates whether a loss resulted from neglect. A well-documented home is easier to insure and easier to defend in a dispute.
When to File a Claim and When to Pay Out of Pocket
Filing a foundation claim is a significant decision, and it is not always the right one. A claim stays on your loss history for years and can affect your premium at renewal, even if it is denied. Before calling your insurer, get a professional inspection and a written repair estimate. That gives you a realistic number to weigh against your deductible and the likely impact on your policy.
A useful rule of thumb is to compare the repair cost to your deductible plus the expected premium increase over the next few years. If the repair is only slightly above your deductible, paying out of pocket may be cheaper in the long run. If the damage clearly stems from a covered peril such as a fallen tree or a burst pipe, filing is usually the right move, and prompt reporting helps preserve evidence.
When you do file, be specific about the cause and provide your documentation. Avoid describing the damage as settling or shifting, since those words trigger the earth movement exclusion. Instead, describe the event that caused the damage and let the adjuster evaluate it. If a claim is denied, you have the right to request a written explanation and to appeal. Many denials are resolved through a reinspection once additional evidence is provided.
For homeowners who want to compare coverage options or find a policy that includes helpful endorsements, working with a comparison service can simplify the process. Sites such as QuoteComparison let you review multiple quotes and coverage structures side by side, which makes it easier to spot whether earth movement or water backup protection is included before you buy. Taking that step now is far less stressful than discovering a gap after the foundation has already cracked.
Preventive Maintenance That Reduces Foundation Risk
Most foundation failures are preventable, at least in part. Water management is the single most important factor. Soil that stays consistently moist is less likely to expand and contract dramatically, and water that drains away from the house cannot undermine the footing. Extending downspouts, regrading the yard, and installing a French drain in problem areas are relatively inexpensive steps that pay for themselves many times over.
Vegetation matters too. Large trees planted close to the house draw moisture from the soil and can cause uneven settling, while roots can crack shallow foundations. Keep trees a safe distance away and monitor any that are already close. In drought-prone regions, soaker hoses or drip irrigation can help maintain stable soil moisture around the foundation during dry months.
Finally, schedule a professional foundation inspection every few years, especially if your home is more than 20 years old or sits on clay soil. An inspector can catch small issues before they become structural. That early warning gives you time to budget for repairs and to review your policy with a clear head, rather than making decisions in the middle of a crisis.
Foundation damage sits at the intersection of insurance, maintenance, and geology, and the coverage answer depends heavily on cause. Understanding what your policy includes, documenting your home's condition, and staying ahead of water and soil problems will protect both your house and your wallet. When in doubt, read the exclusions, ask your carrier directly, and get professional estimates before filing a claim. A little preparation now can save a great deal of money and frustration later.