Home Insurance Exclusions That Surprise Homeowners
Home insurance exclusions that surprise homeowners can lead to denied claims. Call (833)-214-6397 to review your policy and close coverage gaps.
By Everett Hale
You pay your premium every month, confident that your home is protected. Then a pipe bursts, a sinkhole opens, or a storm tears off part of your roof, and you file a claim only to discover that the damage is not covered. The truth is, home insurance policies are packed with exclusions, and many of them catch homeowners off guard. Understanding these gaps before a loss occurs is essential to protecting your financial investment. In this guide, we will walk through the most common home insurance exclusions that surprise homeowners, explain why certain claims are denied, and show you how to close the gaps with endorsements and careful policy review.
Why Home Insurance Exclusions Catch Homeowners Off Guard
Most people buy home insurance with a simple expectation: if something bad happens to my house, the insurance will pay for it. That assumption is understandable, but it is not how policies work. A standard homeowners policy (often an HO-3 form) covers a long list of named perils, such as fire, windstorm, hail, and theft, while excluding many others. The exclusions are buried in dense policy language, and many homeowners never read them until they need to file a claim.
The surprise often comes from the gap between what people think is covered and what the policy actually says. For example, you might assume that damage from a slow leak is covered because sudden water damage is covered. But insurers distinguish between sudden and accidental discharge (covered) and long-term seepage or maintenance neglect (usually excluded). Similarly, you might think your policy covers everything that could go wrong with your property, but standard policies exclude earth movement, neglect, and even certain types of mold. These home insurance exclusions that surprise homeowners are not hidden by design; they are simply not emphasized during the sales process.
Another reason these exclusions catch people off guard is that they often interact with other coverage parts. Your dwelling coverage might pay for water damage from a burst pipe, but your personal property coverage might not pay for the damaged furniture if the cause was excluded. Liability coverage might protect you if a guest is injured, but it will not protect you if the injury results from an intentional act or a business activity. Understanding how exclusions apply across different coverage parts is key to spotting gaps.
Common Perils Excluded by Standard Home Insurance Policies
Standard home insurance policies typically exclude a set of perils that are either catastrophic, predictable, or preventable. These exclusions are fairly consistent across most carriers, though some states and policy forms may vary. Here are the most common ones that surprise homeowners:
- Earth movement: This includes earthquakes, landslides, sinkholes, and mudflows. Damage from these events is almost always excluded unless you buy a separate earthquake or earth movement endorsement.
- Water damage from floods: Flooding from external sources (storm surge, overflowing rivers, heavy rain) is excluded. Flood insurance is a separate policy, typically through the National Flood Insurance Program (NFIP) or a private carrier.
- Neglect: If you fail to maintain your home and the damage results from that neglect (e.g., a leaky roof that you knew about but did not fix), the claim will likely be denied.
- Intentional loss: Damage you cause on purpose is never covered.
- Ordinance or law: If your home is damaged and you must rebuild to current building codes, the extra cost is often excluded unless you add an ordinance or law endorsement.
- Mold, fungus, and rot: These are typically excluded unless they result from a covered peril (like a burst pipe) and you have purchased additional coverage.
- Pests and insects: Damage from termites, rodents, or other pests is excluded because it is considered a maintenance issue.
- Wear and tear, deterioration: Gradual damage from age or poor maintenance is not covered.
These exclusions are not arbitrary. Insurers exclude them because they are either catastrophic and require separate underwriting (earthquakes, floods), or they are preventable through proper maintenance (neglect, pests, mold). The challenge for homeowners is that these exclusions are often not top-of-mind when they buy a policy. For instance, you might live in an area prone to wildfires and assume your policy covers fire, which it does, but you might not realize that smoke damage from a nearby fire could be covered while ash damage might have sublimits. Similarly, you might think your policy covers your home office equipment, but business property is often excluded or limited.
Understanding these exclusions is the first step toward closing the gaps. The next step is to review your declarations page and policy language carefully. As we noted in our article on home insurance premiums surging due to climate-driven disasters, insurers are tightening underwriting in high-risk areas, making it even more important to know exactly what is and is not covered.
Why Maintenance-Related Damage Is Often Denied
One of the most frustrating surprises for homeowners is when a claim is denied because the damage resulted from poor maintenance. Insurers expect you to take reasonable steps to maintain your home, and they exclude damage that results from neglect. This is not just a technicality; it is a fundamental principle of insurance. Insurance is designed to cover sudden and accidental events, not gradual deterioration that could have been prevented.
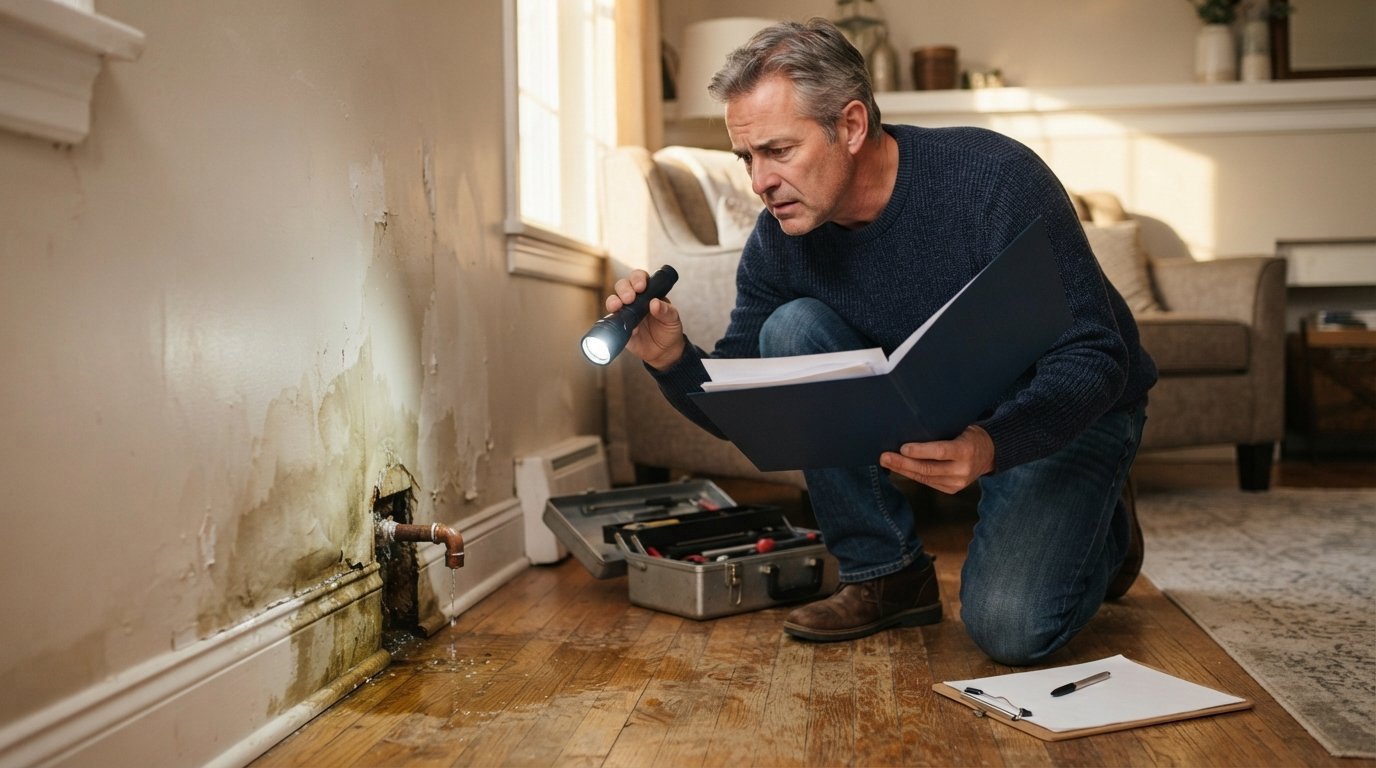
Consider a common scenario: a small leak in the roof goes unnoticed for months. Water slowly seeps into the attic and drywall, causing rot and mold. When you finally notice the damage and file a claim, the insurer may deny it because the damage resulted from long-term seepage and neglect. The same applies to plumbing leaks: a sudden burst pipe is covered, but a slow leak that has been corroding a pipe for years is not. Insurers often send adjusters who can tell the difference between sudden damage and long-term deterioration.
Maintenance-related exclusions also apply to exterior features. If your deck collapses because the wood has rotted over time, the claim will likely be denied. If your foundation cracks due to soil settling that you could have addressed with proper drainage, the claim may be denied. Even if the damage is partly covered, the insurer may apply a maintenance exclusion to reduce the payout. The key takeaway is that home insurance is not a maintenance contract. It covers sudden events, not the wear and tear that comes with homeownership.
To avoid these surprises, keep up with routine maintenance and document it. Save receipts for roof repairs, plumbing updates, and HVAC servicing. If you do file a claim, having a maintenance record can help you demonstrate that you took reasonable care of your home. It also helps to understand the difference between a covered peril and a maintenance issue. For example, if a storm causes a tree to fall on your roof, that is a covered peril (windstorm). But if the tree falls because it was dead and you neglected to remove it, the insurer might argue that neglect contributed to the loss.
Endorsements That Can Add Back Certain Exclusions
The good news is that many home insurance exclusions can be addressed with endorsements, which are add-ons that modify your policy to provide additional coverage. Endorsements typically increase your premium, but they can fill critical gaps and prevent unpleasant surprises. Here are some of the most common endorsements that homeowners buy to add back coverage:
- Flood insurance: Available through the NFIP or private insurers, this covers water damage from external flooding.
- Earthquake insurance: A separate policy or endorsement that covers damage from earthquakes and sometimes other earth movement.
- Sewer backup and sump pump overflow: Covers water damage from backed-up sewers or failed sump pumps, which is typically excluded.
- Ordinance or law coverage: Pays for the extra cost of rebuilding to current building codes.
- Water backup and sump discharge: Similar to sewer backup, this endorsement covers water that backs up through drains or sump pumps.
- Mold remediation: Some policies offer limited mold coverage, but you can often buy additional protection.
- Scheduled personal property: For high-value items like jewelry, art, or collectibles that are subject to sublimits, this endorsement provides broader coverage.
These endorsements are not one-size-fits-all. The right ones depend on your location, your home's age and condition, and your personal belongings. For example, if you live in an area prone to flooding, flood insurance is essential. If your home is older and not up to current codes, ordinance or law coverage can be valuable. If you have a home office or run a business from home, you may need a business pursuits endorsement or a separate commercial policy.
When considering endorsements, it is important to weigh the cost against the potential benefit. An endorsement that adds $200 per year to your premium might be well worth it if it covers a $10,000 sewer backup claim. On the other hand, if you live in a low-risk area for earthquakes, the extra premium might not be justified. The key is to understand your risk profile and make informed decisions. You can compare home insurance quotes and endorsements from multiple carriers to find the right balance of coverage and cost. For a broader look at comparing policies and finding competitive rates, you can use resources like QuoteComparison to evaluate options side by side.
How to Review Your Declarations Page for Gaps
The declarations page (or dec page) is the summary of your home insurance policy. It lists your coverage limits, deductibles, and any endorsements you have purchased. It also shows the policy form number, which you can use to look up the exact exclusions that apply. Reviewing your dec page is one of the most important steps you can take to avoid surprises. Here is a simple framework to follow:
- Check your dwelling coverage limit: Make sure it reflects the cost to rebuild your home, not its market value. If you have made improvements or if construction costs have risen, you may need to increase your limit.
- Review your personal property coverage: Understand the sublimits for categories like jewelry, electronics, and firearms. If your belongings exceed these limits, consider scheduling them separately.
- Look at your liability coverage: Ensure it is adequate for your assets. A common recommendation is at least $300,000, but some homeowners need more.
- Identify your deductibles: Check both your standard deductible and any separate deductibles for windstorm or hurricane damage. A higher deductible lowers your premium but increases your out-of-pocket cost after a loss.
- List your endorsements: Note which endorsements you have and which you might need. If you see exclusions that concern you, ask your agent about adding coverage.
After reviewing your dec page, take the next step: read your policy form. The dec page summarizes coverage, but the policy form contains the exclusions in detail. Pay attention to sections labeled "Exclusions" and "Conditions." Look for phrases like "we do not cover," "unless," and "subject to." If you find language you do not understand, ask your agent or a licensed insurance professional to explain it. It is better to ask questions now than to discover a gap after a loss.
Another helpful practice is to do an annual policy review. Your coverage needs change over time as your home appreciates, your belongings accumulate, and your family situation evolves. An annual review helps you keep your policy aligned with your needs and gives you a chance to adjust endorsements or limits. Many insurers offer online tools or mobile apps that make it easy to review your policy and request changes.
Real-World Examples of Surprising Exclusions
To illustrate how these exclusions play out in real life, consider a few scenarios that often surprise homeowners. In each case, the homeowner assumed they were covered, but the policy said otherwise.
Scenario 1: The slow leak. A homeowner notices a stain on the ceiling and ignores it for a few months. Eventually, the drywall collapses, causing significant damage. The insurer denies the claim because the damage resulted from long-term seepage and neglect, not a sudden event. The homeowner is stuck with the repair bill.
Scenario 2: The home business. A homeowner runs a consulting business from a home office and stores client files and expensive equipment there. A fire destroys the office. The insurer covers the dwelling damage but denies the claim for the business equipment and lost income because business property and business interruption are excluded under a standard homeowners policy.
Scenario 3: The earthquake. A homeowner lives in an area with moderate seismic risk but never buys earthquake insurance because "we never have earthquakes here." A small earthquake causes foundation cracks and chimney damage. The claim is denied because earth movement is excluded. The homeowner faces tens of thousands of dollars in repairs.
Scenario 4: The mold. A homeowner has a minor plumbing leak that is fixed, but moisture remains in the walls. Mold develops and spreads. The insurer denies the mold remediation claim because mold is excluded unless it results from a covered peril and the homeowner has purchased additional coverage. The homeowner pays out of pocket for remediation.
These examples highlight why it is so important to understand home insurance exclusions that surprise homeowners. They also show that the consequences of a gap can be financially devastating. The good news is that most gaps can be closed with endorsements, separate policies, or simple maintenance. The key is to be proactive.
Steps to Protect Yourself from Surprising Exclusions
Now that you know the common exclusions and how they can affect you, here are practical steps you can take to protect yourself:
- Read your policy and dec page annually. Set a reminder to review your coverage every year, ideally before renewal. Look for changes in exclusions or limits.
- Ask about endorsements. When you buy or renew your policy, ask your agent about endorsements that might fill gaps, such as flood, earthquake, sewer backup, and ordinance or law coverage.
- Maintain your home and keep records. Regular maintenance prevents claims and helps you demonstrate that you took reasonable care if a claim occurs. Save receipts and photos of repairs.
- Consider your risks. Evaluate your home's location and features. If you live in a flood zone, buy flood insurance. If you have a home business, get the right coverage. If you have high-value items, schedule them.
- Shop around and compare. Different insurers have different exclusions and endorsement options. Comparing quotes can help you find a policy that fits your needs and budget.
By taking these steps, you can avoid the unpleasant surprises that come with undiscovered exclusions. Remember, home insurance is not a set-it-and-forget-it product. It requires periodic review and adjustment to keep pace with your life and your home.
Final Thoughts
Home insurance exclusions that surprise homeowners are a common source of frustration and financial loss. From earth movement and neglect to mold and business property, standard policies exclude many perils that homeowners assume are covered. The key to protecting yourself is education and proactive review. Understand what your policy covers and what it does not, ask about endorsements that can close gaps, and review your declarations page regularly. If you are unsure about your coverage, consult a licensed insurance professional. Taking the time to understand your policy now can save you from a devastating surprise later.