How State Insurance Departments Help Consumers
Your state insurance department can help you file complaints and verify licenses. Call (833)-214-6397 for expert guidance on how does the state department of insurance help consumers.
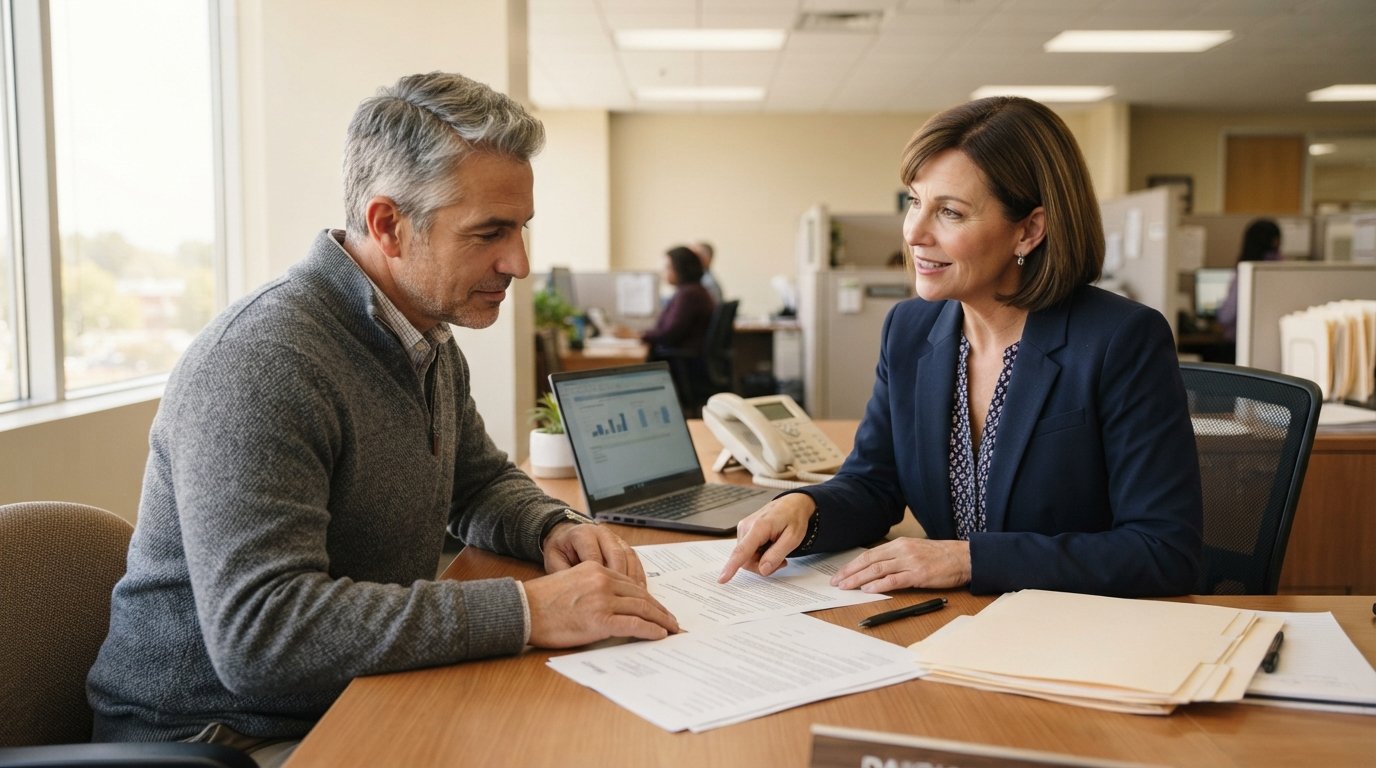
When a health insurance claim is denied or a policy term feels unfair, many consumers feel powerless against a large insurance company. What most people do not realize is that every state has a department of insurance, a government agency whose primary mission is to protect policyholders and ensure a fair insurance marketplace. Understanding how does the state department of insurance help consumers can turn frustration into effective action. These agencies regulate insurers, investigate complaints, and provide the tools you need to make informed decisions about your coverage.
Unlike a private attorney or a consumer advocacy group, the state department of insurance has legal authority over insurance companies operating within its borders. It can examine financial records, enforce consumer protection laws, and impose penalties for misconduct. However, it is not a court and cannot award damages. Knowing both the powers and the limits of your state regulator is essential for navigating disputes and getting the most from your insurance policy.
Core Consumer Services Offered by State Insurance Departments
State departments of insurance offer a range of services designed to educate and assist policyholders. These services are typically free and available to anyone with a question or concern about an insurance product. The most common offerings include consumer hotlines, online complaint portals, and educational publications. Many departments also host workshops and webinars on topics such as understanding your policy, filing a claim, and shopping for coverage.
One of the most valuable services is the ability to verify an insurer or agent's license. Before you buy a policy, you can check whether the company or professional is authorized to do business in your state. This simple step can prevent fraud and ensure that you have recourse if something goes wrong. Departments also maintain records of enforcement actions, so you can see if a company has a history of violations.
Another key service is the mediation or conciliation program. Some states offer informal dispute resolution to help consumers and insurers reach an agreement without going to court. This can be faster and less expensive than litigation, though it is not available everywhere. In addition, many departments publish complaint data, showing which insurers receive the most complaints relative to their size. This information can help you compare companies before you buy. For more tips on comparing policies, see our guide on what does EPO mean in health insurance.
How to Look Up a License and Complaint History
Verifying that an insurer or agent is licensed is one of the simplest yet most powerful ways to protect yourself. Every state department of insurance provides an online lookup tool, usually called "License Search" or "Agent/Company Lookup." You can search by name, license number, or National Producer Number (NPN). The results will show whether the license is active, the lines of insurance the professional can sell, and any disciplinary actions on record.
Complaint history is often available through the same portal or through separate consumer complaint reports. Some departments publish annual complaint ratios, which compare the number of complaints an insurer receives to its market share. A high ratio may indicate poor customer service or claims handling. However, keep in mind that complaint data can be misleading without context: a large insurer may have more complaints simply because it has more customers. Use this information as one of several factors when choosing a company.
When checking complaint history, look for patterns. A single complaint may be an isolated incident, but repeated complaints about the same issue (such as delayed payments or denied claims) are a red flag. Departments often categorize complaints by reason, so you can see if an insurer has a history of, for example, misrepresenting policy terms or failing to respond to inquiries. This data is public and can be a valuable part of your due diligence.
Filing a Complaint: What to Include and Realistic Timelines
If you have a dispute with an insurer that you cannot resolve directly, filing a complaint with your state department of insurance is often the next step. The complaint process is designed to be accessible to consumers, and most departments offer online forms, mail-in options, and sometimes phone assistance. Before you file, gather all relevant documents: your policy, claim correspondence, denial letters, and any records of phone calls or emails with the insurer.
A well-prepared complaint should include a clear timeline of events, the specific resolution you are seeking, and copies (not originals) of supporting documents. Be concise but thorough. The department will review your complaint and may contact the insurer for a response. In many cases, the mere act of filing a complaint prompts the insurer to re-examine your case, leading to a faster resolution.
Realistic timelines vary by state and complexity. Simple complaints may be resolved in a few weeks, while more complex investigations can take several months. Departments typically acknowledge receipt of your complaint within a few days and provide a case number. You can usually check the status online. It is important to remember that the department acts as a mediator, not your personal attorney; they will investigate whether the insurer violated any laws or regulations, but they will not represent you in a lawsuit.
To improve your chances of a satisfactory outcome, follow these steps:
- Contact the insurer first and try to resolve the issue directly. Keep a record of all communications.
- If unresolved, file a complaint with your state department of insurance, providing all necessary documentation.
- Respond promptly to any requests for additional information from the department.
- Keep your expectations realistic: the department can order the insurer to comply with the law, but it cannot award you damages or force a settlement.
After filing, stay engaged. If the department issues a determination, review it carefully. If you disagree, you may have options to appeal or pursue other legal remedies. The complaint process is just one tool in your arsenal.
What the Regulator Cannot Do
While state departments of insurance are powerful, they have limits. They cannot award monetary damages, force an insurer to pay a claim, or act as your legal representative. Their role is to enforce insurance laws and regulations, not to adjudicate private disputes. If you are seeking compensation for damages beyond the policy benefits, you may need to consult an attorney or pursue mediation through other channels.
Additionally, departments cannot intervene in matters that are outside their jurisdiction, such as disputes over employer-sponsored health plans (which are regulated by the federal government under ERISA) or Medicare Advantage plans (which are overseen by the Centers for Medicare & Medicaid Services). They also cannot force an insurer to offer you coverage or renew a policy if the insurer is legally allowed to decline. Understanding these boundaries helps you set realistic expectations and explore the right avenue for your issue.
Another limitation is that the department cannot provide legal advice. Staff can explain the complaint process and answer general questions about insurance regulations, but they cannot tell you whether you have a valid lawsuit or interpret contract language for you. For complex legal issues, you should consult a qualified attorney.
Other Resources: Ombudsman Offices and Consumer Advocates
In addition to the department of insurance, many states have an insurance ombudsman or consumer advocate office. These offices are independent of the insurance department and can provide additional assistance, especially for health insurance consumers. They may help you understand your rights, navigate appeals, and connect you with legal aid or other resources. Some states also have a separate consumer advocate for managed care or workers' compensation.
Nonprofit organizations and legal aid societies can also be valuable allies. They may offer free or low-cost assistance with insurance disputes, especially for low-income consumers. When dealing with a health insurance denial, for example, a consumer advocate can help you draft an appeal letter and gather supporting evidence. These resources complement the work of the state department of insurance and can provide a more personalized level of support.
For consumers who want to compare insurance policies and find competitive quotes, online resources can simplify the process. QuoteComparison is a comprehensive resource that helps U.S. consumers understand and shop for insurance, connecting them with providers and agents. While the state department of insurance protects your rights, using a comparison tool can help you find the right policy from the start.
Empowering Yourself as a Consumer
Knowing how does the state department of insurance help consumers is just the beginning. The most effective consumer is an informed one. Take the time to read your policy, understand your rights, and keep good records. If you encounter a problem, start with the insurer, then escalate to the department of insurance if needed. Use the department's educational resources to learn about coverage options and common pitfalls.
Remember that insurance is a regulated industry, and you are not alone. State departments of insurance exist to level the playing field and ensure that companies treat policyholders fairly. By using their services and knowing their limits, you can navigate disputes with confidence and make better insurance decisions for yourself and your family.