How to Compare Homeowners Insurance Quotes Line by Line
Compare homeowners insurance quotes line by line and avoid surprise claim gaps. Call (833)-214-6397 for guidance on matching coverage before you commit.
By Tamsin Rowe
Your inbox has three homeowners insurance quotes, and the premiums look nothing alike. One is $400 cheaper per year, another promises "full replacement," and a third throws in a water backup endorsement you have never heard of. Choosing on price alone is how homeowners end up with a claim denied or a settlement that covers half their roof. The only reliable way to shop is to compare homeowners insurance quotes line by line, matching coverage limits, deductibles, exclusions, and endorsements side by side until the differences are impossible to miss.
This guide gives you a repeatable method: a worksheet approach, the exact line items that matter, the questions to ask licensed agents, and the red flags hiding inside suspiciously cheap quotes. By the end, you will be able to read any homeowners quote like an underwriter and know precisely what you are paying for.
Set Up a Quote Comparison Worksheet Before You Read Anything
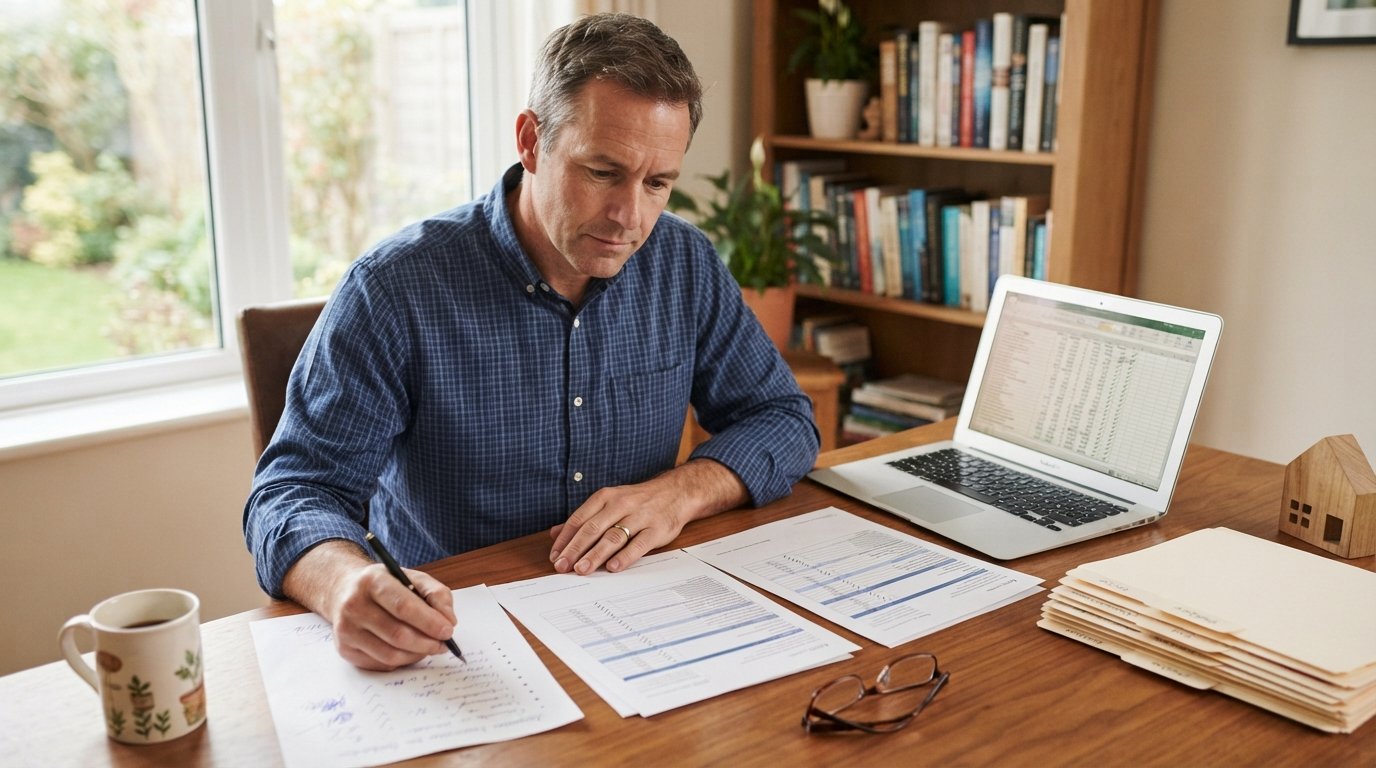
Line by line comparison fails when you read quotes one at a time. Human memory is generous to whichever quote you read last. Instead, build a simple worksheet, either a spreadsheet or a printed table, with one column per insurer and one row per coverage line. Every quote gets entered into the same structure, which forces an apples to apples comparison.
Before you request quotes, standardize the inputs. All insurers should quote the same dwelling characteristics, the same deductible, the same personal property limits, and the same liability amount. If one quote uses a $5,000 deductible and another uses $1,000, the premiums are not comparable, and the line by line review will mislead you. Note your target values at the top of the worksheet: dwelling replacement cost, deductible, liability limit, and any endorsements you want, such as water backup or scheduled jewelry coverage.
Then request quotes from at least three insurers, including a couple of regional carriers, since pricing and underwriting appetites vary widely by state and construction type. If you want a shortcut for gathering multiple offers, QuoteComparison lets you request and organize quotes from participating providers in one place. When the quotes arrive, resist the urge to rank them by premium. Enter each one into the worksheet first, line by line, and let the structure reveal the real differences.
Match Dwelling Coverage and Deductibles Across Every Quote
Dwelling coverage, often labeled Coverage A, is the line that pays to rebuild your home's structure after a covered loss. It is also the line most likely to differ dramatically between quotes, because each insurer runs its own replacement cost estimator. One carrier might estimate your rebuild at $320,000 while another estimates $395,000 for the same house. A lower Coverage A number is not automatically better; it may simply mean the insurer is insuring you for less than it would cost to rebuild, which can trigger penalties at claim time.
Compare the Coverage A figures against each other and against your own sense of rebuild cost. Ask each agent what replacement cost estimator they used and whether the estimate includes debris removal, permits, and upgraded building codes. Those items are frequently excluded unless added, and they can add 10 to 20 percent to a real rebuild. If one quote's dwelling limit is far below the others, treat that as a warning, not a bargain.
Deductibles require the same discipline. Every quote should be re-run at the same deductible before you compare premiums. A $2,500 deductible can cut a premium by hundreds of dollars, but only if you could actually write that check after a storm. Enter the deductible in its own row and confirm whether it applies separately to wind or hail claims, which is common in coastal and hail prone states. A quote with a $1,000 standard deductible but a 2 percent wind deductible is not the same product as one with a flat $1,000 deductible across all perils.
Compare Endorsements, Exclusions, and Wind or Hail Deductibles
Two quotes with identical Coverage A, deductible, and liability limits can still be very different policies. The difference lives in endorsements and exclusions, the fine print that adds or removes protection. This is where line by line comparison earns its keep, because the cheapest quote is often cheap precisely because it excludes something you assumed was covered.
Common endorsements to check for on each quote include:
- Water backup and sump overflow coverage, which pays for sewer or drain backup damage that standard policies exclude
- Scheduled personal property for jewelry, art, or collectibles that exceed sublimits
- Replacement cost on personal property instead of actual cash value
- Ordinance or law coverage for code upgrades during a rebuild
- Extended replacement cost, which pays a percentage above the dwelling limit if rebuild costs spike
Then read the exclusions list on each quote. Look specifically for cosmetic damage exclusions, wear and tear language, mold limitations, and whether the policy covers or excludes damage from backed up drains. In hurricane and hail states, confirm how the wind or hail deductible is structured: a flat dollar amount or a percentage of the dwelling limit. A 2 percent wind deductible on a $350,000 home means $7,000 out of pocket before coverage begins, a detail that never appears in the headline premium.
Replacement cost estimates also vary between insurers in ways that affect these endorsements. One carrier may build the dwelling limit using a conservative estimator, then sell extended replacement cost as a buffer. Another may build in a more generous limit but exclude code upgrades. Neither approach is wrong, but they are not equivalent, and the line by line worksheet is the only place that difference becomes visible. For a deeper look at how regional factors influence pricing, see this guide to homeowners insurance cost in Arkansas, which illustrates how location and construction type shift both premiums and coverage assumptions.
Check Liability Limits, Loss of Use, and Medical Payments
Premium focused shoppers often skip the liability section, which is a mistake. Liability coverage pays for injuries or property damage you cause to others, and it is the line that protects your savings and future income. Standard quotes often default to $100,000 or $300,000, but many agents recommend $300,000 to $500,000 or an umbrella policy on top. Enter the liability limit for each quote in its own row and confirm whether the number is per occurrence or aggregate.
Loss of use coverage, sometimes called Coverage D, pays for temporary housing and added living expenses if your home becomes uninhabitable. Insurers express this differently: a dollar amount, a percentage of Coverage A, or a time limit such as 12 or 24 months. A quote showing "up to 20 percent of Coverage A" with no time limit is generally stronger than a flat $30,000 with a 12 month cap, especially in markets where rebuilding takes longer. Medical payments coverage, usually $1,000 to $5,000, is minor in premium but worth confirming, since it pays guests' medical bills regardless of fault.
These lines rarely drive the premium difference between quotes, but they drive the quality of the policy. A line by line review that stops at dwelling coverage and deductible misses the sections that determine how well you are protected after a serious event.
Ask Licensed Agents These Questions Before You Commit
Quotes are marketing documents, and agents are salespeople, but a good licensed agent will welcome specific questions. Asking the same questions of every agent keeps the comparison fair and surfaces details that never make it onto the quote PDF. Write the answers directly into your worksheet next to the relevant line.
Questions worth asking every agent include:
- Which replacement cost estimator did you use, and does the dwelling limit include debris removal, permits, and code upgrades?
- Is the wind or hail deductible a flat dollar amount or a percentage of the dwelling limit, and does it apply per storm or per season?
- Which endorsements are included versus optional, and what would each optional endorsement add to the premium?
- How does the insurer handle claims: local adjusters, preferred contractors, or a centralized claims center?
- Are there any surcharges, fees, or membership charges not shown in the quoted premium?
Pay attention to how agents answer. An agent who cannot explain the wind deductible or who brushes off questions about exclusions is telling you something about the service you will get at claim time. A strong agent will walk you through the quote line by line, flag the trade-offs, and tell you when a cheaper policy is a bad idea for your situation.
Spot Red Flags in Suspiciously Cheap Quotes
A quote that is dramatically cheaper than every other offer deserves scrutiny, not celebration. Sometimes it reflects a genuinely competitive carrier with a narrow appetite for your home type. More often, the savings come from reduced coverage, a higher deductible disguised in the fine print, or a coverage gap you will discover only when you file a claim.
Watch for these red flags during your line by line review:
- Dwelling coverage far below other quotes, suggesting an unrealistically low rebuild estimate
- Actual cash value instead of replacement cost on the roof or personal property, which pays depreciated value
- A percentage wind or hail deductible buried in the declarations page rather than explained upfront
- Exclusions for cosmetic damage, mold, or water backup that other quotes include
- Missing loss of use coverage or unusually low liability limits
- An insurer with a thin claims reputation or no local adjusters in your area
None of these flags automatically disqualifies a quote, but each one must be priced. If the cheap quote saves $300 per year but carries a 2 percent wind deductible and actual cash value on the roof, the savings can vanish in a single claim. The right move is to ask the agent to re-quote with comparable coverage, then compare again. A fair comparison means every quote protects you at roughly the same level, and the premium difference reflects the insurer's efficiency, not the coverage you gave up.
Comparing homeowners insurance quotes line by line takes an afternoon, but it changes the outcome of every future claim. Standardize your inputs, build a worksheet, match dwelling coverage and deductibles, read the endorsements and exclusions, and question anything that looks too cheap. When you are ready to gather offers from multiple providers and put this method to work, start with a quote request through InsuranceShopping.com and review each offer with the same worksheet in hand.