How to Read the Declarations Page of an Insurance Policy
Decode your policy summary with confidence. Call (833)-214-6397 for guidance on reading your declarations page and spotting coverage gaps early.
By Silas Corwin
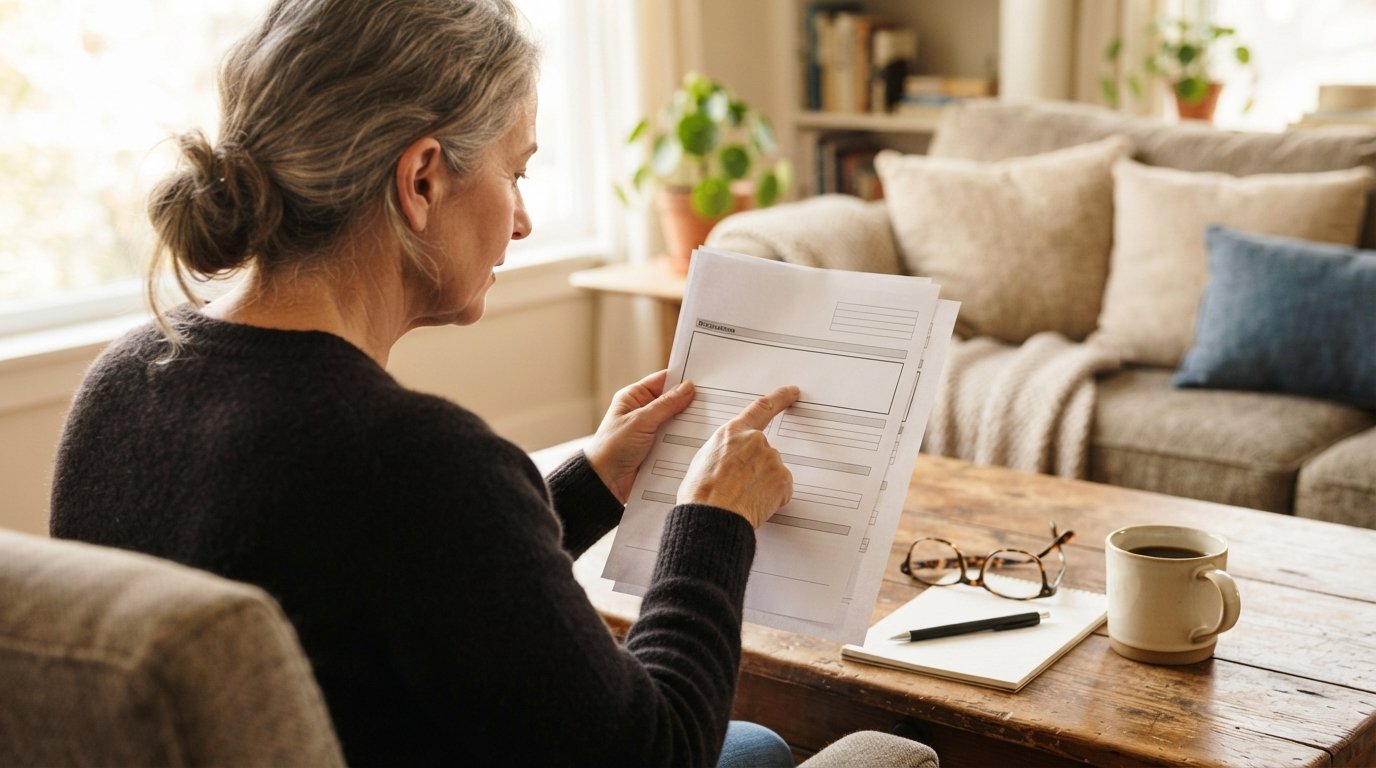
Your insurance policy arrives as a thick stack of papers, and the most important page is often the one you skim past. The declarations page, sometimes called the dec page, is the snapshot of your entire policy: who is covered, what is covered, how much is covered, and what you pay. Learning how to read the declarations page of an insurance policy takes about ten minutes, but it can save you thousands of dollars at claim time and reveal costly errors before they become problems. This guide walks through each section, explains how the dec page relates to the full policy form, and shows you what to check after every renewal.
InsuranceShopping.com is an informational and connection service, not an insurer. The explanations below are educational, and your actual policy language always controls. If anything on your declarations page looks wrong, contact your agent or carrier promptly. You can also compare coverage options and request no-obligation quotes through our site to make sure your policy still fits your needs.
What the Declarations Page Is and Why It Matters
The declarations page is the cover summary of your insurance contract. It lists the named insured, the policy period, the covered property or vehicles, the coverage limits, the deductibles, the premium, and any endorsements that modify the standard policy. Insurers generate a new dec page at every renewal and after any mid-term change, so the document doubles as a receipt and a change log. If you ever need to prove coverage, the dec page is the first document anyone asks for.
The dec page does not contain the full legal terms. Those live in the policy form, sometimes called the jacket or the base form. The declarations page personalizes the generic form to your situation. Think of the policy form as the rulebook and the dec page as the scorecard for your specific game. When the two conflict, the declarations page usually controls specific items like limits and deductibles, while the form controls definitions and exclusions. Reading them together is the only way to understand your actual coverage.
Many policyholders never look at the dec page after the initial purchase. That is a mistake. Premiums change, limits get adjusted, and endorsements appear or disappear. A quiet change on page one can mean a very loud surprise at claim time. The sections below break the page into manageable parts so you can review it with confidence.
Finding the Key Numbers: Limits, Deductibles, and Premiums
The middle of the declarations page is usually a table of coverages. Each row names a coverage, shows a limit, and often shows a deductible. For auto insurance, you might see bodily injury liability, property damage liability, collision, comprehensive, uninsured motorist, and medical payments. For homeowners insurance, you might see dwelling, other structures, personal property, loss of use, personal liability, and medical payments to others. Health insurance dec pages typically show the plan name, deductible, out-of-pocket maximum, copays, and coinsurance percentages.
Limits are the maximum the insurer will pay for a covered loss. A limit can be a single number, a pair of numbers, or a schedule. For example, auto liability might read 100/300/50, meaning $100,000 per person, $300,000 per accident, and $50,000 for property damage. Homeowners dwelling coverage might read $350,000. Health plans might show an individual deductible of $2,500 and a family deductible of $5,000. Deductibles are what you pay out of pocket before the insurer pays its share. A higher deductible usually lowers your premium, but it also raises your exposure at claim time.
Premiums are itemized on most dec pages. You can see the base premium, any discounts, fees, taxes, and the total. This breakdown is useful when you shop around, because a competitor's lower total might actually reflect fewer coverages rather than a better price. Comparing line by line prevents apples-to-oranges quotes. If a line item looks unfamiliar, ask your agent before you pay. Unfamiliar fees and surcharges are common sources of billing disputes.
Here are the specific items to locate and verify on the coverage table:
- Named insured and additional insureds: Confirm every person or entity that should be covered is listed exactly as intended.
- Policy period: Note the effective and expiration dates, especially for short-term or non-ACA health coverage.
- Coverage limits: Check that each limit meets your state minimums and your personal risk tolerance.
- Deductibles: Confirm the dollar amounts and whether separate deductibles apply to different perils.
- Premium breakdown: Review discounts, fees, and the total amount due, and confirm the payment schedule.
Once you have located these items, read the endorsements section. Endorsements are amendments that add, remove, or change coverage. A common example is a scheduled personal property endorsement that lists a specific engagement ring or camera. Another is a water backup endorsement that adds coverage the base policy excludes. Endorsements often carry their own limits and deductibles, so they deserve a separate look. If an endorsement appears that you did not request, ask why. If one is missing that you expected, ask for it in writing.
How the Declarations Page Relates to the Full Policy Form
The declarations page is not the whole contract. It is the summary that makes the contract specific to you. The full policy form contains definitions, coverage grants, exclusions, conditions, and duties after loss. Reading only the dec page can give you a false sense of security, because exclusions in the form can wipe out coverage that the dec page appears to provide. For example, a homeowners dec page might show $300,000 in personal property coverage, but the form might exclude business property or limit jewelry theft to $1,500. The dec page shows the limit; the form shows the fine print.
The best practice is to read the dec page first, then scan the form for definitions and exclusions that affect your situation. Pay special attention to defined terms like actual cash value, replacement cost, occurrence, and resident relative. These definitions determine how much you actually collect. If your dec page shows replacement cost coverage, confirm that the form defines it the way you expect. If it shows actual cash value, understand that depreciation will reduce your payout.
Health insurance works the same way. The summary of benefits and coverage, which functions like a dec page, shows deductibles and copays, but the plan document contains the network rules, prior authorization requirements, and exclusions. A low deductible on the summary can be misleading if the service you need requires prior authorization or falls outside the network. Reading both documents together is the only way to see the full picture. Our guide on how to choose the best supplemental health insurance policy explains how supplemental coverage can fill gaps that the main policy leaves behind.
Common Errors to Check for After a Renewal
Renewal is when most dec page errors appear. Insurers update the page automatically, and small changes can slip through unnoticed. A deductible might increase, a discount might drop off, or a vehicle might be listed with the wrong annual mileage. These errors are usually fixable, but only if you catch them before a claim. Set a calendar reminder to review your dec page within a few days of receiving it.
Start with the named insured and address. A misspelled name or an old address can cause problems at claim time, especially for homeowners policies where the property address must match. Next, verify the policy period and the premium. Compare the new premium to last year's and identify what changed. A premium increase is not automatically an error, but an unexplained increase deserves a call. Then check the coverage limits against your current needs. If you renovated your home or bought a new car, the old limits may no longer be adequate.
Review the endorsements and exclusions carefully. Renewal is a common time for insurers to add restrictive endorsements or remove optional coverages. If an endorsement appears that you did not request, ask for an explanation. If a coverage you relied on has disappeared, ask whether it was removed intentionally and what it would cost to add it back. Document every conversation with dates and names. If the insurer made an error, ask for a corrected dec page in writing.
Here is a practical renewal checklist you can run through in minutes:
- Confirm the named insured, address, and policy period are correct.
- Compare each coverage limit and deductible to the prior year's dec page.
- Verify that all discounts and credits you qualify for are still applied.
- Review every endorsement and confirm you requested each one.
- Check that the premium breakdown matches the amount you were quoted.
If you find a discrepancy, contact your agent or carrier immediately. Most errors are correctable, but some have deadlines. For example, if a vehicle was omitted from a policy, coverage might not apply to a loss that occurred before the correction. Acting quickly protects you. Keep a copy of the corrected dec page with your policy documents.
Why a New Declarations Page Signals a Coverage Change
Insurers issue a new declarations page whenever something material changes. That includes renewals, mid-term endorsements, vehicle additions or removals, address changes, and coverage limit adjustments. A new dec page is effectively a notice that your contract has been modified. Ignoring it means you may not know what you agreed to. Treat every new dec page as a required read, not junk mail.
The change might be minor, such as a new paperless billing fee. It might be significant, such as a reduced dwelling limit after a roof inspection or a new exclusion for water damage. In health insurance, a new dec page or summary of benefits can signal a formulary change, a network change, or a new prior authorization requirement. These changes affect what you pay and where you can receive care. Reading the new page promptly gives you time to switch plans during open enrollment or to request an exception if a needed service is affected.
If you receive a new dec page you did not expect, call your agent. Unrequested changes can be legitimate (for example, an insurer re-rating a policy after an inspection) or they can be errors. Either way, you have the right to ask questions and to receive a clear explanation. If the change is not acceptable, you can often adjust coverage, shop for a new policy, or cancel within the allowed window. Understanding your options before the next payment is due puts you in control.
For consumers who want to compare policies side by side, a resource like QuoteComparison can help organize quotes across carriers. The key is to compare dec pages, not just premiums, because the cheapest quote often reflects the thinnest coverage. Line up the limits, deductibles, and endorsements next to each other and the real differences become obvious.
Putting It All Together: A Practical Reading Routine
Reading a declarations page becomes easy with a consistent routine. First, confirm the basics: names, addresses, dates, and premium. Second, review the coverage table line by line and compare it to your needs and to last year's page. Third, read the endorsements and note anything unfamiliar. Fourth, scan the policy form for definitions and exclusions that affect the coverages you rely on most. Finally, file the dec page where you can find it and note the next renewal date.
This routine takes less time than a coffee break, and it turns a confusing document into a useful tool. You will spot errors earlier, understand your coverage better, and negotiate from a position of knowledge. Whether you are reviewing auto, home, health, life, or Medicare coverage, the declarations page is the fastest way to see what you actually bought. If you are unsure about a coverage gap, ask a licensed agent to walk through the page with you. A few minutes of review today can prevent a denied claim tomorrow.