How to Update Insurance After Having a Baby
Update insurance after a baby without stress. Call 8332146397 for expert guidance on adding your newborn and avoiding surprise bills.
By Silas Corwin
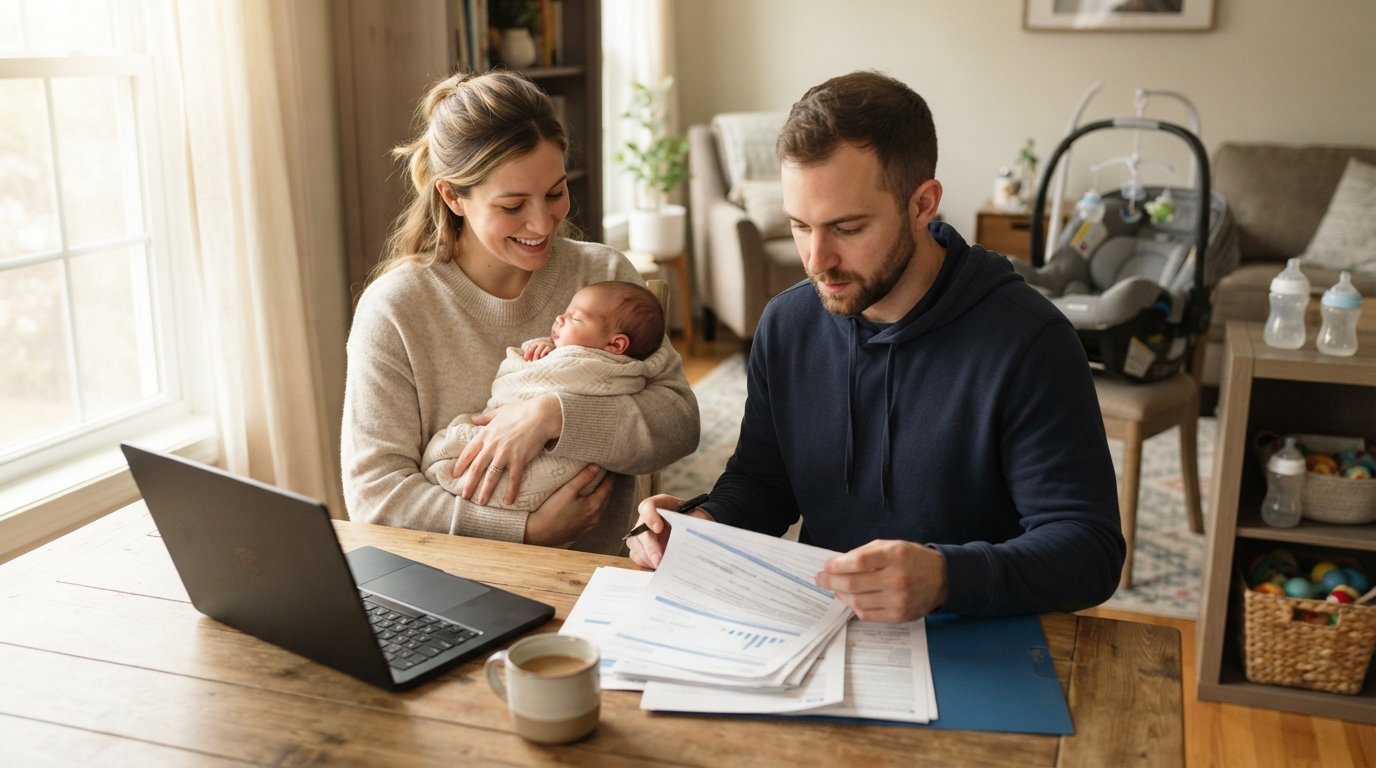
The moment you welcome a newborn into your family, your world shifts in profound ways. Between feedings, diaper changes, and sleepless nights, insurance paperwork probably ranks low on your priority list. Yet the decisions you make about health coverage in those first few months can shape your family's financial protection for years. Adding your baby to a health plan, understanding special enrollment windows, and updating related policies like auto and life insurance are time-sensitive tasks that deserve prompt attention. Acting quickly protects your newborn and may help you avoid surprise medical bills from pediatric visits, emergency care, or hospital stays.
Why Adding Your Newborn to Insurance Cannot Wait
Most health insurance policies include a limited window to add a new dependent after birth. This window is typically 30 to 60 days, though some plans allow up to 90 days. If you miss this deadline, you may have to wait until the next open enrollment period, which could leave your baby uninsured for months. During that gap, any medical care your newborn needs, including routine checkups, vaccinations, or emergency treatment, would come out of your pocket.
The good news is that the birth of a child qualifies as a qualifying life event. This designation triggers a special enrollment period that lets you add your baby to a health plan outside the annual open enrollment window. The same event may also allow you to change plans, switch from individual coverage to a family plan, or enroll in a marketplace plan if you were previously uninsured. Understanding these rules helps you move quickly and confidently.
If you are navigating other coverage questions, such as penalties for going without insurance, our guide on whether you get fined for no health insurance explains the current landscape. While the federal individual mandate penalty was reduced to zero starting in 2019, some states still impose their own penalties, making it important to maintain continuous coverage for your growing family.
Step-by-Step: How to Update Insurance After Having a Baby
Updating your insurance after a birth involves several moving parts, from notifying your employer to contacting your health plan and reviewing other policies. The following steps outline a practical sequence you can follow to ensure nothing falls through the cracks.
- Notify your employer or HR department. If you have job-based health insurance, your HR team is your first point of contact. They will provide the dependent enrollment form and explain the deadline for adding your newborn. Some employers require documentation, such as a birth certificate or proof of birth letter from the hospital.
- Contact your health insurance company directly. If you purchased coverage through the ACA Marketplace or directly from an insurer, call the member services number on your card. Ask about the dependent addition process, required documents, and the effective date of coverage. In many cases, coverage for the newborn is retroactive to the date of birth.
- Gather the necessary documents. You will typically need your baby's Social Security number, birth certificate, and possibly a hospital discharge summary. If you have not received the Social Security card yet, some insurers allow you to add the baby provisionally and submit the number later.
- Complete the enrollment forms. Whether online, by phone, or through paper forms, complete the dependent addition request within the special enrollment window. Keep copies of everything you submit and note the date.
- Confirm the update. After submitting your request, follow up with the insurer to confirm that your baby is officially enrolled. Ask for a new insurance card listing your dependent and verify the effective date.
Once your baby is added, review your plan's coverage details. Pediatric care, immunizations, and well-child visits are typically covered as preventive services with no cost-sharing under ACA-compliant plans. However, you should confirm which hospitals, pediatricians, and specialists are in your network to avoid unexpected out-of-network charges. If your current plan does not include your preferred pediatrician, the special enrollment period may allow you to switch to a different plan that does.
Special Enrollment Periods and Marketplace Coverage
If you have health insurance through the ACA Marketplace, the birth of a child triggers a 60-day special enrollment period. During this time, you can add your baby to your existing plan or choose a new plan that better fits your family's needs. You may also qualify for increased premium tax credits because your household size has grown, which could lower your monthly premiums.
To take advantage of this window, log into your Marketplace account or call the Marketplace call center. Report the birth as a life change, update your household income and size, and select a plan. If you miss the 60-day window, you generally cannot enroll until the next open enrollment period, unless you qualify for another special enrollment event.
For those who are self-employed or without employer-sponsored coverage, exploring private health insurance options may also be worthwhile. Private plans can offer flexibility, but they may not include the same consumer protections as ACA-compliant plans, such as guaranteed coverage for pre-existing conditions. Weigh the trade-offs carefully and consider speaking with a licensed insurance agent who can help you compare options.
Updating Other Insurance Policies After a Birth
Health insurance is the most urgent update, but other policies may also need attention. Adding a dependent can affect your auto insurance, life insurance, and even your homeowner or renter policy. Reviewing these coverages ensures your family is fully protected as it grows.
For auto insurance, adding a teen driver is not yet a concern, but you may want to review your policy to ensure it adequately covers your growing family. Some insurers offer discounts for bundling auto and home policies, which could free up funds for other needs. If you are comparing auto coverage, resources like NewAutoInsurance consumer guides can help you understand coverage options and potential savings.
Life insurance deserves special attention after a birth. If you already have a policy, consider whether the death benefit is sufficient to support your child through adulthood. If you do not have life insurance, this is an ideal time to purchase term coverage, which is often affordable for young parents. A licensed agent can help you determine the right coverage amount based on your income, debts, and future expenses like college tuition.
Common Mistakes to Avoid When Updating Insurance
Even well-intentioned parents can stumble when updating coverage. Being aware of common pitfalls helps you avoid costly gaps or delays.
- Missing the enrollment deadline. The 30-to-60-day window is strict. Set a reminder as soon as you get home from the hospital.
- Assuming coverage is automatic. In most cases, you must actively add your newborn. Do not assume the hospital notified your insurer.
- Forgetting to update income information. If you receive premium tax credits, reporting your new household size and any income changes ensures you receive the correct subsidy.
- Overlooking other policies. Health insurance is critical, but life and auto coverage may also need updates.
- Not confirming enrollment. Always follow up to verify your baby is covered and request a new insurance card.
Another frequent mistake is failing to review the plan's provider network. A plan that worked well for you and your partner may not include the pediatrician or children's hospital you prefer. During the special enrollment period, you have the flexibility to switch plans if needed, so take advantage of that option.
How InsuranceShopping.com Can Help
Navigating insurance changes after a birth can feel overwhelming, especially when you are sleep-deprived and adjusting to a new routine. InsuranceShopping.com is an informational resource that connects you with licensed insurance agents who can answer your questions and help you compare plans. Whether you need to update your health coverage, explore life insurance options, or review your auto policy, the site offers educational guides and no-obligation quote requests.
InsuranceShopping.com is not an insurer, agency, or broker. It does not issue, bind, or guarantee policies or rates. Instead, it serves as a connection service, matching consumers with participating providers. This model allows you to research options at your own pace and then speak with a licensed professional when you are ready. The site may receive compensation from featured providers, but that does not affect the information presented.
For new parents, the site's health insurance section includes articles on special enrollment, family coverage, and cost-saving strategies. You can also find guidance on life insurance and auto insurance, making it a convenient starting point for all your post-birth insurance needs.
Key Takeaways for New Parents
Updating insurance after having a baby is a task that requires prompt action and attention to detail. By understanding the special enrollment period, contacting your insurer or employer quickly, and reviewing all relevant policies, you can secure your child's coverage and protect your family's financial future.
Remember these core points:
- Add your newborn to health insurance within 30 to 60 days of birth.
- Use the special enrollment period to make changes outside open enrollment.
- Gather documents like Social Security number and birth certificate.
- Review life, auto, and home insurance to ensure adequate protection.
- Confirm enrollment and keep copies of all paperwork.
Taking these steps early gives you peace of mind and allows you to focus on what matters most: bonding with your new baby. If you have questions or need help comparing plans, reach out to a licensed insurance agent through InsuranceShopping.com. They can guide you through the process and help you find coverage that fits your family's needs and budget.