No Fault vs At Fault Car Insurance States: Key Differences
Understand how no fault versus at fault car insurance states explained affects your claim. Call (833)-214-6397 for expert guidance on your coverage options.
By Ophelia Crane
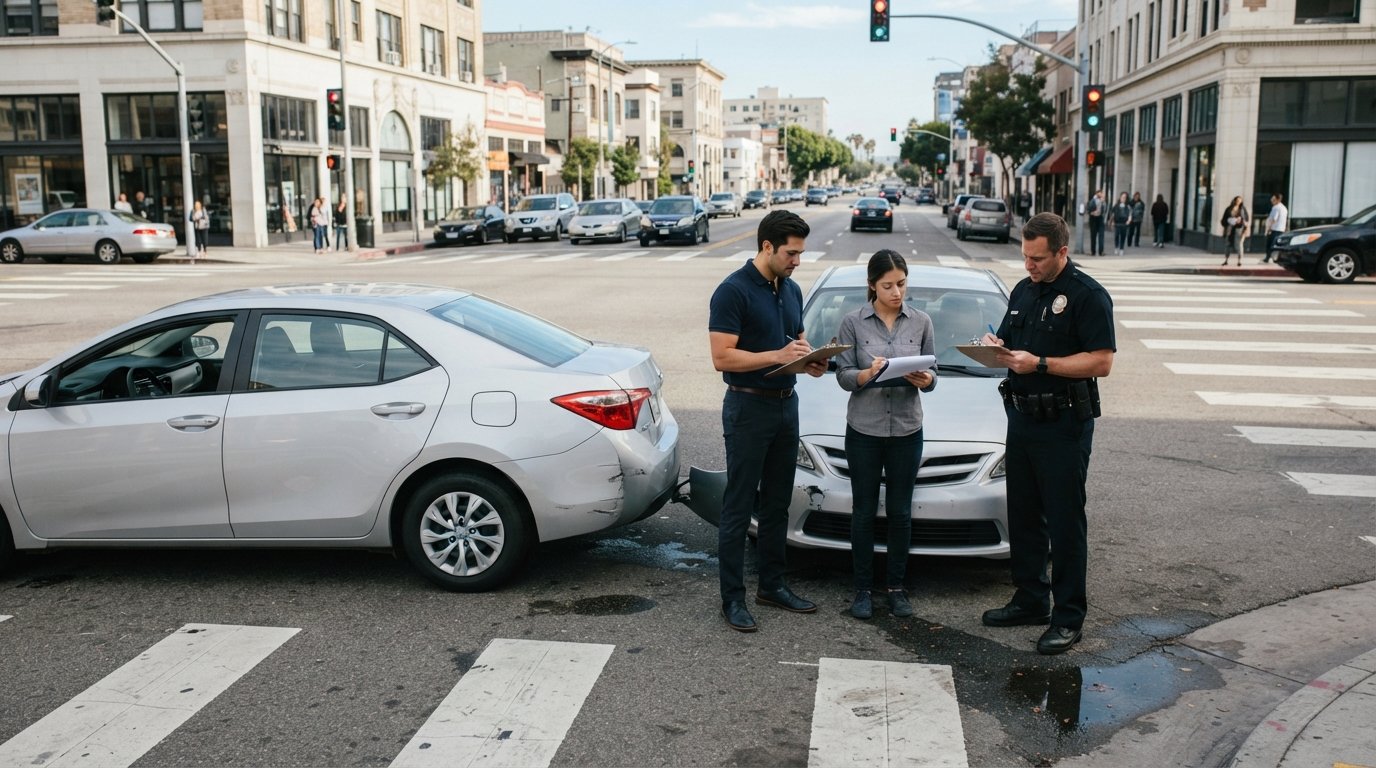
Imagine two drivers in identical fender benders on the same day. One lives in a state where each driver's own insurer pays medical bills immediately, regardless of who caused the crash. The other lives in a state where the driver who caused the accident (or that driver's insurer) is financially responsible for the other party's injuries and damage. Same accident, dramatically different financial and legal aftermath. That is the practical reality of no fault versus at fault car insurance states, and understanding which system applies where you live can save you thousands of dollars and months of frustration after a collision.
This guide breaks down how each system works, which states use which rules, how personal injury protection (PIP) fits into the picture, and what all of it means when you file a claim or consider suing another driver. Whether you are shopping for a new policy, moving to another state, or simply trying to make sense of a recent accident, the information below will help you navigate the claims process with confidence.
How No Fault Insurance Works After a Crash
In a no fault state, your own auto insurance policy pays for your medical expenses and certain other losses after an accident, no matter who caused the collision. This system is designed to speed up payments and reduce litigation. Instead of spending weeks or months determining fault, insurers process claims based on the coverage you purchased, typically personal injury protection (PIP) or medical payments coverage (MedPay).
The tradeoff is that your ability to sue the other driver is limited. In most no fault states, you can only file a lawsuit if your injuries meet a certain threshold, such as significant disfigurement, permanent injury, or medical expenses exceeding a specified dollar amount. These thresholds vary widely from state to state. Some states use a verbal threshold (describing the type of injury required), while others use a monetary threshold (a specific dollar figure).
A key point for drivers in no fault states is that PIP coverage is often mandatory. It typically covers medical bills, lost wages, and sometimes essential services like housekeeping or childcare, up to your policy limits. Because PIP pays first, your health insurance may not be involved until PIP benefits are exhausted. This is one reason it pays to understand your policy's PIP limits before an accident happens, not after.
How At Fault (Tort) States Handle Claims
In at fault states, also called tort states, the driver who is found responsible for the accident is financially liable for the other party's injuries and property damage. After a crash, you file a claim with the at fault driver's insurance company. That insurer investigates the accident, determines fault (often based on police reports, witness statements, and traffic laws), and pays damages up to the at fault driver's policy limits.
If the at fault driver has insufficient coverage or no insurance at all, you may need to rely on your own uninsured or underinsured motorist coverage. In some cases, you might also have the option to file a lawsuit directly against the at fault driver. The at fault system generally allows for broader recovery, including pain and suffering and other non economic damages, but it can also take longer to resolve because fault must be established.
It is worth noting that even in at fault states, your own insurer may pay for your medical bills under MedPay or PIP if you purchased those coverages. However, unlike in no fault states, these coverages are usually optional and do not restrict your right to sue. The at fault driver's liability insurance remains the primary source of compensation for your injuries and vehicle damage.
Which States Use No Fault or At Fault Rules
As of 2026, the majority of U.S. states use an at fault (tort) system for auto insurance. However, a significant number of states have some form of no fault law, and the details can be complex. Below is a general overview of no fault states, but keep in mind that laws can change and some states have hybrid systems or allow drivers to choose between no fault and at fault coverage.
- Traditional no fault states: Florida, Hawaii, Kansas, Massachusetts, Michigan, Minnesota, New York, North Dakota, Pennsylvania (choice no fault), and Utah.
- Add on or choice no fault states: Kentucky, New Jersey, and Pennsylvania allow drivers to select between no fault and at fault coverage, though the default may vary.
- At fault states: All other states, including California, Texas, Illinois, Georgia, and Ohio, operate under a tort liability system.
This list is not exhaustive and some states have unique rules. For example, Michigan has historically had unlimited PIP coverage, though recent reforms have introduced limits. Florida requires PIP but also has a verbal threshold for lawsuits. Because state laws evolve, always verify the current rules with your state's department of insurance or a licensed agent before making coverage decisions.
If you are moving to a new state, your existing policy may not automatically comply with the new state's requirements. It is wise to review your coverage and compare quotes from multiple insurers to ensure you meet the minimum requirements and have the protection you need. For those exploring coverage options, resources like affordable health insurance in North Carolina can provide helpful context on how health coverage interacts with auto insurance, especially in states where PIP is not available.
The Role of Personal Injury Protection (PIP) in No Fault States
Personal injury protection, or PIP, is the cornerstone of no fault insurance. It pays for medical expenses, lost wages, and other specified losses for you and your passengers, regardless of who caused the accident. PIP coverage is typically required in no fault states, and the minimum limits vary. In some states, you can purchase additional PIP coverage for higher limits.
PIP differs from medical payments coverage (MedPay), which is optional in many states and only covers medical expenses. PIP is broader because it can also reimburse you for lost income and essential services. However, PIP benefits are subject to policy limits and may have deductibles or co-pays. It is important to understand your PIP coverage before an accident so you know what to expect.
In no fault states, your PIP coverage pays first for your medical bills, even if you have health insurance. This is known as primary coverage. Once PIP is exhausted, your health insurance may kick in. If you do not have health insurance, PIP may be your only source of payment for medical bills, which makes adequate PIP limits especially important. In at fault states, PIP is not typically available, and your health insurance or the at fault driver's liability insurance would be the primary sources of payment.
Filing a Claim: What to Expect in Each System
The claims process differs significantly between no fault and at fault states. In a no fault state, you file a claim with your own insurance company for your medical expenses and other PIP benefits. You generally do not need to prove fault to receive these benefits. However, if you want to pursue a lawsuit for pain and suffering or other non economic damages, you must meet your state's threshold for serious injury.
In an at fault state, you file a claim with the at fault driver's insurance company. That insurer will investigate and determine fault. If they accept liability, they will pay for your damages up to the policy limits. If fault is disputed or the insurer delays, you may need to negotiate or consider legal action. Your own insurer may also be involved if you have collision coverage for vehicle damage or MedPay for medical bills.
Here is a simple framework for what to do after an accident, regardless of your state's system:
- Ensure everyone is safe and call 911 if needed.
- Exchange information with the other driver(s), including insurance details.
- Document the scene with photos and gather witness contact information.
- Report the accident to your insurance company promptly.
- Follow your state's specific rules for claims and lawsuits, including any deadlines.
Following these steps can help protect your rights and streamline the claims process. If you are unsure about your state's rules, consult a licensed insurance agent or attorney.
Suing Another Driver: Limits and Thresholds
One of the most significant differences between no fault and at fault states is your right to sue. In at fault states, you can generally sue the at fault driver for any damages, including pain and suffering, as long as you can prove negligence. In no fault states, your right to sue is restricted by the injury threshold. You can only sue if your injuries meet the threshold, which is designed to limit frivolous lawsuits and keep premiums lower.
The threshold can be monetary (e.g., medical expenses exceeding $2,000) or verbal (e.g., fractures, disfigurement, permanent injury). Some states have both. If you meet the threshold, you can step outside the no fault system and sue the at fault driver for non economic damages. However, you would still need to prove fault in court, which can be time consuming and expensive.
Understanding your state's threshold is crucial if you are injured in an accident. If your injuries are minor and do not meet the threshold, your recovery is limited to PIP benefits. If they are serious, you may have the option to pursue a lawsuit. A local attorney can help you evaluate your case.
How Your State's System Affects Your Insurance Choices
Your state's liability system should influence the types and amounts of coverage you purchase. In no fault states, PIP is often mandatory, so you will see it on your policy. You may want to increase your PIP limits if you have limited health insurance or a high deductible. In at fault states, you should consider purchasing uninsured/underinsured motorist coverage, as a significant number of drivers may lack adequate insurance.
Additionally, your health insurance can play a role in both systems. In no fault states, PIP pays first, but health insurance may cover expenses beyond PIP limits. In at fault states, health insurance may be your primary source of payment for medical bills until a settlement is reached. If you are self employed or without employer coverage, you may need to explore individual health plans. For a deeper dive into health coverage options, a guide on comparing insurance quotes and coverage options can help you make informed decisions.
Ultimately, the best approach is to understand your state's rules, assess your personal risk, and choose coverage that protects you and your family. Comparing quotes from multiple insurers is a smart way to find competitive rates and ensure you are adequately covered.
No fault versus at fault car insurance states explained here is just a starting point. The details can be complex, and state laws change. Always verify current requirements with your state insurance department and consider consulting a licensed professional for personalized advice. By knowing how your state handles claims, you can be better prepared for the unexpected and make more confident insurance decisions.