Policyholder Rights When an Insurance Claim Is Delayed
Know your insurance policyholder rights when a claim is delayed. Call (833)-214-6397 to pressure insurers and maximize your recovery.
By Tamsin Rowe
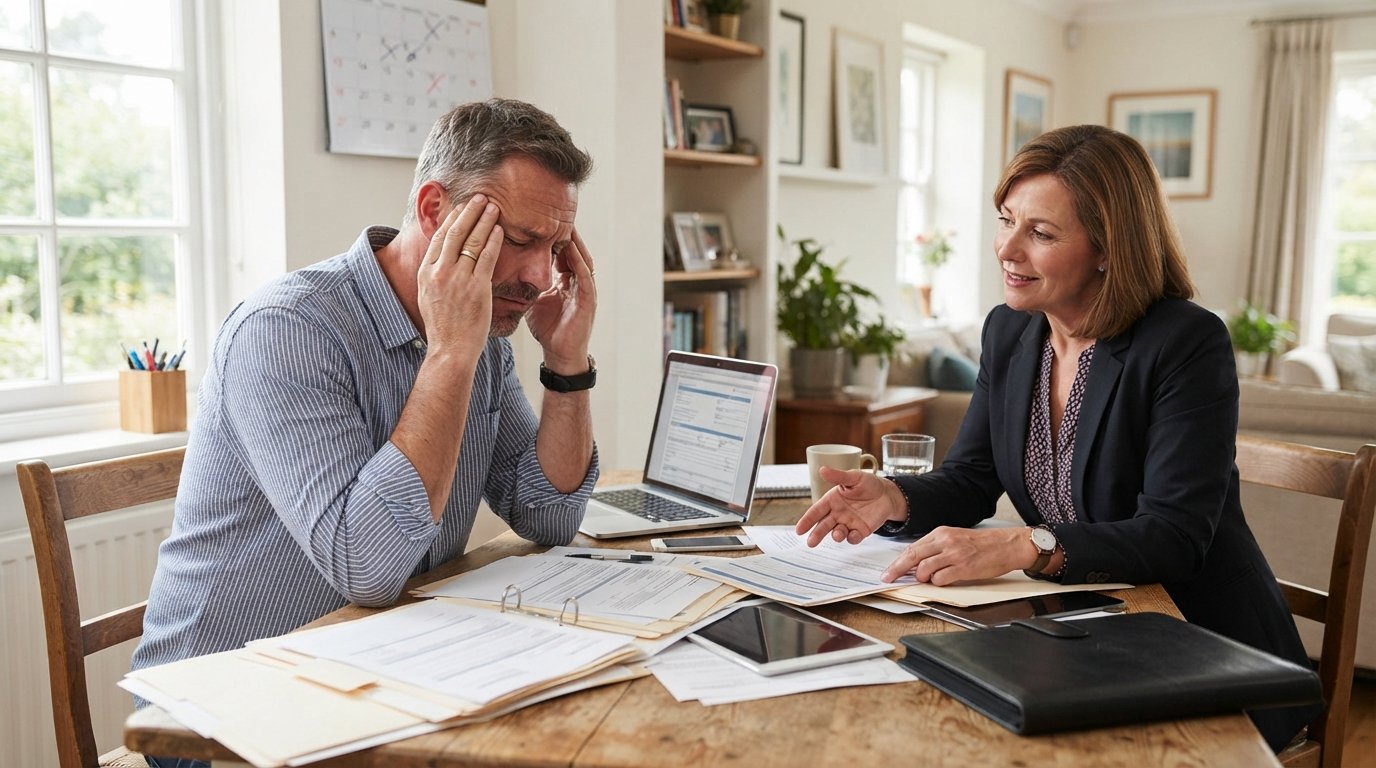
A delayed insurance claim can turn a stressful situation into a financial crisis. Whether you are waiting on a health insurance reimbursement, a homeowners claim after a storm, or an auto repair payout, the silence from your insurer can feel endless. But you are not powerless. Every state has laws that set deadlines for insurers, define unfair claim practices, and give you formal channels to push back. Understanding insurance policyholder rights when a claim is delayed is the first step toward getting the resolution you deserve. This guide walks you through the legal protections, the steps to escalate a stalled claim, and when it makes sense to bring in professional help.
What Counts as a Delayed Claim?
There is no single federal definition of a delayed claim. Instead, each state sets its own rules for how quickly an insurer must acknowledge, investigate, and pay a claim. Generally, a delay becomes legally problematic when an insurer misses statutory deadlines without a reasonable excuse. Common examples include failing to acknowledge receipt of a claim within a set number of days, failing to request necessary information in a timely manner, or failing to make a payment decision within the required period after receiving all documentation.
For health insurance, federal rules under the Affordable Care Act add another layer. Non-grandfathered group health plans and individual market plans must decide urgent care claims within 72 hours and non-urgent claims within 30 days for pre-service or 60 days for post-service claims. If an insurer misses these windows, you may have grounds for an internal appeal and, ultimately, an external review. For property and casualty claims, state prompt-payment laws typically require acknowledgment within 10 to 30 days and payment within 30 to 60 days after a proof of loss is submitted.
It is important to distinguish a legitimate delay from a bad-faith delay. A legitimate delay often involves missing information, complex investigations, or disputes over coverage. A bad-faith delay occurs when an insurer drags its feet without justification, hoping you will give up or accept a low offer. Knowing the difference helps you decide how aggressively to push back.
Key Policyholder Rights When a Claim Is Delayed
When your claim stalls, you have specific rights that are protected by state and federal law. These rights are designed to level the playing field between you and the insurance company. Here are the core protections you should know.
- Right to a prompt acknowledgment: Insurers must confirm receipt of your claim within a set number of days, typically 10 to 15 business days.
- Right to a timely investigation: The insurer must conduct a reasonable investigation and cannot delay simply to gather unnecessary information.
- Right to a written explanation for denial: If your claim is denied or partially denied, you are entitled to a written explanation citing the specific policy provisions and facts.
- Right to appeal: You have the right to appeal a denied or delayed claim through the insurer's internal process and, for health claims, an independent external review.
- Right to file a complaint: You can file a complaint with your state insurance department, which can investigate unfair claim practices.
These rights are not just theoretical. State insurance departments regularly fine insurers for violating prompt-payment laws. For example, California, New York, and Florida have some of the strictest prompt-payment rules and actively enforce them. If you suspect your insurer is violating these rules, documenting every interaction is critical. Keep a log of phone calls, emails, and letters, including dates and the names of representatives you speak with.
For health insurance claims, the appeals process is particularly structured. You typically have 180 days from the denial to file an internal appeal. If the internal appeal is denied, you may request an external review by an independent third party. This process is free for consumers and can overturn wrongful denials. The health insurance claim delayed guide on InsuranceShopping.com walks you through the specific steps for health claims, including how to request an expedited review for urgent situations.
Prompt-Payment Laws and Acknowledgment Deadlines
Prompt-payment laws are the backbone of policyholder protections against slow insurers. While the specifics vary by state, most laws follow a similar framework. The insurer must acknowledge the claim within a certain number of days, request any additional information within a set period, and then approve or deny the claim within a final deadline. For example, Texas requires acknowledgment within 15 days and a decision within 60 days. New York requires acknowledgment within 15 days and payment within 30 days after settlement.
These deadlines are not suggestions. Insurers that miss them can face penalties, including interest on the overdue payment, fines from the state, and in some cases, liability for bad faith. If your claim is delayed beyond the statutory deadline, you can cite the specific law in your communications with the insurer. This often prompts faster action because insurers know that regulators take prompt-payment violations seriously.
For health insurance, the federal timeline is even more defined. Urgent care claims must be decided within 72 hours if you have not yet received care, or 24 hours if you have. Non-urgent claims have 30 days for pre-service and 60 days for post-service. If the insurer requests an extension, it must notify you and explain why. Missing these deadlines can be a violation of federal law, giving you grounds for an appeal and a complaint to the Department of Labor or your state insurance department.
Bad-Faith Claim Practices and Unfair Settlement Conduct
Every state has laws defining unfair claim settlement practices. These laws, often based on model regulations from the National Association of Insurance Commissioners, prohibit insurers from engaging in tactics like misrepresenting policy provisions, failing to investigate promptly, offering substantially less than the claim is worth, or delaying payment without a reasonable basis. When an insurer engages in these practices, it may be acting in bad faith.
Bad faith is a legal term that carries significant consequences. If you can prove bad faith, you may be able to recover not just the claim amount but also extra-contractual damages, such as emotional distress, attorney fees, and in some states, punitive damages. However, proving bad faith requires evidence. You need to show that the insurer had no reasonable basis for delaying or denying your claim and that it knew or should have known that its conduct was unreasonable.
Common examples of bad-faith delay include repeatedly requesting the same information, failing to return phone calls, making low-ball offers without explanation, or delaying payment after agreeing to a settlement. If you experience these tactics, document everything and consider filing a complaint with your state insurance department. Regulators track patterns of bad faith and can take action against insurers that repeatedly violate the law. For a broader look at how to navigate insurance shopping and claims, InsuranceAdvisers offers additional resources and tools to help you compare coverage and understand your options.
How to File a Complaint With Your State Insurance Department
If your claim is delayed and the insurer is not responsive, filing a complaint with your state insurance department is one of the most effective steps you can take. Insurance departments have the authority to investigate complaints, request documents from insurers, and impose penalties for violations. The process is typically free and can be done online.
Before you file, gather your documentation. You will need your policy number, claim number, a timeline of events, and copies of all correspondence with the insurer. Be specific about the delay and cite the relevant state law if you know it. For example, you might write, "My claim was submitted on March 1, 2026, and I received no acknowledgment until April 10, which exceeds the 15-day requirement under state law." This kind of specificity helps regulators act quickly.
After you file, the insurance department will typically contact the insurer and request a response. Many complaints are resolved within 30 to 60 days. If the department finds a violation, it may require the insurer to pay your claim and may also fine the insurer. You can usually check the status of your complaint online or by phone. Keep in mind that while the insurance department can help resolve your claim, it cannot provide legal advice or represent you in court.
When to Consult an Attorney About a Delayed Claim
Not every delayed claim requires a lawyer, but there are situations where legal help is worth the cost. If your claim is substantial, if the insurer has repeatedly ignored your requests, or if you suspect bad faith, consulting an attorney can protect your rights and increase your chances of a fair recovery. Many insurance attorneys offer free consultations and work on a contingency fee basis, meaning they only get paid if you win.
You should consider consulting an attorney if the insurer has missed statutory deadlines by a significant margin, if the claim involves a complex coverage dispute, or if you have suffered financial hardship due to the delay. An attorney can send a demand letter, file a bad-faith lawsuit, and negotiate on your behalf. They can also help you understand whether your state allows you to recover attorney fees and other damages.
Before hiring an attorney, try the internal appeal and the state complaint process. These steps are free and often effective. If they fail, an attorney can escalate the matter. Keep in mind that lawsuits can take time, so weigh the potential recovery against the cost and stress of litigation. For most policyholders, a well-documented complaint and a firm demand letter are enough to get the insurer moving.
Steps to Take When Your Claim Is Delayed
When you find yourself waiting for an insurer to act, a structured approach can make all the difference. Here is a step-by-step framework to follow.
- Review your policy and state law: Understand the deadlines that apply to your claim and the specific rights you have.
- Document everything: Keep a log of all communications, including dates, names, and what was discussed. Save copies of all letters and emails.
- Send a written demand: Write a letter to the insurer citing the delay and requesting a response within a specific timeframe, such as 10 business days.
- File a complaint with the state insurance department: If the insurer does not respond, submit a formal complaint with supporting documentation.
- Consult an attorney if needed: If the claim remains unresolved or involves bad faith, seek legal advice.
Following these steps not only increases your chances of a timely resolution but also creates a paper trail that can support an appeal or legal action. Insurers respond to organized, informed policyholders. By knowing your rights and using the tools available, you can turn a frustrating delay into a successful claim.
Remember that insurance policyholder rights when a claim is delayed are designed to protect you. Do not hesitate to use them. Whether you are dealing with a health insurer, a home insurer, or an auto insurer, the law is on your side. Stay persistent, stay documented, and do not accept unnecessary delays.