What Does an Insurance Adjuster Do During a Claim?
What does an insurance adjuster do during a claim? They investigate, estimate damage, and negotiate settlements. Get expert help at (833)-214-6397.
By Adrian Foxe
When you file an insurance claim, the adjuster becomes the most important person in the process. They decide how much the insurer will pay, what damage counts, and when you get a check. Understanding their role helps you prepare, avoid delays, and secure a fair settlement. This guide explains what an insurance adjuster does during a claim, from the first inspection to the final payout, and how you can work with them effectively.
The Adjuster's Core Role: Investigator, Evaluator, and Negotiator
An insurance adjuster is a trained professional who investigates claims on behalf of an insurance company. Their job is to determine whether a loss is covered under your policy, estimate the cost of repairs or replacement, and recommend a settlement amount. They act as a bridge between you and the insurer, but they are paid by the insurer, which means their primary duty is to protect the company's financial interests while fairly applying the policy terms.
During a claim, adjusters wear several hats. They investigate the circumstances of the loss, evaluate damage, interpret policy language, and negotiate with policyholders or their representatives. They also document everything meticulously, because their findings support the insurer's decision and may be used in disputes or litigation. The adjuster's work begins the moment a claim is filed and continues until the claim is resolved or denied.
It is important to remember that adjusters are not on your side in the way a lawyer or public adjuster would be. They are professionals doing a job, and most aim to be fair, but their loyalty lies with the insurer. Knowing this helps you approach the process with realistic expectations and a proactive mindset.
Types of Adjusters: Staff, Independent, and Public
Not all adjusters work the same way. The type of adjuster handling your claim affects how the process unfolds and what you can expect. There are three main categories: staff adjusters, independent adjusters, and public adjusters.
Staff adjusters are employees of the insurance company. They handle claims day in and day out, often within a specific region or line of business. Because they work directly for the insurer, they are familiar with its policies, procedures, and settlement guidelines. Staff adjusters are common for routine claims like minor auto accidents or small homeowners claims.
Independent adjusters are contractors hired by the insurer to handle claims, often during catastrophic events like hurricanes, wildfires, or hailstorms. They may work for multiple insurers and are brought in when the volume of claims exceeds the company's capacity. Independent adjusters follow the insurer's guidelines but are not permanent employees. They can be efficient, but because they are temporary, they may have less familiarity with your specific policy.
Public adjusters are completely different: they are licensed professionals who represent the policyholder, not the insurer. You hire and pay them (usually a percentage of the settlement) to prepare, document, and negotiate your claim. Public adjusters are especially useful for large or complex claims, such as major fire damage or business interruption losses. They can level the playing field when you feel outmatched by the insurer's resources.
Understanding which type of adjuster you are dealing with helps you communicate effectively and know when to seek additional help. If you are unsure, ask the adjuster directly who they work for and what their role is.
Step-by-Step: What an Adjuster Does During a Claim
From the moment you file a claim to the final settlement, the adjuster follows a structured process. While every claim is unique, most follow a similar path. Here is a step-by-step breakdown of what an insurance adjuster typically does during a claim.
1. Initial Contact and Claim Review
After you report a claim, the adjuster is assigned and will contact you, usually by phone or email, within a few days. During this initial contact, the adjuster introduces themselves, explains the process, and gathers basic information about the loss: what happened, when it happened, and what damage occurred. They will also confirm your policy details, including coverage limits and deductibles.
This is your first opportunity to ask questions and clarify expectations. The adjuster may request that you provide a recorded statement, but you are not obligated to give one without preparation. You can ask to provide a written statement instead or request time to review your policy. The adjuster will also schedule an inspection, which is the next critical step.
2. Inspection and Documentation
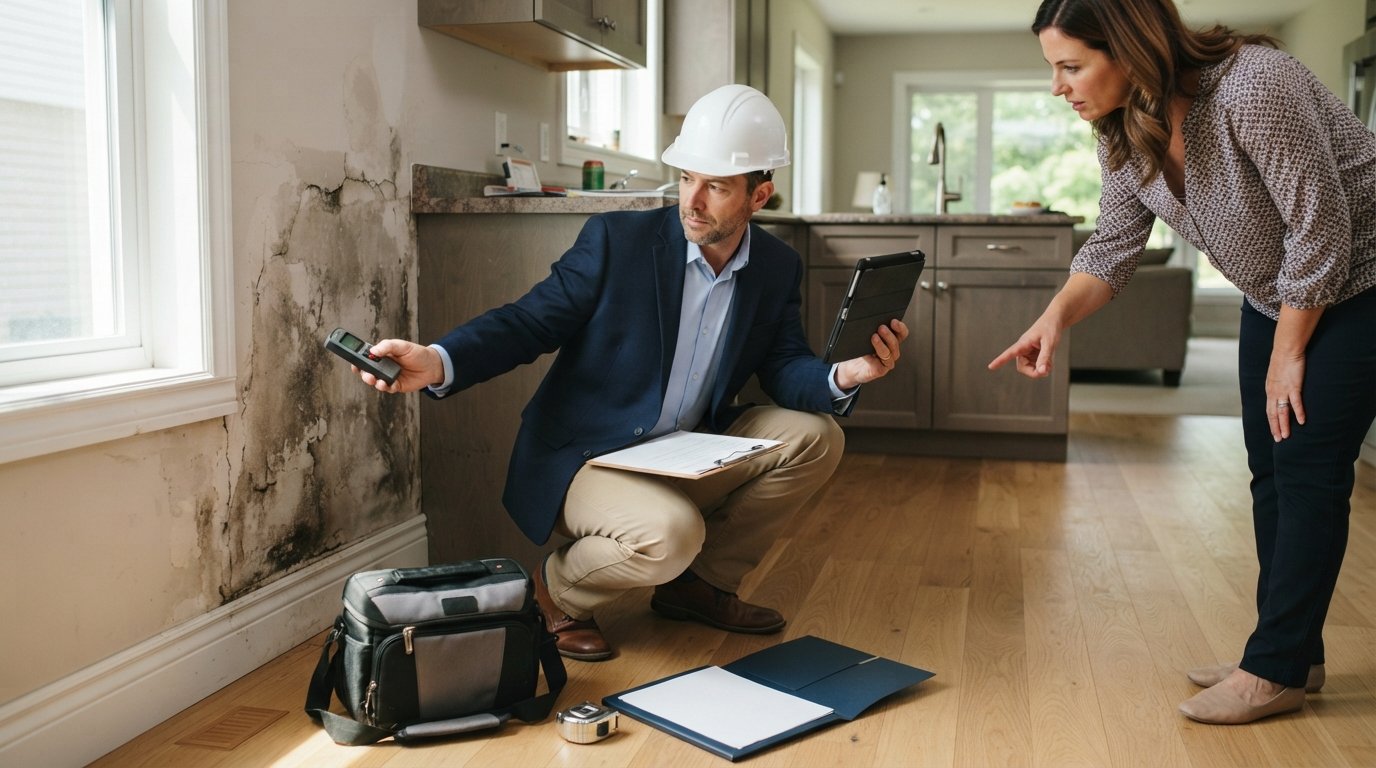
The inspection is where the adjuster gathers evidence. They will visit the damaged property (or examine the vehicle) to assess the extent of the loss. During the inspection, the adjuster takes photographs, measurements, and notes. They may also interview you and any witnesses, and they will look for signs of pre-existing damage or maintenance issues that could affect coverage.
Before the inspection, you should gather your own documentation: photos and videos of the damage, receipts for damaged items, and any relevant records. Having this ready speeds up the process and ensures nothing is overlooked. The adjuster will compare your documentation with their own findings, so being organized helps your case.
After the inspection, the adjuster may request additional documents, such as contractor estimates, medical records (for injury claims), or proof of ownership for valuable items. They may also consult with specialists like engineers or appraisers for complex damages.
3. Damage Evaluation and Estimation
Once the evidence is collected, the adjuster evaluates the damage. This involves determining the scope of repairs or replacement, applying policy limits, and calculating depreciation. For property claims, adjusters often use estimating software that factors in labor, materials, and regional pricing. They may also rely on contractor estimates you provide, but they are not required to accept them.
Depreciation is a key concept. Most policies pay actual cash value (ACV) or replacement cost value (RCV). ACV is the cost to replace the item minus depreciation, while RCV pays the full cost to replace without deducting depreciation (up to policy limits). The adjuster calculates depreciation based on the age and condition of the damaged property. Understanding these terms helps you anticipate your settlement.
If the adjuster's estimate seems low, you can provide additional evidence, such as independent contractor bids or expert opinions, to support a higher valuation. The adjuster may revise the estimate if presented with convincing information.
4. Policy Application and Coverage Determination
The adjuster then applies your policy terms to the evaluated damage. They determine which damages are covered, which are excluded, and how much your deductible applies. They also check for any sublimits or special provisions that might affect the payout. This step requires a careful reading of your policy, and the adjuster may consult with underwriters or legal teams for complex issues.
If coverage is denied in whole or in part, the adjuster should explain the reason in writing, citing specific policy language. You have the right to appeal a denial or dispute the adjuster's interpretation. Many insurers have an internal appeals process, and you can also contact your state's department of insurance for guidance. For more on navigating disputes, see our guide on what happens after a no-fault accident.
5. Negotiation and Settlement Offer
After determining coverage, the adjuster calculates a settlement offer. This offer includes the cost of covered repairs or replacement, minus your deductible, and any depreciation if applicable. The adjuster presents the offer to you, often with a detailed estimate, and negotiates if you disagree.
Negotiation is common. You can present counterarguments, additional estimates, or evidence of overlooked damage. The adjuster may have some flexibility, but they are bound by the insurer's guidelines. If you cannot reach an agreement, you may escalate the claim, request a re-inspection, or invoke your policy's appraisal clause. In some cases, hiring a public adjuster can help, but weigh the cost (typically 10-15% of the settlement) against the potential increase.
Once you accept the offer, the adjuster processes the payment. For large claims, the insurer may issue partial payments as repairs progress. The adjuster may also coordinate with contractors or vendors to ensure the work is completed.
6. Claim Closure and Recordkeeping
Finally, the adjuster closes the claim after payment is issued and all issues are resolved. They document the entire process, including photos, estimates, correspondence, and the final settlement. This record is important if you later discover additional damage or need to reopen the claim (within the policy's time limits).
Keep copies of all documents you receive from the adjuster, and maintain your own records of the claim. Good recordkeeping protects you if disputes arise.
Documents and Photos to Gather Before the Inspection
Preparation is your best defense against a low settlement. Before the adjuster arrives, gather as much evidence as possible. This not only helps the adjuster but also ensures your claim is fully documented.
Here is a checklist of key items to have ready:
- Photos and videos of the damage: Take wide shots and close-ups from multiple angles. Include timestamps if possible.
- Receipts and proof of purchase: For damaged items, especially high-value electronics, furniture, or jewelry.
- Contractor estimates: Get at least two independent estimates for repairs.
- Policy documents: Have your policy number and a copy of your coverage details handy.
- Records of maintenance and repairs: Show that you have maintained the property, which can counter claims of neglect.
Additionally, create a home inventory if you do not already have one. A detailed list of your belongings, with photos and values, makes it easier to substantiate your loss. The adjuster will appreciate your organization, and it reduces the chance of missed items.
During the inspection, walk with the adjuster and point out all damage. Do not assume they will notice everything. Ask questions and take notes. If the adjuster says something you do not understand, ask for clarification. You are entitled to a clear explanation.
How Adjusters Estimate Damage and Apply Depreciation
Estimating damage is both an art and a science. Adjusters use a combination of visual inspection, measurement, and standardized pricing tools. For property claims, they often use software like Xactimate, which contains regional pricing for labor and materials. They input the scope of work (e.g., replace 200 square feet of roofing) and the software generates an estimate.
Depreciation is subtracted from the replacement cost to arrive at actual cash value (ACV). Depreciation reflects the age and wear of the damaged item. For example, a 10-year-old roof may have a useful life of 20 years, so its depreciation might be 50%. The adjuster uses industry tables or formulas to calculate this. If your policy pays replacement cost, you may receive the full replacement cost upfront or in two payments: first the ACV, then the recoverable depreciation once repairs are completed and documented.
Understanding how depreciation works helps you evaluate the settlement. If you plan to repair or replace, replacement cost coverage is more beneficial. If you have ACV coverage, expect a lower payout. You can also ask the adjuster to explain how they calculated depreciation and whether any items are eligible for full replacement cost.
For auto claims, adjusters use similar methods, often relying on industry databases like CCC or Mitchell to value vehicles and parts. They may declare a vehicle a total loss if repairs exceed a certain percentage of its value. In that case, the settlement is based on the vehicle's actual cash value, which you can negotiate if you have evidence of higher value (e.g., recent upgrades, low mileage).
When a Public Adjuster May Be Worth Hiring
Public adjusters can be valuable allies in certain situations. They are licensed professionals who work exclusively for you, handling the entire claims process from documentation to negotiation. They charge a fee, usually a percentage of the settlement, so you only pay if you get paid.
Consider hiring a public adjuster if:
- Your claim is large or complex (e.g., major fire, flood, or business interruption).
- You feel overwhelmed by the process or lack the time to manage it.
- The insurer's offer seems unreasonably low or coverage is disputed.
- You have already appealed and are not satisfied with the response.
Public adjusters can often secure higher settlements because they know how to document damage thoroughly and negotiate effectively. However, they are not a guarantee, and their fee reduces your net payout. For small or straightforward claims, they may not be cost-effective. Always check licensing and references before hiring one.
If you decide to hire a public adjuster, inform your insurer. The insurer will still assign its own adjuster, but your public adjuster will handle communications and negotiations on your behalf.
How to Work Effectively with Your Adjuster
Good communication with your adjuster can make the process smoother and improve your outcome. Here are some practical tips:
- Be responsive: Answer calls and emails promptly. Delays can prolong the claim.
- Document everything: Keep a log of all conversations, including dates, names, and what was discussed.
- Ask questions: If something is unclear, ask for an explanation in writing.
- Be honest and consistent: Inconsistencies can raise red flags and slow down the claim.
- Know your rights: Familiarize yourself with your policy and your state's insurance regulations.
Remember that the adjuster is not your adversary, but they are not your advocate either. A cooperative, professional relationship often leads to better results than an adversarial one.
If you are shopping for insurance or want to compare policies to ensure you have adequate coverage before a loss occurs, resources like QuoteComparison can help you evaluate options from multiple insurers. Being well-informed about your coverage is the best way to avoid surprises during a claim.
Understanding what an insurance adjuster does during a claim empowers you to navigate the process with confidence. By preparing documentation, asking questions, and knowing when to seek professional help, you can work toward a fair settlement and protect your financial interests.