Wildfire Insurance Options for Homes in High Risk Areas
Explore wildfire insurance options for homes in high risk areas, from FAIR Plans to extended replacement cost. Call (833)-214-6397 for expert guidance.
By Isolde Fenwick
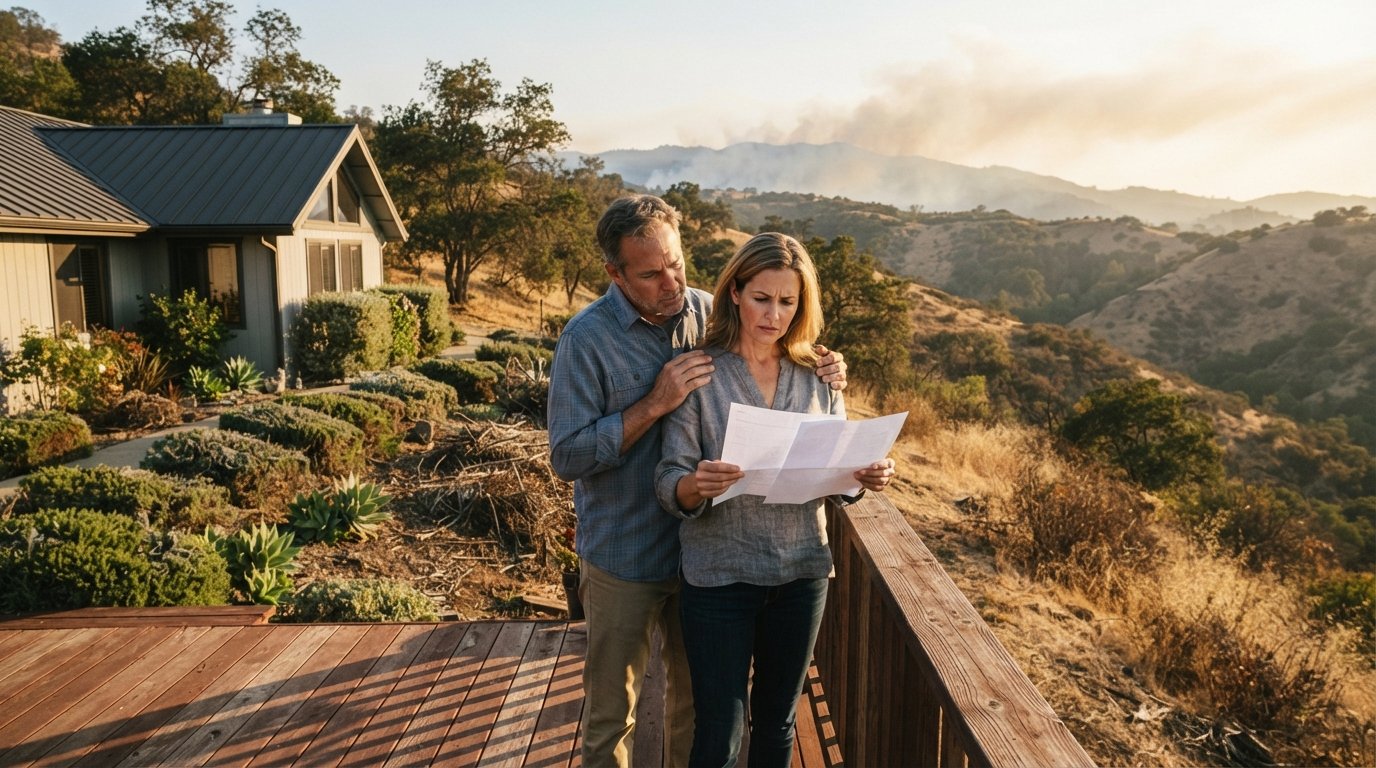
Your renewal notice arrives with a number you did not expect: a non-renewal. Or perhaps your premium jumped by 60 percent in a single year, and your agent cannot explain why beyond a vague reference to "catastrophe modeling." For homeowners in fire-prone canyons, foothills, and wildland-urban interface zones, this scenario has become routine. The standard insurance market has retreated from many high-risk regions, leaving families to navigate a confusing patchwork of state-backed plans, surplus lines carriers, and specialized endorsements. Understanding your wildfire insurance options for homes in high risk areas is no longer a niche skill; it is essential financial literacy for anyone living where embers can travel a mile ahead of a flame front.
This guide walks through the real choices available to you, from state FAIR plans and residual markets to the practical steps that can make a standard carrier reconsider your property. We will also examine how replacement cost provisions work, where to shop when national brands pull back, and how to evaluate whether a policy actually protects your ability to rebuild. The goal is not to sell you on a single solution but to map the terrain so you can ask better questions and make informed decisions.
Why the Standard Market Is Retreating from Fire Zones
Insurance carriers use catastrophe models that simulate wildfire probability, intensity, and loss. In the past decade, several factors have converged to make those models less favorable for properties in high-risk areas. Prolonged drought cycles, accumulated fuel loads in forests, and expanding development into wildlands have increased both the frequency and severity of losses. At the same time, reinsurance costs (the insurance that insurers buy for themselves) have risen sharply after major fire years. When a carrier's reinsurance bill climbs, it tightens underwriting standards, raises premiums, or exits regions entirely.
The result is a market where a home that was insurable five years ago may now be declined by every major carrier. This is not necessarily a reflection of your specific property's risk; it is a portfolio-level decision. Insurers are limiting their aggregate exposure to wildfire in any given state. When they hit that ceiling, they stop writing new policies regardless of individual home characteristics. That is why two neighbors on the same street can receive different outcomes: one retained, one non-renewed, based on when their policy came up for renewal and which carrier held it.
For consumers, this creates a frustrating paradox. You may have maintained your home meticulously, cleared brush, and installed a fire-resistant roof, yet still face non-renewal because your carrier is reducing its overall footprint. The key is to understand that the standard market is not monolithic. Some regional carriers and specialty insurers remain active in high-risk zones, but they often require specific mitigation features and may price accordingly. Finding them requires a deliberate shopping strategy rather than a single phone call to a captive agent.
State FAIR Plans and Residual Market Options
When the voluntary market fails, many states offer a residual market mechanism, often called a FAIR Plan (Fair Access to Insurance Requirements). These plans are not charities; they are insurance pools backed by the state's participating carriers, designed to provide basic property coverage for those who cannot obtain it elsewhere. FAIR Plans typically cover the dwelling and personal property against fire, lightning, and internal explosion, and some have expanded to include wind or other perils. However, they are usually bare-bones policies: they may exclude liability, medical payments, and theft, and they often have lower coverage limits than a standard homeowners policy.
FAIR Plans are available in several states with significant wildfire exposure, including California, Oregon, and Washington, though the specific names and structures vary. In California, for example, the FAIR Plan has seen a massive influx of new policies as the voluntary market has contracted. The plan offers dwelling fire coverage and, in some cases, a homeowners policy that includes liability. But applicants should understand the trade-offs: premiums can be higher than standard market rates for comparable coverage, and the policy may not include the comprehensive protections you expect.
Here is how the typical FAIR Plan process works:
- Verify eligibility: You generally must show that you have been declined by at least one admitted carrier or that no admitted carrier will offer you coverage. Some states require a denial letter or a specified number of declinations.
- Submit an application: Provide property details, including construction type, roof age, and defensible space information. Inspections may be required.
- Receive a quote and bind coverage: If approved, you pay the premium and the policy takes effect. Be aware that FAIR Plans may require payment in full rather than installments.
- Consider a difference in conditions (DIC) policy: Because FAIR Plans are limited, many homeowners pair them with a DIC policy from a surplus lines carrier to fill gaps such as liability, water damage, or higher limits.
The FAIR Plan is a safety net, not a long-term solution for most homeowners. It is best used as a bridge while you continue shopping for a more comprehensive policy or while you complete mitigation work that may make you eligible for a standard carrier. It is also worth noting that FAIR Plan assessments can be levied on all policyholders in the state if the plan suffers a major loss, so the true cost may extend beyond your premium.
What Defensible Space and Fire-Hardening Can Do for Eligibility
Insurers increasingly differentiate between homes based on measurable mitigation features. The concept of defensible space, the buffer between a structure and the surrounding wildland, is not just a firefighter recommendation; it is becoming an underwriting criterion. Carriers may ask for photographic evidence of brush clearance, tree spacing, and roof type. Some have developed proprietary scoring systems that reward specific upgrades. While mitigation cannot guarantee eligibility, it can move your property from "decline" to "review" or from "review" to "accept" with certain carriers.
The most impactful upgrades typically fall into two categories: site-level defensible space and building-level fire hardening. Site-level work includes clearing flammable vegetation within a certain radius of the home, removing ladder fuels that can carry fire from the ground into tree canopies, and maintaining a noncombustible zone around the foundation. Building-level work includes installing a Class A fire-rated roof, using noncombustible siding, enclosing eaves and soffits, and covering vents with fine mesh to prevent ember intrusion. Embers are the primary cause of home loss in wildfires, so vent screening and deck maintenance are often weighted heavily by underwriters.
Here is a practical framework for prioritizing mitigation investments:
- Start with the roof and vents: These are the most common ember entry points. A Class A roof and 1/8-inch mesh vent screens offer high return on investment.
- Create the first five feet of noncombustible zone: Remove all flammable mulch, plants, and stored items within five feet of the foundation. Replace with gravel or concrete.
- Address the deck: If you have a wood deck, consider replacing it with a noncombustible material or at least maintain the underside free of debris and enclose it if possible.
- Thin and space vegetation: Within 30 feet, keep grass mowed and shrubs isolated. Within 100 feet, reduce tree density and remove lower branches.
- Document your work: Keep dated photos, receipts, and a written log. Insurers may request proof, and having a mitigation file can speed up underwriting.
Some states and local agencies offer grants or cost-share programs for mitigation, and a few insurers provide premium discounts for verified upgrades. It is worth asking any prospective carrier whether they recognize specific mitigation standards, such as those from the National Fire Protection Association (NFPA) or your state's fire safe council. Even if a discount is not available, the documentation can be the difference between a declination and an offer.
Replacement Cost vs. Extended Replacement Provisions
When you do find a policy, the coverage limit matters as much as the premium. Replacement cost coverage pays to rebuild your home with materials of similar quality and current labor costs, without deducting for depreciation. Actual cash value (ACV) coverage, by contrast, deducts depreciation, which can leave you with a fraction of the funds needed to rebuild after a total loss. In wildfire zones, where rebuilding costs have skyrocketed due to demand and material shortages, ACV coverage is particularly dangerous.
Even replacement cost policies have limits. Standard policies typically cap replacement cost at the dwelling limit stated on the declarations page. If your home is underinsured, you bear the difference. Extended replacement cost coverage (sometimes called extended replacement cost or ERC) provides a buffer, often 125 percent to 200 percent of the dwelling limit, to account for unexpected cost overruns. Some carriers offer an even stronger provision called guaranteed replacement cost, which pays whatever it costs to rebuild, though these policies are increasingly rare.
For homeowners in high-risk areas, extended replacement cost is often worth the additional premium. Construction costs in fire-affected regions can spike after a major event because of labor shortages and code upgrades. Building codes may also require upgrades to meet current wildfire standards, which can add 20 to 30 percent to rebuilding costs. A policy with a 150 percent extended replacement cost provision provides meaningful breathing room. When comparing quotes, look beyond the dwelling limit and ask specifically: "Does this policy include extended replacement cost, and what percentage?" Also ask whether the carrier offers inflation guard, which automatically adjusts the dwelling limit over time, and whether ordinance or law coverage is included to pay for code-required upgrades.
If you are shopping for coverage, you can use comparison tools to evaluate quotes side by side. For a broad overview of insurance shopping resources, see QuoteComparison, which provides educational content and connects consumers with providers across multiple insurance lines. The key is to compare not just price but coverage structure: a cheaper policy with ACV coverage and no extended replacement cost may cost you far more in the long run.
Where to Shop When Standard Carriers Pull Back
When national carriers decline your property, the shopping process changes. You are no longer comparing Geico to State Farm; you are navigating a segmented market that includes regional admitted carriers, surplus lines carriers, FAIR Plans, and specialized wildfire insurers. Each has different appetites, eligibility rules, and coverage forms. A single independent agent may not have access to all of them, so you may need to work with multiple agents or use online tools to broaden your reach.
Start with independent agents who specialize in high-risk property. These agents often have relationships with regional carriers that do not advertise nationally but actively write policies in fire-prone areas. Ask specifically whether they have appointments with carriers that write in your ZIP code and whether those carriers have a history of non-renewals in the area. A good agent will be transparent about which carriers are stable and which are retreating.
Surplus lines carriers are another option. These are insurers that are not admitted in your state, meaning they are not backed by the state guaranty fund and are less regulated on rates and forms. They can offer flexible coverage for high-risk properties, but you should review the policy carefully for exclusions and confirm the carrier's financial strength rating. Surplus lines policies are often written on a nonstandard form, so the language may differ from a standard homeowners policy.
Here is a step-by-step approach to shopping in a constricted market:
- Gather your property documentation: Include roof age, construction type, mitigation features, and any inspection reports. This will speed up quotes.
- Contact at least three independent agents: Ask each which carriers they represent for high-risk wildfire properties and whether those carriers are currently writing new business.
- Check the state FAIR Plan as a baseline: Even if you do not intend to use it, a FAIR Plan quote gives you a comparison point and may be required to prove you cannot get coverage elsewhere.
- Explore surplus lines and specialty carriers: Ask agents about non-admitted options and review the policy forms for exclusions related to wildfire or smoke damage.
- Consider a DIC policy to fill gaps: If you end up with a FAIR Plan or a bare-bones policy, a DIC policy can add liability and broader coverage.
- Review replacement cost provisions carefully: Do not assume that a higher premium means better coverage. Confirm the dwelling limit, extended replacement percentage, and ordinance or law coverage.
One often-overlooked resource is your state insurance department. Many departments publish lists of carriers writing in high-risk areas, consumer guides to FAIR Plans, and tips for mitigation. They may also have complaint data that can help you evaluate a carrier's claims reputation. Additionally, if you own a mobile or manufactured home in a high-risk area, the shopping dynamics can differ; our guide on affordable mobile home insurance options explains how to approach coverage for those structures.
Practical Steps to Protect Your Coverage and Your Home
Securing a policy is only half the battle. Once you have coverage, you need to maintain it and prepare for the possibility of a claim. Insurers increasingly conduct annual inspections or request mitigation updates. Failing to maintain defensible space can lead to non-renewal even after you have been accepted. Set a calendar reminder to review your policy annually, update your dwelling limit for inflation, and document any home improvements. If you make mitigation upgrades, notify your carrier and ask whether they qualify for a discount or a coverage enhancement.
In the event of a wildfire, having a clear inventory of your belongings and a documented mitigation file can streamline the claims process. Take a video walkthrough of your home each year, store it in the cloud, and keep receipts for major purchases. Understand your policy's deductible, especially if it has a separate wildfire deductible expressed as a percentage of the dwelling limit. A two percent deductible on a $500,000 home is $10,000, which you will need to pay out of pocket before insurance kicks in.
Finally, consider the broader financial picture. If insurance costs in your area have become unsustainable, you may need to evaluate whether staying is financially viable. That is a personal decision, but it is better made with clear information about your options. The market for wildfire insurance is evolving, and new carriers and state programs may emerge. Staying informed and shopping proactively, rather than waiting for a renewal crisis, gives you the most leverage.
Wildfire risk is not going away, but neither are the options for homeowners who are willing to navigate the market deliberately. From FAIR Plans to surplus lines to mitigation-driven eligibility, the path forward requires patience and a willingness to ask detailed questions. By understanding the trade-offs and documenting your efforts, you can find coverage that protects your home and your financial future.