Classic Car Insurance Eligibility Rules for Collector Vehicles
Understand classic car insurance eligibility rules for collector vehicles, from agreed value to storage limits. Call (833)-214-6397 for expert guidance.
By Adrian Foxe
Collector car ownership is about passion, preservation, and the satisfaction of keeping a piece of automotive history on the road. But the insurance that protects that investment is not the same as the policy on your daily commuter. Standard auto insurance is built around market value and daily use, while collector vehicle coverage is designed around agreed value, limited mileage, and proper storage. Understanding the classic car insurance eligibility rules for collector vehicles before you shop can save you from a denied claim, a low payout, or a policy that never really matched your car's worth. The rules are not arbitrary: they exist because insurers are protecting a specialized risk, and knowing them puts you in a stronger position to compare quotes and ask the right questions.
The core issue is that a collector car is usually not a depreciating appliance. It may be appreciating, it may be irreplaceable, and it may spend most of its life in a garage. Insurers therefore apply different eligibility standards, and those standards vary by carrier. Some are strict, some are flexible, and some specialize in certain eras or vehicle types. The sections below walk through how eligibility is defined, what documentation you will likely need, and how to prepare before you call a licensed agent.
How Insurers Define Classic, Antique, and Collectible Vehicles
There is no single federal definition of a classic car, and that is the first thing collectors need to understand. Eligibility often depends on the insurer's own underwriting guidelines, which may reference age, production numbers, condition, and intended use. A common industry starting point is that a vehicle becomes eligible for classic treatment at roughly 20 to 25 years old, but that threshold is not universal. Some carriers use 15 years for certain models, while others focus less on age and more on rarity or collector interest.
Antique vehicles are often defined more narrowly, sometimes as vehicles 25 years or older that are maintained in original condition and used only for exhibitions, club activities, and occasional pleasure drives. Collectible is the broadest category and can include modern limited-production sports cars, muscle cars from the 1960s and 1970s, vintage trucks, and even motorcycles. The label matters because it drives the eligibility questionnaire: an insurer may ask whether the vehicle is stock, modified, or a replica, and each answer can change which program applies.
Condition and originality also play a role. A numbers-matching restoration in excellent condition is easier to place than a heavily modified project car. That does not mean modified cars are uninsurable, but they often require a specialty carrier or a stated value approach. Collectors should expect to describe the vehicle accurately, because misrepresenting its condition or use is one of the fastest ways to void coverage when a claim occurs.
Mileage, Storage, and Daily-Driver Limits
Most collector policies assume the vehicle is not your primary transportation. That assumption is central to eligibility. Insurers typically ask how many miles you drive per year, whether you have another vehicle for daily use, and where the collector car is parked. Annual mileage limits are common, and while the exact number varies, many programs set a range such as 3,000 to 7,500 miles per year. Some policies offer unlimited mileage for certain vehicle types, but that is the exception rather than the rule.
Storage requirements are equally important. A garage is often required, though some carriers accept a carport or a secured covered structure for certain vehicles. The reasoning is straightforward: a car stored indoors is less exposed to weather, theft, and vandalism, which lowers the risk the insurer is accepting. If you do not have a garage, do not assume you are automatically excluded, but be prepared for a higher premium or a narrower list of carriers.
Daily-driver use is the most common eligibility stumbling block. If you plan to drive your classic to work, run errands in it, or use it as your only vehicle, a standard policy may be the better fit, even if it means accepting actual cash value. Collector policies are built for occasional pleasure use, club events, and shows. Some carriers allow limited pleasure driving and occasional errands, but commuting is usually excluded. A licensed agent can clarify how a specific carrier defines permitted use, which is far more reliable than guessing based on a website summary.
Agreed Value Versus Stated Value Versus Actual Cash Value
The valuation method is where collector coverage differs most sharply from standard auto insurance. Actual cash value, the basis for most everyday policies, pays replacement cost minus depreciation. For a collector car, that can be a painful outcome, because the market for a well-kept classic may be far above what a depreciation formula suggests. Stated value policies list an amount, but the payout may be limited to the lesser of the stated amount or the actual cash value at the time of loss, which can leave a gap.
Agreed value is the gold standard for collector vehicles. The insurer and the policyholder agree on a value at the start of the policy, often supported by an appraisal, photos, and documentation. In the event of a total loss, the agreed amount is typically paid without a depreciation deduction, subject to policy terms. That certainty is why collectors pursue agreed value coverage, and it is also why insurers ask for more evidence before issuing the policy.
Each approach carries tradeoffs that are worth weighing before you shop:
- Agreed value: highest certainty for total losses, usually requires documentation and sometimes an appraisal, and premiums reflect the agreed amount.
- Stated value: simpler to arrange, but the payout may be capped by actual cash value, so it can underperform expectations.
- Actual cash value: common on standard policies, generally the least protective for a collector car, and best suited to vehicles driven daily.
Collectors should also ask about deductibles, spare parts coverage, and whether the policy includes coverage for tools, memorabilia, or a partially completed restoration. These details rarely appear in a headline quote, but they matter when a claim happens. If you are also shopping for everyday coverage, resources such as this guide to affordable health insurance in North Carolina show how the same comparison discipline applies across insurance categories.
Documentation and Photos Collectors Are Usually Asked to Provide
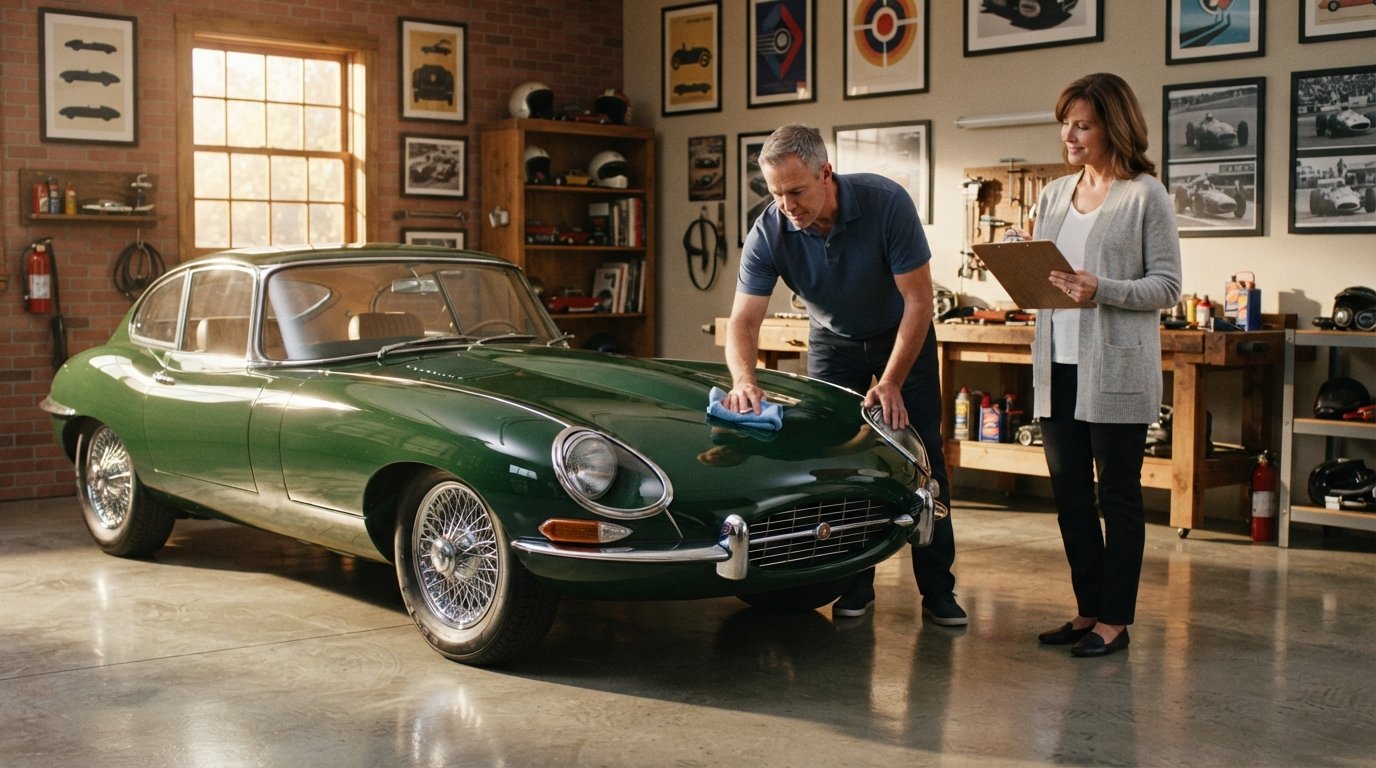
Because agreed value policies depend on an accurate valuation, insurers typically request documentation before binding coverage. The exact list varies, but collectors should expect to provide evidence of the vehicle's identity, condition, and value. Clear, well-lit photos are standard: exterior from multiple angles, interior, engine bay, odometer, and any distinctive features or flaws. Photos taken after a recent wash and in good light are more useful than blurry snapshots, and they help avoid disputes later.
Paperwork usually includes the title, registration, and a bill of sale if the vehicle was recently purchased. For restored or modified cars, receipts for parts and labor strengthen the file. An independent appraisal is often requested for higher-value vehicles or for builds where market comparables are scarce. Some carriers accept a professional appraisal from a recognized collector appraiser, while others rely on their own valuation tools and photos.
A practical documentation checklist helps the process move faster:
- Gather the title, registration, and purchase documents.
- Take dated photos of the exterior, interior, engine, odometer, and VIN plate.
- Collect receipts for restoration, modifications, and major maintenance.
- Obtain an appraisal if the vehicle is high value or heavily customized.
- Note storage arrangements, including garage photos and security features.
Accurate documentation does more than satisfy underwriting. It creates a record that supports your agreed value if a claim is filed, and it reduces the chance of a disagreement about condition or authenticity. Collectors who keep a simple digital folder with photos and receipts tend to have a smoother experience at renewal and at claim time.
Questions to Ask a Licensed Agent About Eligibility
Eligibility rules are carrier-specific, so the most reliable path is a conversation with a licensed agent who can match your vehicle and usage to the right program. Before that call, clarify your own situation: how often you drive the car, where it is stored, whether it is modified, and what value you believe it holds. Then ask questions that surface the details a quote page will not show.
Useful questions include whether the carrier requires a garage, what the annual mileage limit is, whether commuting is excluded, and how agreed value is determined at renewal. Ask about the claims process for a total loss, whether spare parts and tools are covered, and whether the policy includes trip interruption or flatbed towing. It is also worth asking what happens if you sell the car or add a second collector vehicle, since multi-vehicle discounts and policy adjustments can change the math.
Consumers who want a broader view of how insurance shopping works can compare options through trusted resources. Sites such as InsuranceAdvisers provide educational content and comparison tools across auto, home, health, life, and Medicare coverage, which can help frame the questions you bring to an agent. The goal is not to self-underwrite, but to arrive informed enough to recognize a policy that actually fits your collector car rather than one that merely looks inexpensive.
Finally, revisit eligibility at every renewal. Mileage habits change, storage situations change, and values move with the market. A policy that fit five years ago may no longer reflect your car's worth or your use. A short annual review keeps the agreed value current and confirms that the classic car insurance eligibility rules for collector vehicles still work in your favor.