Does Homeowners Insurance Cover Ordinance or Law Upgrades?
Does homeowners insurance cover ordinance or law upgrades? Standard policies cap code upgrade payouts, but an endorsement can close the gap. Call (833)-214-6397 for help.
By Adrian Foxe
When a fire, storm, or other covered peril damages your home, the last thing you want is a surprise bill for bringing the rebuilt structure up to current building codes. Many homeowners assume their policy will pay for everything needed to restore their home to a safe, legal condition. The reality is more nuanced. The answer to the question, does homeowners insurance cover ordinance or law upgrades, is that standard policies include only a limited amount of protection, and that protection is often far less than what older homes actually need. Understanding how this coverage works, where the gaps lie, and how to close them can save you tens of thousands of dollars after a loss.
What Ordinance or Law Coverage Actually Pays For
Ordinance or law coverage, sometimes called code upgrade coverage, is a specific provision within a homeowners policy that addresses the extra costs of complying with building codes, zoning ordinances, and laws during the repair or rebuild of a damaged home. Without this coverage, your insurer would only pay to replace what was there before the loss, using materials and methods that may no longer be legal. If your local building department requires upgrades to electrical wiring, plumbing, insulation, or structural framing when you pull a permit for reconstruction, those costs would otherwise fall on you.
This coverage typically has three distinct parts. The first covers the cost to demolish and remove the undamaged portions of a structure when a code requires it, which is common when a partial loss leaves a building that cannot legally be repaired as is. The second covers the increased cost to rebuild the damaged portion in compliance with current codes. The third, less common part covers the loss of value of an undamaged structure because a code now prohibits rebuilding it as it was, such as when a home sits too close to a property line under modern setback rules.
It is important to note that this coverage applies only when the loss itself is caused by a peril your policy covers, such as fire, wind, or hail. It does not pay for upgrades you choose to make voluntarily, nor does it help with routine renovations or code compliance for an undamaged home. The trigger is always a covered claim followed by a legal requirement to rebuild to a higher standard.
Typical Limits and How Percentage-of-Dwelling Calculations Work
Most standard homeowners policies include ordinance or law coverage as an automatic extension, but the limit is usually a percentage of your dwelling coverage, commonly 10 percent. That means if your home is insured for $400,000 on the dwelling portion, you might have $40,000 available for code upgrades. On the surface that sounds generous, but in practice it can disappear quickly. A full electrical rewire, new foundation anchoring, upgraded windows for energy codes, and modern fire suppression can easily exceed that amount, especially in older homes or areas with stringent codes.
The percentage is applied to the dwelling limit, not to the total policy limit, and it is typically a sublimit rather than additional insurance. In other words, the money for code upgrades comes out of the same pool as your dwelling coverage, which can leave you underinsured for the actual rebuild. Some insurers offer higher automatic limits, such as 25 or 50 percent, and some allow you to purchase a higher limit by endorsement. The key is to read your policy declarations page and the ordinance or law section carefully to see what percentage applies and whether the limit is shared with other extensions.
Here is a simple framework to estimate whether your current limit is adequate:
- Identify the code requirements in your area: Ask your local building department what upgrades are typically triggered by a rebuild permit, such as seismic anchoring, wind mitigation, or energy efficiency measures.
- Get a rough cost estimate: A contractor can provide ballpark figures for common upgrades like electrical, plumbing, and roof-to-wall connections.
- Compare that estimate to your policy limit: If the estimate exceeds your ordinance or law sublimit, you likely need a higher endorsement.
- Factor in demolition and debris removal: These costs can be substantial and are often subject to the same sublimit.
For a more precise picture, consider a professional replacement cost estimate that includes code upgrade allowances. Many insurers use software that can model these costs, and a local agent familiar with your market can help you calibrate the right limit. In our guide on homeowners insurance cost in Arkansas, we explain how regional factors affect premiums, and the same logic applies to code upgrade limits: older housing stock and stricter codes often mean higher exposure.
Why Older Homes Face a Bigger Code Upgrade Gap
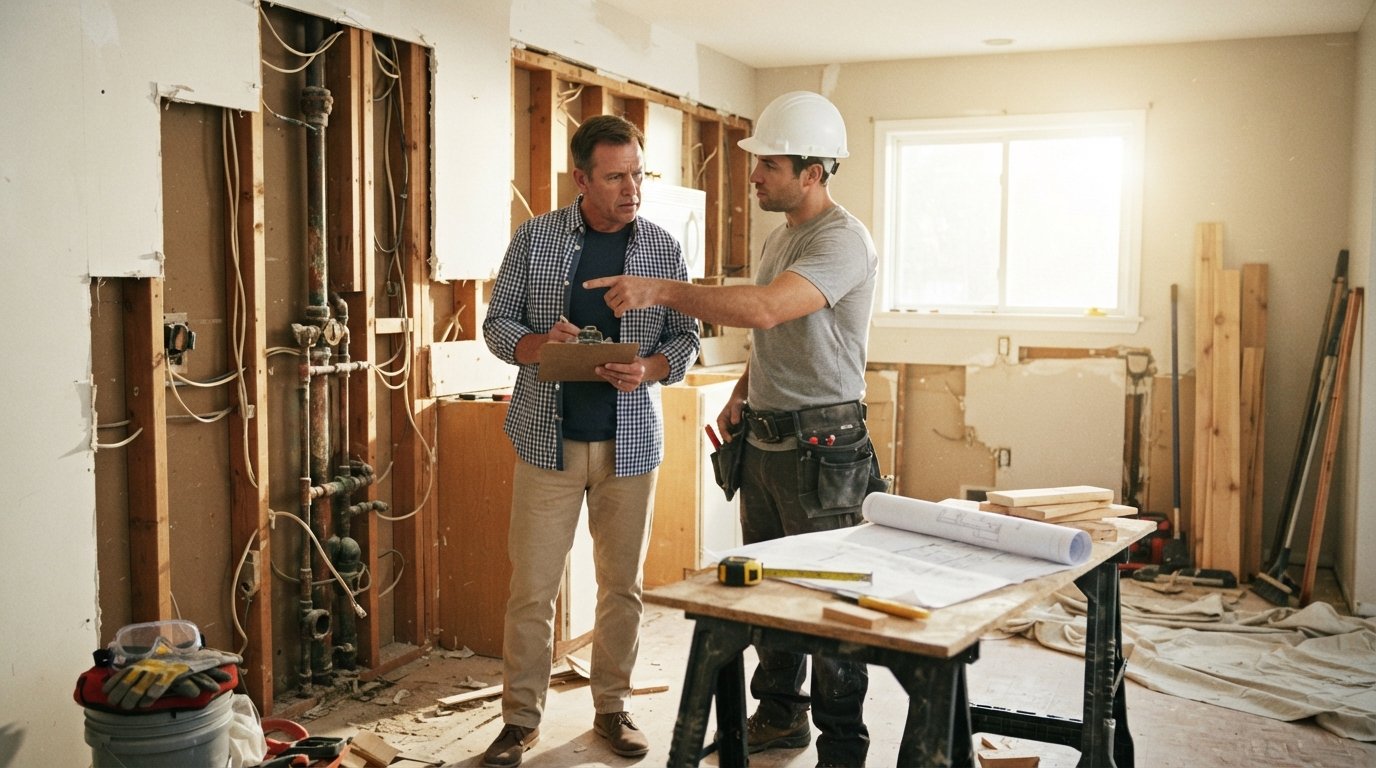
Homes built before the 1980s were constructed under building codes that look nothing like today's standards. Electrical systems may lack grounding or ground fault protection, plumbing may use materials now banned, and structural connections may not be designed for modern wind or seismic loads. When a partial loss occurs, the building department may require that the entire affected system be brought up to code, not just the damaged portion. This is where the gap between what your policy pays and what the rebuild actually costs becomes dangerous.
Consider a kitchen fire in a 1950s home. The fire damages cabinets and wiring in one wall. When you pull a permit to repair, the inspector requires that the entire kitchen circuit be upgraded to current code, including a new panel, arc-fault breakers, and grounded outlets. The visible fire damage might cost $30,000 to repair, but the code-required electrical work could add another $15,000 or more. If your ordinance or law limit is 10 percent of a $300,000 dwelling limit, you have $30,000 available, which may cover the upgrade but leaves nothing for other code triggers like smoke detectors or egress windows.
Older homes also present a higher risk of a total loss because they may not meet current fire separation or structural requirements. If a total loss occurs, the entire home must be rebuilt to current code, and the cost difference between like-for-like replacement and code-compliant construction can be enormous. In some jurisdictions, you may not even be allowed to rebuild the same footprint if the home is now considered a nonconforming use. These scenarios are exactly why homeowners with older properties should treat the default ordinance or law limit as a starting point, not a ceiling.
Requesting an Endorsement With Higher Limits
If your home is older, has had significant renovations, or is located in an area with aggressive code enforcement, you should consider buying a higher ordinance or law limit by endorsement. An endorsement is a policy add-on that changes the terms of your coverage, and in this case it increases the sublimit for code upgrades. Some insurers offer limits of 25, 50, or even 100 percent of the dwelling limit, though availability varies by carrier and state.
The process is straightforward but requires some preparation. Start by gathering the following:
- Your current policy declarations page: Note the dwelling limit and the ordinance or law percentage.
- A recent replacement cost estimate: Ask your agent for a new estimate that reflects current construction costs and code requirements.
- Documentation of renovations and permits: If you have updated electrical, plumbing, or structural systems, have the permits and inspection records ready. Insurers may offer better terms when they see that major systems have already been modernized.
- Local code summary: A brief description from your building department about what upgrades are typically required after a loss can help justify the higher limit.
Once you have this information, ask your agent to quote an endorsement with a higher limit. Compare the additional premium to the potential out-of-pocket cost of a code upgrade. In many cases, the cost of increasing your limit from 10 to 25 percent is modest relative to the protection it provides. If your current insurer does not offer a sufficient limit, it may be worth shopping around. You can use comparison tools and educational resources to evaluate options, and sites like QuoteComparison can help you see how different carriers approach code upgrade coverage.
Keep in mind that increasing your ordinance or law limit does not change your dwelling limit; it simply makes more of that limit available for code-related costs. Some policies structure the endorsement as additional insurance, which is even better because it does not erode your dwelling coverage. Read the endorsement language carefully to confirm whether the limit is additional or included.
Documenting Renovation and Permitting History Before a Claim
One of the most practical steps you can take to protect yourself is to maintain thorough records of all renovations, permits, and inspections. When a claim occurs, the adjuster will need to determine what was damaged and what code upgrades are required. If you can show that certain systems were already updated and permitted, you may reduce the scope of required upgrades and preserve your ordinance or law limit for other items. Conversely, if you have unpermitted work, the insurer may deny coverage for that portion or require it to be brought up to code at your expense.
Create a home file that includes permits, contractor invoices, inspection reports, and photographs of major systems before and after renovation. Store digital copies in the cloud so they are accessible if your home is damaged. If you have not pulled permits for past work, consider consulting a contractor or code official about whether retroactive permits are possible; sometimes a simple inspection can bring unpermitted work into compliance and reduce your future exposure.
It also helps to review your policy annually with your agent, especially after any renovation. Adding a room, upgrading a kitchen, or finishing a basement changes your replacement cost and may trigger new code requirements. Keeping your dwelling limit and ordinance or law limit in sync with your home's actual condition is the best way to avoid a coverage gap. For a broader look at how insurance costs vary by region, you can explore resources that break down state-specific factors, and the same attention to local codes applies to your code upgrade protection.
Key Takeaways and Next Steps
Does homeowners insurance cover ordinance or law upgrades? Yes, but typically only up to a limited sublimit that may not match the real cost of bringing an older home up to code. The default 10 percent limit is often insufficient for homes with outdated electrical, plumbing, or structural systems, and the gap can become a financial crisis after a covered loss. By understanding how the coverage works, estimating your exposure, and requesting a higher endorsement when needed, you can close that gap and rebuild with confidence.
Take action now: pull out your policy, find the ordinance or law section, and check the percentage. If it is 10 percent and your home is more than a few decades old, call your agent and ask about increasing the limit. Document your renovations, keep your permits handy, and review your coverage annually. A few minutes of preparation today can prevent a devastating surprise tomorrow.