Flood Insurance vs Homeowners Insurance: Coverage Gap Explained
Understand the flood insurance vs homeowners insurance coverage gap and protect your home. Call (833)-214-6397 for expert guidance.
By Callum Reeves
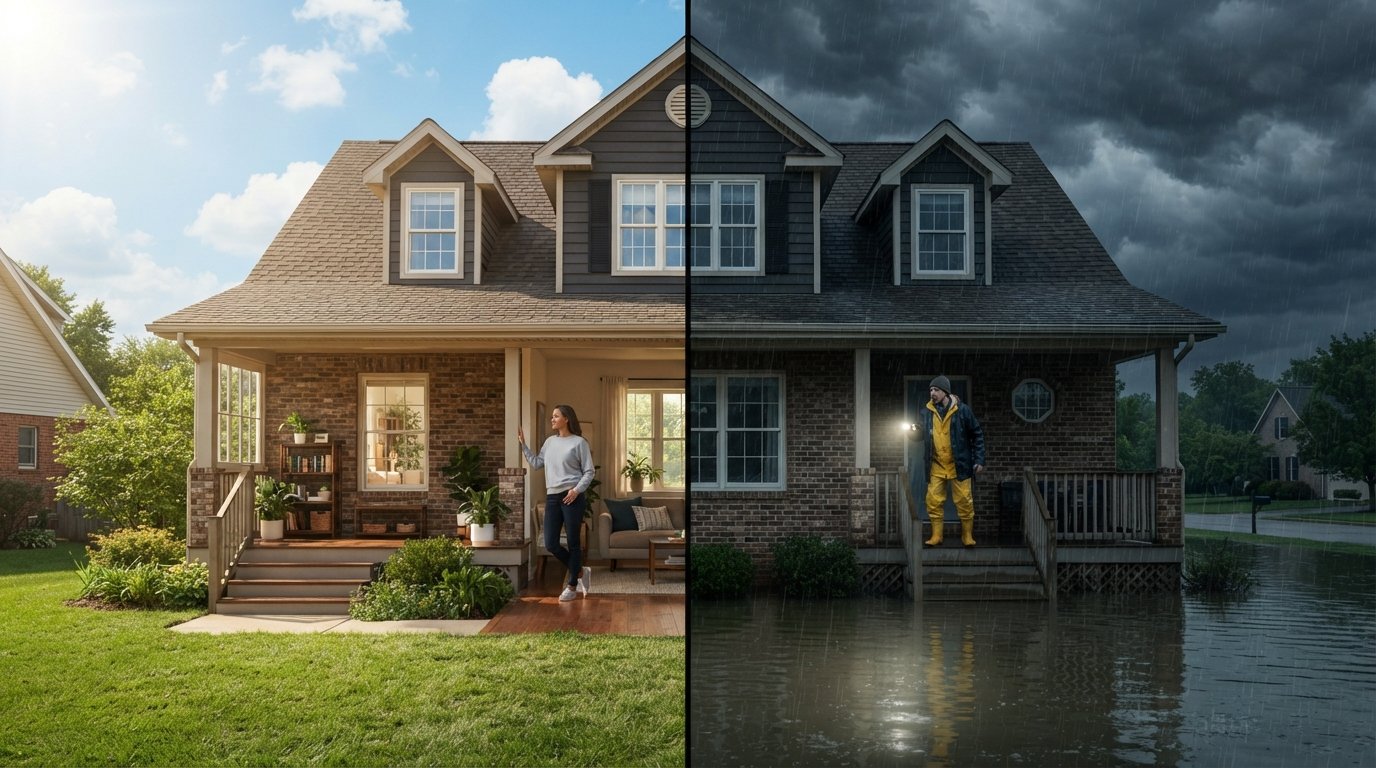
Your homeowners policy may protect your home from fire, wind, and theft, but it almost certainly will not pay for damage caused by a flood. That single exclusion has surprised thousands of Americans after hurricanes, heavy rains, and even minor storm surges. Understanding the flood insurance vs homeowners insurance coverage gap explained here can mean the difference between a $10,000 repair bill and a financial recovery. This article breaks down what each policy covers, why the gap exists, how to check your flood risk, and what steps to take before the next storm.
What Homeowners Insurance Covers and What It Excludes
A standard homeowners insurance policy (HO-3 or similar) is designed to protect your dwelling and personal property against specific perils listed in the contract. Common covered perils include fire, lightning, windstorm, hail, vandalism, and theft. If a falling tree damages your roof during a windstorm, your policy typically pays to repair the roof and remove the tree. If a burst pipe soaks your floors, that water damage is usually covered because it resulted from an accidental discharge inside the home.
However, homeowners policies specifically exclude water damage from external sources. Flood, surface water, waves, tidal water, and spray from a body of water are almost always excluded. Even water that seeps through a foundation or backs up from a storm drain may be excluded unless you purchased a separate endorsement. The key distinction is the source of the water: internal plumbing failures are often covered, while external flooding is not.
This exclusion is not a loophole; it is a fundamental part of how homeowners insurance is priced. Insurers calculate risk based on historical data for common perils. Flood risk varies dramatically by location, and including it in every policy would make homeowners insurance unaffordable for everyone. Instead, flood coverage is separated so that only those in high-risk areas pay for it.
Why Flood Is Treated as a Separate Peril
Flood is a catastrophic, widespread event. A single river overflowing can damage thousands of homes simultaneously, creating losses that far exceed what a typical homeowners insurer can absorb. Private insurers largely withdrew from flood coverage in the mid-20th century after repeated devastating floods. In response, the federal government created the National Flood Insurance Program (NFIP) in 1968 to make flood insurance available and to encourage community floodplain management.
Today, the NFIP remains the primary source of flood insurance for most Americans, though some private insurers now offer alternatives. The separation serves two purposes: it keeps homeowners insurance premiums lower for everyone, and it allows flood risk to be priced according to actual exposure. Homes in high-risk flood zones pay more, while those in low-risk areas pay less. This risk-based approach is why lenders require flood insurance for properties in Special Flood Hazard Areas (SFHAs).
It is also why you cannot simply add a flood endorsement to your homeowners policy. Flood is a distinct policy with its own deductible, coverage limits, and waiting period. Understanding this separation is the first step in closing the coverage gap.
How to Check Your Flood Zone and Lender Requirements
Before you buy or renew coverage, find out your property's flood zone. The Federal Emergency Management Agency (FEMA) publishes flood insurance rate maps (FIRMs) that classify land into zones. Zones starting with A or V are high-risk (SFHAs), while zones B, C, and X are moderate- to low-risk. You can check your zone through FEMA's Flood Map Service Center or ask your insurance agent.
If you have a federally backed mortgage (FHA, VA, Fannie Mae, Freddie Mac), your lender must require flood insurance if your home is in an SFHA. Lenders typically require coverage equal to the lesser of your outstanding loan balance or the maximum NFIP limit ($250,000 for the building). Even if you are not in an SFHA, your lender may still require flood insurance if the property is near a flood-prone area.
Do not assume that being outside a high-risk zone means you are safe. Roughly 25% of NFIP claims come from properties outside SFHAs. Low-risk does not mean no risk. If you are uninsured and a flood occurs, you will bear the full cost of repairs.
Waiting Periods and Key Differences Between Flood and Homeowners Policies
One of the most critical differences is the waiting period. A new flood insurance policy typically takes effect 30 days after purchase. If you buy flood insurance the day before a storm, you will not be covered. Homeowners policies generally have no such waiting period for new coverage, though some perils may have separate rules. This 30-day wait is why experts advise buying flood insurance well before hurricane season or heavy rain events.
Another difference is the claims process. Flood claims are handled separately from homeowners claims, often through the NFIP's Direct Servicing Agent or a private flood insurer. You will need to document damage extensively, including photos and receipts. Homeowners claims may be more straightforward for covered perils, but flood claims can take longer due to the volume of claims after a major event.
Coverage limits also differ. NFIP building coverage maxes out at $250,000 for residential properties, and contents coverage at $100,000. Private flood insurers may offer higher limits. Homeowners policies typically provide dwelling coverage equal to the replacement cost of your home, which could be much higher. If your home is expensive to rebuild, you may need excess flood coverage.
To compare homeowners insurance options and understand how flood fits into your overall protection, you can use resources like QuoteComparison to see side-by-side quotes from multiple insurers. Also, for a deeper look at how home insurance costs vary by state, see our guide on homeowners insurance cost in Arkansas, which illustrates regional pricing factors that can affect your overall insurance budget.
Frequently Asked Questions
Does homeowners insurance ever cover flooding?
Only in very limited circumstances, such as a burst pipe inside the home. Flood from external sources is excluded. You need a separate flood policy.
Is flood insurance required by law?
Federal law requires flood insurance for properties in SFHAs that have federally backed mortgages. Otherwise, it is optional but highly recommended.
Can I buy flood insurance from a private insurer?
Yes, private flood insurance is available and may offer higher limits or broader coverage. However, NFIP is still the most common option.
How much does flood insurance cost?
Premiums vary by flood zone, elevation, and coverage amount. The average NFIP premium is around $700 per year, but high-risk zones can pay much more.
Closing the flood insurance vs homeowners insurance coverage gap starts with awareness. Check your flood zone, talk to your agent about a separate flood policy, and do not wait until a storm is forecast. The 30-day waiting period means procrastination can leave you exposed. For personalized help comparing homeowners and flood insurance options, call (833)-214-6397 to speak with a licensed agent who can guide you through the process.