Grundy Insurance Classic Car Coverage: What to Know
Grundy insurance classic car coverage uses agreed value to protect your collector vehicle. Call (833)-214-6397 to compare specialty quotes and avoid underinsurance.
By Ethan Carter
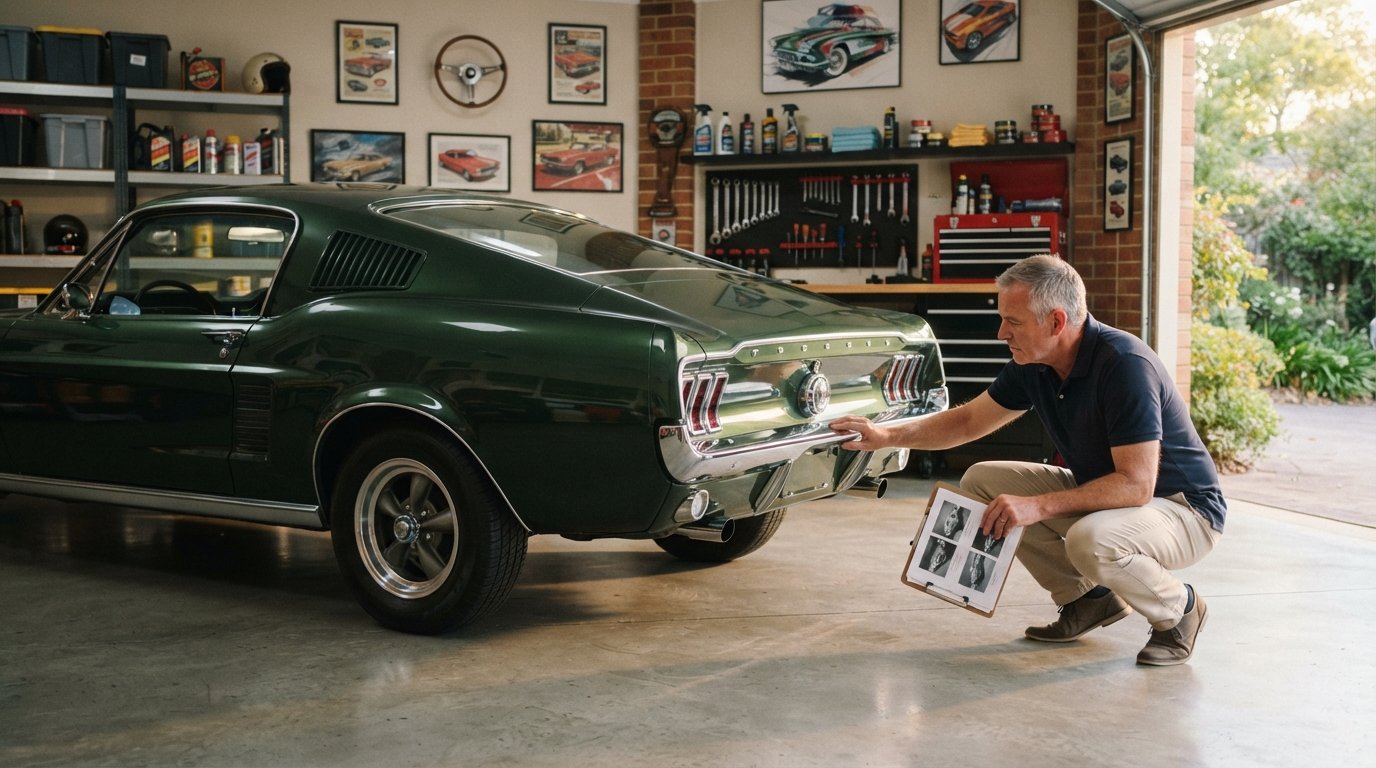
Collector vehicles are not just transportation; they are rolling investments, family heirlooms, and weekend passions. Standard auto policies often treat a 1967 Mustang the same as a daily commuter, which can leave you underinsured when a repair bill for a rare carburetor arrives. Grundy Insurance built its reputation on a different approach: agreed value coverage, unlimited mileage for hobby use, and a claims process that understands restoration timelines. This guide breaks down how Grundy insurance classic car insurance works, where it fits, and how to decide if it is right for your garage.
What Grundy Insurance Classic Car Insurance Actually Covers
Grundy is a specialty carrier focused on collector vehicles, not a generalist insurer that adds a classic car rider as an afterthought. The core product is an agreed value policy. You and the insurer settle on a dollar figure before the policy starts, based on photos, appraisals, and documentation. If the car is totaled, you receive that agreed amount, not a depreciated market estimate. That distinction matters enormously for vehicles with restoration receipts that exceed book value.
Beyond agreed value, Grundy policies typically include:
- Unlimited mileage for hobby and pleasure driving (commuting and commercial use are excluded)
- Coverage for spare parts and memorabilia, often up to a set limit
- Automatic coverage for newly acquired collector vehicles, usually for a short window
- Inflation guard, which adjusts the agreed value annually without a new appraisal
- Roadside assistance and flatbed towing tailored to low-clearance or non-running vehicles
That list is not identical across every state or vehicle type. A numbers-matching muscle car, a modified street rod, and a modern exotic each fall under different underwriting rules. The common thread is that Grundy insurance classic car insurance is designed for vehicles driven less than daily and kept in secure storage. If you use your classic for DoorDash runs, this is not the policy for you.
Agreed Value vs. Actual Cash Value: The Difference That Matters
Most standard auto policies pay actual cash value (ACV) after a total loss. ACV is replacement cost minus depreciation, and for collector cars the depreciation math is brutal because the market does not track a 1972 BMW 2002 the way it tracks a 2022 Camry. A standard insurer may offer a fraction of what a restoration cost, and you absorb the gap.
Agreed value flips that equation. The policy states a specific number, and both parties accept it as the settlement basis. That is why Grundy insurance classic car insurance appeals to owners who have receipts for paint, engine work, and NOS parts. The agreed value should reflect what it would cost to buy a comparable car today, not what you paid ten years ago. Grundy's inflation guard helps, but you should still review the value every few years, especially after a major restoration or a market spike in your model.
One practical note: agreed value is not a blank check. Underwriters review photos and documentation, and they may push back on a value that looks speculative. Accuracy protects you at claim time. Overstating value can create disputes; understating it leaves money on the table.
Eligibility and Usage Rules You Should Read Before Buying
Grundy insurance classic car insurance is not available for every vehicle or every driver. Eligibility generally hinges on three factors: the vehicle, the storage, and the usage.
- Vehicle type: Collector cars, classics, antiques, street rods, modified vehicles, and exotics typically qualify. Daily drivers and work trucks do not.
- Storage: A locked garage is usually required. Carports and open driveways are often disqualifying because theft and weather risk rise sharply.
- Usage: Pleasure driving, club events, car shows, and occasional errands are fine. Commuting, track use, and commercial hauling are not.
Drivers also matter. Grundy generally requires a clean driving record and may ask for household driving information. A DUI or a cluster of at-fault accidents can push you to a standard carrier or a surplus lines market. If you are shopping for a first classic and have a young driver in the house, call before assuming the car can be added to the policy.
These rules exist because collector policies price risk differently. The carrier assumes the car spends most of its life parked and protected, which is why premiums are often lower than a daily driver policy for the same vehicle value. Break the usage assumptions and the pricing model breaks with it.
How Grundy Compares With Other Collector Car Insurers
The collector car insurance market has a handful of well-known names, and each has a slightly different personality. Grundy is often praised for flexible mileage and a straightforward agreed value process. Hagerty is known for its enthusiast community, driving events, and valuation tools. American Modern and Safeco's collector programs serve specific niches, including modified vehicles and younger drivers.
Here is a practical comparison framework:
- Mileage: Grundy generally offers unlimited hobby mileage; some competitors cap annual miles.
- Agreed value: All major collector carriers offer it, but documentation requirements and inflation adjustments vary.
- Claims handling: Ask whether the carrier uses specialty adjusters who understand restoration shops and parts sourcing.
- Bundling: If you also need home or daily driver coverage, check whether bundling is available or whether you will maintain separate policies.
For a broader look at how auto rates behave in dense urban markets, our guide on affordable auto insurance in San Francisco illustrates why ZIP code and usage patterns drive pricing. The same logic applies to collector cars: where and how the vehicle is stored changes the quote dramatically.
Cost Factors: What Drives Your Grundy Premium
Collector car premiums are not random. Underwriters weigh a predictable set of variables, and understanding them helps you shop intelligently.
- Agreed value: The higher the stated value, the higher the premium, though the rate per dollar of coverage often improves at higher values.
- Vehicle type: Rare parts and exotic materials increase repair complexity and cost.
- Location: Theft rates, weather risk, and garage security vary by region.
- Usage: Limited pleasure use prices lower than broad hobby use, even within collector programs.
- Deductibles: A higher deductible lowers premium but shifts more risk to you.
Because Grundy insurance classic car insurance is specialty coverage, you should not assume your current agent's quote is competitive. Get at least two collector-specific quotes and compare the agreed value language, not just the bottom line. A cheaper policy with a vague valuation clause can cost far more at claim time.
Claims: What to Expect When Something Goes Wrong
The claim experience is where collector policies earn their reputation. Grundy's process generally starts with a call and photos, followed by an adjuster who understands that a correct repair may require a specialist shop and a waiting period for parts. Total losses are settled at the agreed value, minus deductible, with the option to retain the salvage in some cases.
A few habits make claims smoother:
- Keep current photos of all sides, the interior, the engine bay, and the odometer.
- Store receipts for restoration and maintenance in one folder, digital or physical.
- Update the agreed value after major work or market shifts.
- Report incidents promptly, even minor ones, to preserve options.
Disagreements happen, but they are less common when documentation is strong. If you are comparing the policy to a standard auto policy, read the valuation clause side by side. The difference in settlement language is usually the deciding factor.
Is Grundy the Right Fit for Your Garage?
Grundy insurance classic car insurance fits owners who treat their vehicles as collectibles, not commuters. If you have a garage, drive for pleasure, and want a settlement number you can point to before a loss, it is a strong candidate. If you drive the car daily, park on the street, or plan to use it for hire, a standard or commercial policy is the better path.
It also helps to think about your whole insurance picture. Collector cars often sit alongside daily drivers, a home, and health or life coverage. A resource like InsuranceAdvisers can help you understand how different policy types fit together, while specialty carriers handle the collector vehicle itself. The goal is a portfolio where each vehicle is insured on the basis that matches its use and value.
Before you buy, confirm three things in writing: the agreed value, the usage restrictions, and the storage requirements. Those three details determine whether the policy performs when you need it. Everything else, from roadside assistance to spare parts coverage, is a bonus on top of that foundation.
Collector car ownership is a long game. Paint fades, markets shift, and parts get harder to find. A policy built for that reality is worth the extra phone call. Start with a documented value, ask hard questions about usage, and compare at least two specialty quotes before you sign.