How Vehicle Age and Mileage Affect Car Insurance Rates
Vehicle age and mileage shape premiums through depreciation and risk. Call (833)-214-6397 to compare quotes and avoid overpaying for coverage.
By Adrian Foxe
Your car's age and the miles on its odometer are not just numbers on a title or dashboard. They are two of the most powerful signals insurers use to predict risk, and they can swing your premium by hundreds of dollars a year. Whether you drive a brand-new sedan or a ten-year-old commuter, understanding how vehicle age and mileage affect car insurance rates puts you in a stronger position to shop smart, adjust coverage, and avoid paying for protection that no longer makes financial sense.
The Core Logic: Why Insurers Care About Age and Mileage
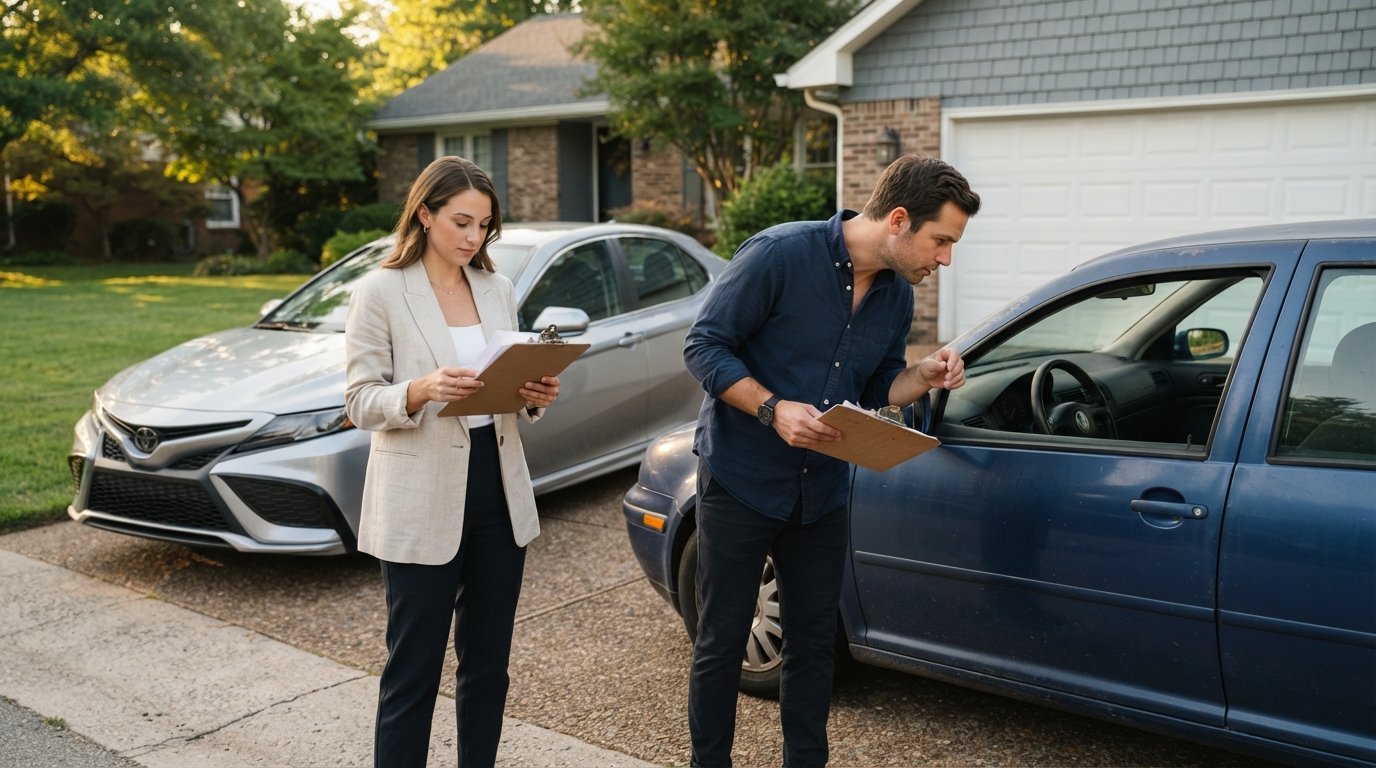
Auto insurance pricing is built on probability. Insurers want to know how likely you are to file a claim and how much that claim might cost. Vehicle age and mileage feed directly into both sides of that equation. A newer car costs more to repair or replace, so physical damage claims are pricier. An older car is worth less, which caps the payout on a total loss, but it may also lack modern safety features that reduce injury risk. Mileage works in parallel: the more you drive, the more exposure you have to accidents, theft, and weather events. According to the Insurance Information Institute, annual mileage is a standard rating factor in most states, and insurers often group drivers into low, medium, and high-mileage buckets when setting rates.
These two factors do not act in isolation. A 12-year-old car with 150,000 miles presents a very different risk profile than a 3-year-old car with 20,000 miles, and insurers price accordingly. The interplay between depreciation, repair costs, and crash frequency is what makes this topic more nuanced than a simple "older equals cheaper" or "newer equals expensive" rule. In the sections below, we break down each factor and show how to use that knowledge when you compare quotes and choose coverage limits.
How Vehicle Age Affects Car Insurance Rates
Age influences premiums through several channels. The most obvious is vehicle value. New cars are worth more, so if they are totaled or stolen, the insurer pays more. That higher potential payout translates into higher premiums for comprehensive and collision coverage. As a car depreciates, the maximum payout shrinks, and the physical damage portion of your premium typically declines. However, the relationship is not perfectly linear. At some point, an older car becomes so inexpensive that insurers may not offer collision or comprehensive coverage at all, or they may require a higher deductible to make the policy worthwhile.
Another channel is safety and repair technology. Newer vehicles often have advanced driver assistance systems, backup cameras, and stronger crash structures that reduce the severity of claims. Insurers recognize this and may offer discounts for vehicles with certain safety features. Older vehicles may lack these features, which can push injury and collision claim costs higher. At the same time, older cars can be cheaper to repair in minor collisions because parts are more available and labor procedures are simpler. Insurers weigh these competing effects when they assign a rate class to your vehicle.
Depreciation and the Value of Comprehensive and Collision
Comprehensive and collision coverage are priced largely on the vehicle's actual cash value (ACV), which is what it would cost to replace the car minus depreciation. A new car might lose 20 percent of its value in the first year, and 10 to 15 percent per year after that. As the ACV drops, the maximum claim payout drops, and the premium for these coverages usually follows. This is why a 10-year-old car often costs much less to insure for physical damage than a brand-new one, even with identical drivers and limits.
But there is a catch: the cost of repairs does not depreciate at the same rate as the car's value. A bumper replacement on a 2012 model may cost nearly as much as on a 2020 model, while the older car's total value is far lower. When repair costs approach or exceed the car's ACV, insurers may declare a total loss for relatively minor damage. That dynamic can make comprehensive and collision coverage on older cars feel like poor value, because you are paying premiums for coverage that may only pay out a small amount relative to your deductible. Understanding this trade-off is central to deciding when to drop collision on an older vehicle.
Rate Classes and Vehicle Value Assignment
Insurers do not price every car individually. They group vehicles into rate classes based on make, model, body style, engine size, safety features, theft rates, and repair costs. A compact sedan with a strong safety record and inexpensive parts might land in a low rate class, while a sports car or a luxury SUV with costly sensors and special materials lands in a high one. Vehicle age is one input into that classification, but it is not the only one. A 5-year-old economy car may cost less to insure than a 5-year-old luxury sedan because the repair and theft profiles differ dramatically.
When you request quotes, insurers will ask for the VIN, which they use to decode the vehicle's attributes and assign the correct rate class. This is why two drivers with the same age, record, and location can receive very different quotes for different vehicles. It also explains why shopping around matters: different insurers weight vehicle age and value differently, so the same car may be a bargain with one carrier and a premium burden with another. If you want to see how these factors play out in a specific market, our Sacramento auto insurance rates guide breaks down local pricing patterns and savings tactics.
How Mileage Affects Car Insurance Rates
Mileage is a proxy for exposure. Every mile you drive is a chance to be in an accident, and insurers price that risk into your premium. Most carriers ask for your estimated annual mileage and may verify it through odometer readings, claims history, or telematics programs. Low-mileage drivers (often defined as under 7,500 miles per year) frequently qualify for discounts, while high-mileage drivers (15,000 miles or more) may see surcharges. The exact thresholds vary by insurer and state, but the principle is consistent: more time on the road means more risk.
Mileage also interacts with vehicle age. A 5-year-old car with 100,000 miles has been driven hard and may be closer to major repairs, which can affect both claims frequency and the insurer's willingness to offer physical damage coverage. Conversely, a 10-year-old car with 40,000 miles may be a low-risk garage queen that qualifies for low-mileage discounts. Insurers look at both numbers together to build a fuller picture of how the vehicle is used and how much exposure it represents.
Annual Mileage, Commuting, and Usage-Based Insurance
How you use the car matters as much as how far you drive. A vehicle used only for pleasure driving may qualify for lower rates than one used for daily commuting, even if annual mileage is similar. Commuting during rush hour increases exposure to traffic density and accident frequency. Insurers often ask about annual mileage, one-way commute distance, and whether the car is used for business. These details help them assign a usage rating that can move your premium up or down by 5 to 15 percent or more.
Usage-based insurance programs, sometimes called telematics or pay-per-mile, take this a step further. They track actual driving behavior, including miles driven, time of day, braking, and acceleration, and adjust premiums based on that data. Safe, low-mileage drivers can save meaningfully, while high-mileage or aggressive drivers may pay more. If you drive fewer than 10,000 miles per year and want to explore these options, it is worth asking each insurer whether they offer a telematics discount and how it is calculated. Just be aware that these programs collect driving data, so privacy preferences matter.
When Dropping Collision on an Older Car Makes Sense
The decision to drop collision coverage is one of the most practical applications of understanding vehicle age and value. Collision coverage pays to repair or replace your car after an accident you cause, up to its actual cash value. As a car ages, that ACV falls, and the premium for collision coverage may not justify the potential payout. A common rule of thumb is to consider dropping collision when the annual premium plus your deductible approaches or exceeds 10 percent of the car's ACV. For example, if your car is worth $4,000 and you pay $400 per year for collision with a $500 deductible, you are paying 10 percent of the car's value each year for coverage that maxes out at $3,500 after the deductible.
There is no universal cutoff, but a few questions can guide the decision. First, how much would a total loss hurt financially? If you can easily replace the car with savings, collision coverage may be optional. Second, what is your risk tolerance? Dropping collision means you absorb the full cost of repairs or replacement if you cause an accident. Third, do you have a loan or lease? Lenders and lessors typically require collision and comprehensive coverage, so you cannot drop it until the vehicle is paid off. Finally, consider state requirements: liability coverage is mandatory in most states, but collision and comprehensive are optional.
Before making a change, run the numbers with your actual premium and deductible. Ask your insurer for the premium breakdown by coverage so you can see exactly what collision costs. If the math favors dropping it, confirm that you have an emergency fund to cover repairs or replacement. And remember that dropping collision does not reduce your liability exposure; you still need adequate liability limits to protect your assets. For a broader look at how to compare policies and connect with licensed agents, resources like InsuranceAdvisers offer educational guides and comparison tools for U.S. consumers.
Steps to Compare Quotes for the Same Coverage Limits
Because insurers weight vehicle age and mileage differently, the only way to know which carrier offers the best value is to compare quotes with identical coverage limits. Start by gathering your vehicle information (VIN, make, model, year, and current mileage), your driving record, and your desired coverage levels. Decide on liability limits, deductibles for comprehensive and collision, and whether you need uninsured/underinsured motorist coverage. Keeping these variables constant across quotes ensures you are comparing apples to apples.
Next, request quotes from multiple insurers and pay attention to how each one handles vehicle age and mileage. Some may offer low-mileage discounts, while others may surcharge high-mileage vehicles more aggressively. Ask about telematics programs and safety feature discounts. Review the premium breakdown by coverage so you can see where the differences come from. Finally, confirm that the quote reflects your actual usage, not a generic estimate, and ask about any verification requirements. A structured approach looks like this:
- List your must-have coverage limits and deductibles.
- Gather VIN, mileage, and usage details for each vehicle.
- Request quotes from at least three insurers with identical limits.
- Compare premium breakdowns by coverage and ask about discounts.
- Confirm mileage verification and telematics terms before buying.
After you have quotes in hand, look beyond the bottom line. A cheaper premium with a carrier that is difficult to reach or slow to pay claims may cost you more in the long run. Check financial strength ratings and complaint ratios, and read the policy terms for exclusions that could affect older or high-mileage vehicles. If you are unsure how to interpret the differences, a licensed agent can walk you through the trade-offs without obligating you to buy.
Practical Takeaways for Drivers
Vehicle age and mileage affect car insurance rates through depreciation, repair costs, exposure, and rate classification. Newer cars usually cost more to insure for physical damage because they are worth more, while older cars cost less until the value drops so low that coverage no longer makes sense. Mileage increases exposure and premiums, but low-mileage and telematics discounts can offset that for careful drivers. The key is to match your coverage to your car's actual value and your driving habits, then shop with identical limits to find the carrier that prices your specific situation most favorably.
Review your policy annually, especially as your car ages or your commute changes. A coverage mix that made sense three years ago may be overpriced today. By understanding how age and mileage drive rates, you can make informed decisions, avoid surprise bills, and keep more money in your pocket while maintaining the protection you need.