Know Your Consumer Rights When Filing an Insurance Claim
Know your consumer rights when filing an insurance claim and avoid unfair denials. Call (833)-214-6397 for expert guidance.
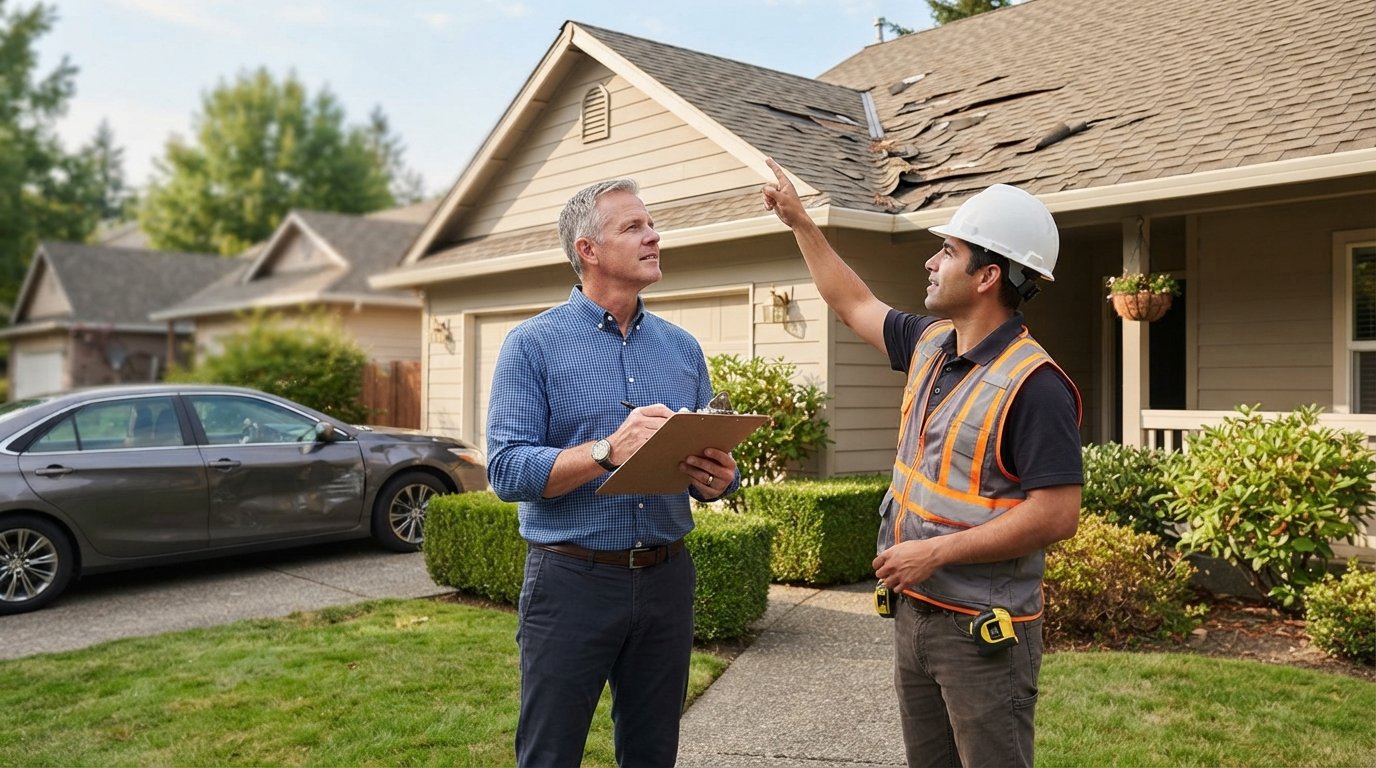
When a storm damages your roof, a fender bender sidelines your car, or a medical emergency lands you in the hospital, the last thing you want is a fight with your insurer. Yet every year, thousands of policyholders discover that filing a claim can feel like navigating a maze blindfolded. The good news: you are not powerless. State laws and regulations grant you specific consumer rights when filing an insurance claim, from timely responses to clear explanations and a path to appeal unfair decisions. Understanding these rights can mean the difference between a smooth payout and months of frustration.
This guide walks you through the protections you have, the timelines insurers must follow, and the steps to take if your claim goes off track. Whether you are dealing with auto, home, health, or any other type of coverage, knowing your rights helps you push back when necessary and get the settlement you deserve.
Your Fundamental Rights During the Claims Process
Insurance is a regulated industry, and every state has laws that dictate how insurers must handle claims. While specifics vary, certain core rights apply broadly. You have the right to a prompt and fair investigation of your claim, the right to receive a written explanation if your claim is denied, and the right to access your claim file. Insurers also cannot engage in deceptive practices or unreasonably delay payment.
These rights exist because insurance policies are contracts of good faith. When you pay premiums, you expect the insurer to honor its end of the bargain. If they fail to do so, you have legal recourse.
Right to Timely Acknowledgment and Decision
Most states impose deadlines for insurers to acknowledge receipt of a claim and to make a decision. For example, many states require acknowledgment within 10 to 15 days and a decision within 30 to 45 days after receiving proof of loss. Some states have shorter windows for certain types of claims, such as health insurance or property damage after a natural disaster. If the insurer needs more time, they must notify you in writing and explain why.
These timelines are not suggestions; they are legal requirements. If your insurer blows past them without justification, you may have grounds for a complaint with your state insurance department.
Right to Documentation and Explanation
You are entitled to a copy of your policy and any relevant claim documents. If your claim is denied or partially paid, the insurer must provide a written explanation that cites the specific policy provisions relied upon. This transparency allows you to challenge incorrect decisions. You also have the right to request updates on the status of your claim, and the insurer must respond within a reasonable time.
In some states, you can request your entire claim file, including adjuster notes and internal communications. This can be invaluable if you suspect the insurer mishandled your claim.
Right to Fair Settlement
Insurers must make a good-faith effort to settle claims promptly and fairly. That means they cannot lowball you with an offer that ignores policy limits or obvious damages. If you believe the settlement offer is unfair, you can negotiate, provide additional evidence, or invoke the appraisal clause in your policy (if available).
Remember that the first offer is rarely the final offer. Many policyholders leave money on the table simply because they accept the initial amount without question.
Typical Timelines Insurers Must Follow
Timelines vary by state and claim type, but here are common benchmarks you can expect. Always check your state's specific regulations, as some states have stricter rules.
- Acknowledgment of claim: 10 to 15 days after receipt.
- Decision on claim: 30 to 45 days after receiving proof of loss.
- Payment: 5 to 30 days after settlement agreement.
- Response to inquiries: 15 to 30 days.
For health insurance claims, federal rules under ERISA and the Affordable Care Act impose additional deadlines, often shorter than those for property claims. For example, urgent care claims must be decided within 72 hours. If your health insurer misses a deadline, you may have the right to external review.
Keep a calendar of these deadlines and document every interaction. If the insurer fails to meet them, you can use that as leverage in an appeal or complaint.
How to Document Your Claim from Day One
Proper documentation is your strongest weapon. Start by notifying your insurer as soon as possible after a loss. Provide a detailed description of what happened, including date, time, and location. Take photos and videos of the damage before you clean up or make temporary repairs. Keep receipts for any emergency repairs or expenses.
Create a claim diary. Log every phone call, email, and letter, including the name of the person you spoke with and what was discussed. Send written follow-ups to confirm verbal conversations. This record can be crucial if you need to escalate.
If your claim involves a third party (like a car accident), gather the other driver's insurance information and any police reports. For home claims, get estimates from licensed contractors. For health claims, keep all medical bills and explanation of benefits statements.
Remember that insurers may request additional documentation. Respond promptly and keep copies of everything you send. If you feel overwhelmed, consider hiring a public adjuster or attorney, but weigh the cost against the potential recovery.
Escalating Your Claim: Steps to Take When Insurer Delays or Denies
If your claim is delayed or denied and you believe the decision is wrong, you have several escalation options. Start by filing a formal appeal with the insurer. Follow the instructions in your denial letter, which should explain how to appeal. Submit a written appeal with supporting evidence, such as contractor estimates, medical records, or photos.
If the internal appeal fails, contact your state insurance department. Every state has a consumer services division that can mediate complaints and investigate insurer misconduct. Filing a complaint is free and often prompts insurers to take your claim more seriously. You can find your state department's contact information on the National Association of Insurance Commissioners (NAIC) website.
For health insurance, you may have the right to external review by an independent third party. For auto and home claims, you might invoke the appraisal clause or, in cases of bad faith, consult an attorney. If you are dealing with a denied auto claim specifically, our guide on how to appeal a denied auto insurance claim provides a step-by-step walkthrough.
Another powerful tool is comparison shopping. If your current insurer is giving you the runaround, you can explore alternatives. Resources like QuoteComparison allow you to compare quotes from multiple insurers, giving you leverage and a backup plan.
Bad Faith Practices: Recognize the Warning Signs
Bad faith is when an insurer unreasonably denies, delays, or undervalues a claim. It is not just poor customer service; it is a violation of the implied covenant of good faith and fair dealing. Common signs include:
- Refusing to pay a valid claim without a reasonable basis.
- Failing to investigate promptly or thoroughly.
- Making lowball offers that ignore policy limits.
- Misrepresenting policy provisions or facts.
- Failing to communicate or respond to inquiries.
If you suspect bad faith, document everything and consider filing a complaint with your state insurance department. In some states, you can sue for bad faith and recover damages beyond the policy limit, including emotional distress and attorney fees. However, bad faith claims are complex, so consult an attorney if you believe you have a case.
Keep in mind that insurers are businesses, and some may push the boundaries. Knowing your rights helps you stand your ground.
State Insurance Department: Your Consumer Advocate
Your state insurance department is a valuable resource. It regulates insurers, enforces consumer protection laws, and can help resolve disputes. You can file a complaint online or by phone. The department will typically contact the insurer and require a response. While the department cannot force the insurer to pay your claim, it can investigate and take disciplinary action if warranted.
Before filing a complaint, gather all relevant documents, including your policy, claim correspondence, and evidence of the loss. Be clear and concise about the issue. The department may also provide guidance on your rights and options.
Many state insurance departments publish consumer guides and claim tips. Take advantage of these free resources.
Special Considerations for Health Insurance Claims
Health insurance claims come with additional rights and complexities. Under the Affordable Care Act, most health plans must provide a plain-language summary of benefits and coverage, and they cannot rescind coverage except in cases of fraud. You have the right to appeal denials internally and externally. The external review process allows an independent organization to review your case, and the insurer must abide by the decision.
If your health insurer denies a claim as not medically necessary, you can request the clinical criteria used and appeal with supporting documentation from your doctor. For urgent claims, expedited appeals are available.
Medicare and Medicaid have their own appeals processes. If you are on Medicare, you can appeal to the plan and then to an independent reviewer. The process is outlined in your plan materials.
Practical Tips to Protect Your Rights
Being proactive can prevent many claim problems. Here are some practical steps:
- Read your policy. Understand what is covered, what is excluded, and what your responsibilities are.
- Report claims promptly. Delays can give the insurer grounds to deny.
- Keep detailed records. As mentioned, document everything.
- Ask questions. If something is unclear, ask the adjuster to explain in writing.
- Know your deadlines. Track the insurer's response times and follow up if they miss them.
By taking these steps, you put yourself in a stronger position to get a fair settlement.
Finally, remember that you are not alone. Consumer advocacy groups, attorneys, and state regulators are there to help. Do not hesitate to seek assistance if you feel your rights are being violated.
Understanding your consumer rights when filing an insurance claim empowers you to navigate the process with confidence. Whether you are dealing with a simple auto claim or a complex health appeal, knowing the rules and timelines helps you hold insurers accountable. And if you need to explore new coverage options, platforms like InsuranceShopping.com can connect you with licensed agents who can help you compare policies and find the right fit.