Life Insurance and Estate Planning: How a Policy Fits In
Life insurance and estate planning how a policy fits in can protect your heirs from probate and taxes. Call (833)-214-6397 for expert guidance.
By Aria Vellane
Most people buy life insurance to protect their families from the financial shock of a sudden loss. But that same policy can also be a powerful estate planning tool, or a costly source of unintended tax and probate complications if it is structured carelessly. Understanding life insurance and estate planning how a policy fits in is not just for the wealthy: it matters for anyone with a home, savings, a business, or a blended family. The decisions you make at purchase, and the beneficiary designations you update over time, determine whether your death benefit flows smoothly to the people you love or gets tangled in legal and tax battles.
This guide walks through the core mechanics: how beneficiary designations interact with wills and trusts, why an irrevocable life insurance trust may enter the picture, how death benefits are generally treated for estate taxes, and how to coordinate a policy with your other assets. Along the way, you will see where a simple term policy fits in an estate plan and where more advanced planning may be warranted. If you are still comparing coverage types, our breakdown of the top benefits of level term life insurance is a useful starting point for the foundation of many estate plans.
How Life Insurance Fits Into an Estate Plan
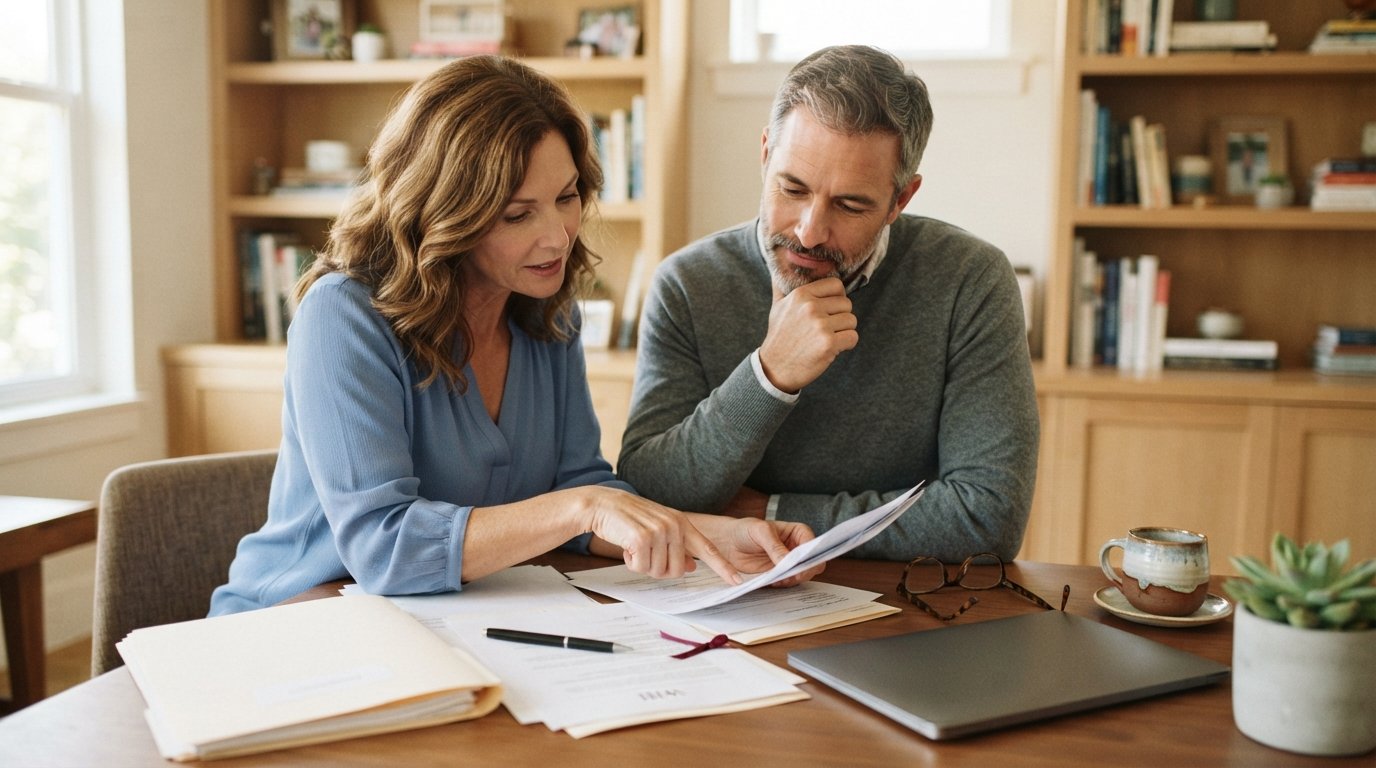
An estate plan is more than a will. It is a coordinated set of documents and designations that control what happens to your assets during your life (if you become incapacitated) and after death. Life insurance sits alongside your will, trusts, retirement accounts, and property deeds. The policy itself is a contract: it pays a death benefit to a named beneficiary when the insured dies, generally free of income tax to the recipient under current federal rules. That tax-free liquidity is why life insurance is often called the cornerstone of estate liquidity planning.
Consider a simple example. A single parent with two young children owns a $500,000 term policy. If she names her children as beneficiaries and dies unexpectedly, the proceeds pass outside probate, meaning the court-supervised process of validating a will does not control the payout. Her will handles the house and bank accounts, but the insurance money reaches the children quickly (through a guardian or trust if minors are involved). That speed and privacy are key advantages. Without a policy, the estate might have to sell assets to cover immediate expenses, or the children might wait months for probate to conclude.
The same logic applies to business owners, people with significant debt, and anyone who wants to equalize inheritances among children. For instance, a farmer who leaves the land to one child and wants to give the other child equivalent value can use life insurance to fund that equalizing bequest without forcing a sale of the farm. In all these cases, the policy is not separate from the estate plan; it is a funding mechanism that makes the rest of the plan work. The key is coordinating the beneficiary designation with the will and any trusts so that the money goes where you intend.
Beneficiary Designations: Trust Versus Individual
One of the most consequential choices in life insurance and estate planning how a policy fits in is who you name as beneficiary. You can name an individual (a spouse, child, parent, or friend), a trust, a charity, or your estate. Each choice has different legal and practical consequences, and the beneficiary designation generally overrides your will. If your will says your daughter should receive everything, but your policy names your ex-spouse as beneficiary, the ex-spouse typically gets the death benefit. That is why reviewing designations after major life events is essential.
Naming an individual is straightforward and common. It avoids probate and gives the beneficiary direct control of the funds. But it also creates risks: a minor child cannot legally manage money, so a court may appoint a guardian to oversee the funds until the child turns 18 or 21. A financially inexperienced adult beneficiary might spend the money quickly. And if you name your estate as beneficiary, the proceeds may become subject to probate and to the claims of your creditors. For these reasons, many estate planners recommend naming a trust as beneficiary when control and long-term management matter.
Naming a trust as beneficiary can provide structure. The trustee you choose manages the death benefit according to the trust's terms, which might specify that funds be used for education, health, or a staggered distribution at certain ages. A trust can also protect the money from a beneficiary's creditors or a future divorce. The tradeoff is complexity and cost: trusts must be drafted by an attorney, and the trustee has ongoing administrative duties. Here is a quick comparison to help you weigh the options:
- Individual beneficiary: Simple, avoids probate, but gives the beneficiary immediate control and offers no creditor protection.
- Trust beneficiary: Provides control, creditor protection, and professional management, but requires legal drafting and ongoing trustee administration.
- Estate beneficiary: May subject proceeds to probate and creditor claims, generally not recommended unless specific circumstances apply.
- Charity beneficiary: Can create an estate tax charitable deduction and fulfill philanthropic goals, but leaves less for heirs.
After reviewing these options, coordinate with your attorney and financial advisor. If you have young children, a trust is often the default choice. If your children are financially responsible adults, naming them directly may be simpler. If you are married, naming your spouse is common, but you should also name contingent beneficiaries in case your spouse predeceases you. And remember to update designations after divorce, remarriage, or the birth of a child; outdated forms are a leading cause of unintended outcomes.
Why an Irrevocable Life Insurance Trust May Be Used
An irrevocable life insurance trust, often called an ILIT, is a specialized estate planning tool designed to own a life insurance policy and manage its proceeds. When you create an ILIT, you transfer ownership of the policy to the trust (or the trust purchases the policy). Because the trust is irrevocable, you give up control over the policy, but the death benefit is generally excluded from your taxable estate. That exclusion is the primary reason wealthy families use ILITs: it can reduce estate tax exposure and provide liquidity to pay estate taxes without forcing the sale of family assets.
How does it work in practice? You, as grantor, create the trust and appoint a trustee (often a family member or professional). The trustee applies for and owns the policy on your life. You make annual gifts to the trust to cover premiums. Those gifts must be structured to qualify for the annual gift tax exclusion, typically by giving beneficiaries a limited right to withdraw the contributed amount for a short period (often called a Crummey power). If done correctly, the gifts are not taxable, and the death benefit passes to the trust beneficiaries free of estate tax. The trust can then lend money to your estate, buy assets from the estate, or make distributions to your heirs.
ILITs are not for everyone. They involve legal costs, ongoing administration, and a loss of flexibility: once the policy is in the trust, you generally cannot change your mind. They make the most sense when your estate is large enough that federal or state estate taxes are a concern, or when you want to protect a policy from creditors or a surviving spouse's remarriage. For many middle-income families, a simpler approach (such as naming a revocable living trust or individual beneficiaries) is sufficient. But if you expect your estate to exceed the federal estate tax exemption (which is set to change after 2025) or live in a state with its own estate tax, an ILIT is worth discussing with an estate planning attorney.
How Death Benefits Are Treated for Estate Taxes
Under current federal law, life insurance death benefits are generally included in your gross estate if you own the policy or possess any incidents of ownership at death. Incidents of ownership include the right to change beneficiaries, borrow against the policy, surrender it, or pledge it as collateral. If you own the policy outright, the full face amount is included in your estate for estate tax purposes, even though the proceeds are not subject to income tax. That inclusion can push a taxable estate over the exemption threshold and trigger estate tax on the margin.
However, there are important exceptions and planning techniques. If you irrevocably assign ownership of the policy to another person or to an ILIT at least three years before your death, the proceeds are generally excluded from your estate. That three-year lookback rule is designed to prevent deathbed transfers. If you die within three years of the transfer, the policy is pulled back into your estate. For married couples, the unlimited marital deduction allows unlimited transfers between spouses, so a policy owned by the surviving spouse may qualify for that deduction. But if the surviving spouse then dies owning the policy, the proceeds are included in his or her estate.
State estate taxes add another layer. Some states impose their own estate taxes with much lower thresholds than the federal government. In those states, a life insurance policy that is included in your estate could trigger state estate tax even if you are below the federal exemption. The interplay between federal and state rules is one reason why life insurance and estate planning how a policy fits in requires a personalized analysis, not a one-size-fits-all answer. The general treatment can be summarized as follows:
- Owned policy: Proceeds included in gross estate; potentially subject to federal and state estate tax.
- Policy transferred more than three years before death: Proceeds excluded from estate; no estate tax on the death benefit.
- Spousal transfer: Marital deduction may defer estate tax, but the policy remains in the survivor's estate.
- Charitable beneficiary: Estate tax charitable deduction may apply, reducing taxable estate.
After reading these rules, you can see that ownership is the pivot point. If estate tax is a concern, you may need to give up ownership of the policy, either by transferring it to an ILIT or to adult children. But giving up ownership also means giving up control. That tradeoff is central to estate planning with life insurance, and it should be made with professional advice. For most families, the federal estate tax exemption is high enough that estate tax is not a concern, but state taxes and future law changes can alter the calculus. Regular reviews are essential.
Coordinating Life Insurance With Other Estate Assets
Life insurance does not exist in a vacuum. To make your estate plan work, you need to coordinate the policy with your will, trusts, retirement accounts, and property. Consider a common scenario: a married couple with a house, two retirement accounts, and a $750,000 term policy. If the husband dies and the wife is the primary beneficiary of everything, the estate plan may be simple. But if they have children from prior marriages, they may want to ensure that the surviving spouse has income while ultimately preserving assets for the children. Life insurance can provide the liquidity to fund a trust that pays income to the spouse and distributes the remainder to the children. Without the policy, the estate might not have enough cash to fund that plan.
Another coordination issue is probate avoidance. Assets that pass by beneficiary designation (life insurance, retirement accounts) and assets held in trust avoid probate. Assets titled solely in your name with no beneficiary designation may go through probate. A well-designed estate plan uses a mix of these techniques to ensure that your affairs are settled quickly and privately. Life insurance is often used to pay debts, funeral costs, and estate settlement expenses so that your family does not have to sell inherited assets. It can also provide a source of liquidity if your estate consists mainly of real estate or a family business.
To coordinate effectively, follow these steps:
- Inventory your assets: List your life insurance policies, retirement accounts, bank accounts, real estate, and business interests, noting how each is titled and who the beneficiary is.
- Review beneficiary designations: Ensure they match your current wishes and align with your will and trusts.
- Assess liquidity needs: Estimate funeral costs, debts, estate taxes, and income replacement needs, then size your life insurance accordingly.
- Consider a trust: If you have minor children, a blended family, or a taxable estate, evaluate whether a revocable trust or ILIT is appropriate.
- Update regularly: Revisit your plan after major life events (marriage, divorce, birth, death, job change) and every few years to account for law changes.
After completing these steps, you will have a clearer picture of how your life insurance fits into your broader estate plan. Remember that beneficiary designations control the payout, not your will. If you name a trust as beneficiary, ensure the trust is properly drafted and funded. If you name individuals, make sure they know where to find the policy and how to file a claim. And if you own a policy that is included in your estate, consider whether transferring ownership or changing the beneficiary to a trust would better achieve your goals.
Finally, do not overlook the role of professional guidance. Estate planning attorneys, tax advisors, and insurance professionals each bring a different perspective. A licensed insurance agent can help you compare policy options and understand features like level term coverage, while an attorney can draft trusts and advise on tax implications. If you want to explore policy options and connect with providers, you can use QuoteComparison's insurance resources to compare quotes and find coverage that aligns with your estate planning goals.
Life insurance is a flexible tool that can protect your family, provide liquidity for your estate, and help you achieve your legacy goals. By understanding how beneficiary designations, trusts, and estate taxes interact, you can structure your policy to work in harmony with the rest of your plan. Review your choices regularly, and consult professionals when your situation changes. With careful planning, your life insurance policy will do exactly what you intend: provide security and peace of mind for the people you care about most.