Scheduled Personal Property Coverage for Jewelry and Valuable
Scheduled personal property coverage for jewelry and valuables closes the sublimit gap. Call (833)-214-6397 to compare options and protect your pieces.
By Theo Merrick
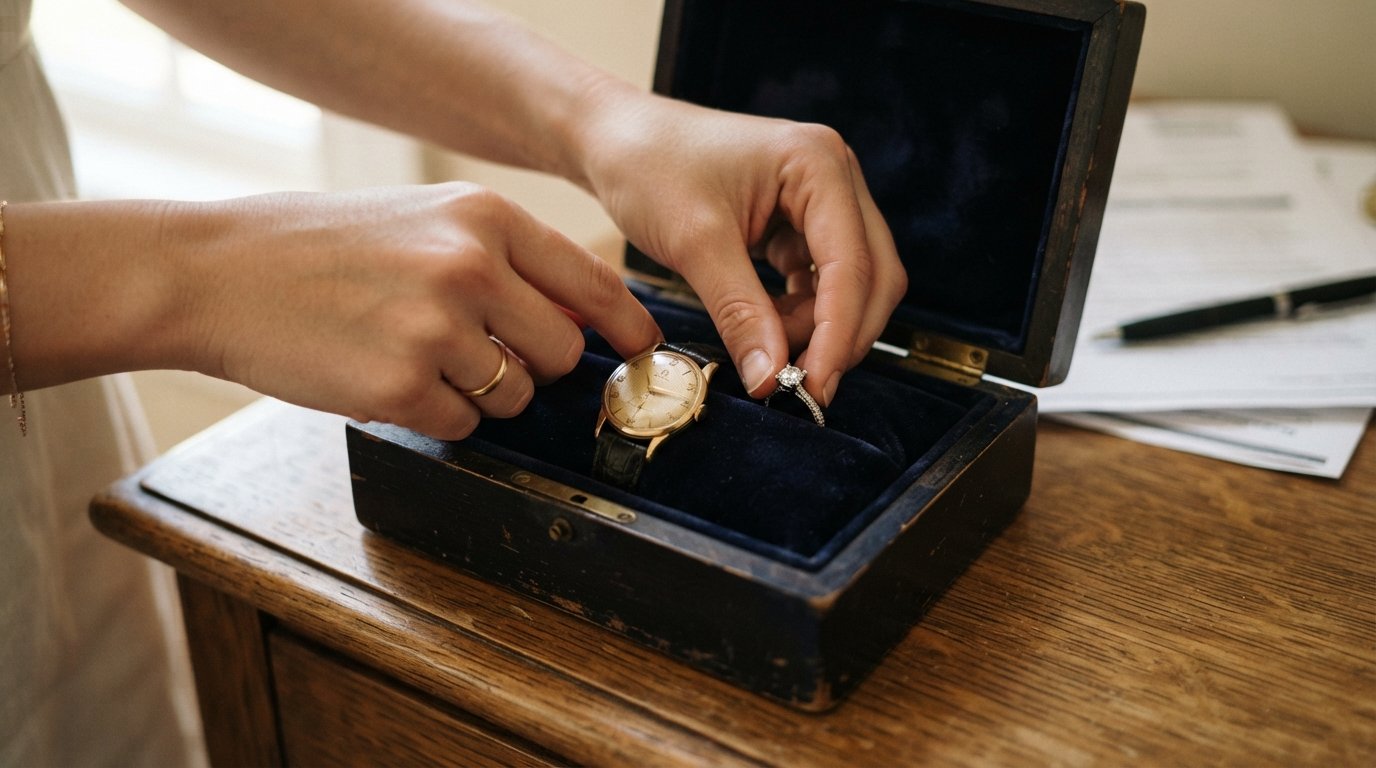
Your grandmother's diamond ring disappears from a hotel nightstand. A vintage watch slips off at the gym. A power surge fries your home theater system. You file a claim, expecting your homeowners policy to cover the loss, only to discover a sublimit of $1,500 for jewelry theft. That gap between what you own and what your policy pays is exactly why scheduled personal property coverage for jewelry and valuables exists. This guide explains how scheduling works, when it makes sense, and how to avoid the most common coverage traps.
Why Standard Homeowners Policies Cap Jewelry and Collectibles
Most homeowners insurance policies include personal property coverage that protects your belongings against covered perils like fire, theft, and vandalism. However, insurers know that high-value items such as jewelry, watches, furs, and fine art are both attractive to thieves and easy to overstate in a claim. To control risk, policies impose internal limits, often called sublimits, on specific categories of property.
Typical sublimits for theft of jewelry, watches, and furs range from $1,000 to $2,500 per category, regardless of how much total personal property coverage you carry. If you own a $10,000 engagement ring and a $5,000 watch, a standard policy might pay only a fraction of their value after a theft. Other categories with sublimits often include silverware, guns, money, and business property. These caps apply even if your overall personal property limit is $300,000 or more.
The result is a coverage gap that many homeowners do not discover until claim time. Scheduled personal property coverage for jewelry and valuables closes that gap by insuring specified items individually, typically without a deductible and often against broader risks than the base policy covers. Before you shop for a schedule, it helps to understand how your current policy handles personal property. Our home insurance personal property coverage guide explains the baseline protections and limits you already have.
How Scheduled Coverage Differs from a Floater
The terms "scheduled personal property" and "floater" are sometimes used interchangeably, but they describe slightly different approaches. A scheduled policy lists individual items with specific descriptions and values. A floater, by contrast, may cover a category of property (such as all jewelry) up to a blanket limit without listing each piece. Understanding the difference matters because it affects how claims are paid and what documentation you need.
When you schedule an item, the insurer agrees to insure that exact piece for an agreed value or appraised value. If the item is lost, stolen, or damaged, the claim is handled based on the scheduled value, often with no deductible. Floaters can be more flexible for collections that change frequently, but they may come with per-item caps or require you to list items above a certain threshold. Some insurers offer a hybrid: a blanket floater for low-value pieces plus scheduled coverage for star items.
Here is how the two approaches compare on key points:
- Documentation: Scheduled coverage requires a description and often an appraisal or receipt for each item; floaters may require only a general inventory.
- Deductible: Scheduled items typically have a zero deductible; floaters may apply the policy deductible.
- Covered perils: Both often cover "mysterious disappearance" and accidental loss, which the base policy excludes.
- Payout: Scheduled items pay the agreed value; floaters may pay actual cash value or a repair cost up to the blanket limit.
For most homeowners with a handful of high-value pieces, scheduled personal property coverage for jewelry and valuables offers the most predictable protection. It removes guesswork at claim time because the value is agreed upon upfront. If your collection is large and constantly changing, a floater or a combination approach may be more practical.
What Scheduled Coverage Actually Pays For
Scheduled coverage is broader than a standard homeowners policy in several important ways. First, it typically covers risks that the base policy excludes, such as accidental loss (dropping a ring down a drain), mysterious disappearance (an item is simply gone with no evidence of theft), and damage from incidents like a stone falling out of its setting. Second, it usually waives the deductible, so small claims do not eat into your payout. Third, because the value is agreed upon, you avoid disputes over depreciation or replacement cost.
Coverage limits and exclusions still apply. Most schedules exclude normal wear and tear, gradual deterioration, and damage from insects or vermin. Some policies exclude losses that occur while the item is in the care of a jeweler for repair, though others extend coverage to those situations. If you travel internationally, check whether your schedule provides worldwide coverage; many do, but some impose territorial limits or require you to notify the insurer before a long trip.
It is also worth confirming whether the schedule pays replacement cost or agreed value. Replacement cost coverage pays to replace the item with a comparable new one, while agreed value pays the amount listed on the schedule. For items that appreciate, such as certain watches or signed pieces, an agreed value schedule with regular updates may be preferable. For everyday jewelry, replacement cost is often the better fit.
Are Appraisals Required, and How Often Should You Update Them
Most insurers require some form of documentation to schedule an item. For jewelry above a certain value, typically $1,000 to $5,000 depending on the carrier, a recent appraisal from a qualified gemologist or jeweler is standard. For lower-value items, a receipt or a detailed description with a photograph may suffice. The appraisal should include the item's description, metal type, stone characteristics (carat, cut, color, clarity), and a stated value.
Appraisals are not good forever. Market prices for precious metals and gemstones fluctuate, and an appraisal that is five or ten years old may not reflect the current replacement cost. Most insurers recommend updating appraisals every two to three years, and some require it at renewal or after a major market shift. If you file a claim with an outdated appraisal, the insurer may pay based on the scheduled value, which could leave you underinsured if replacement costs have risen.
Keeping appraisals current also helps at renewal. Insurers may adjust premiums based on updated values, and you can decide whether to increase or decrease coverage. A practical routine is to schedule appraisals alongside other financial reviews, such as when you update your will or review your home insurance policy. Store digital copies of appraisals and photographs in the cloud so they are available if you need to file a claim while traveling.
Cost Versus Benefit: Scheduling Versus Raising Your General Limit
One common question is whether it is cheaper to simply raise the general personal property limit on a homeowners policy instead of scheduling items. Raising the limit does increase overall coverage, but it does not remove the internal sublimits for jewelry theft. You could have $500,000 in personal property coverage and still face a $1,500 cap on jewelry theft. Scheduling is the only way to insure specific high-value items for their full value.
Costs vary by insurer, item type, and location, but scheduled coverage for jewelry often costs between $1 and $2 per $100 of insured value annually. A $10,000 ring might cost $100 to $200 per year to schedule, sometimes less when bundled with a homeowners policy. By contrast, increasing your general personal property limit by $50,000 might add $200 to $400 to your annual premium without solving the sublimit problem. For most homeowners with a few valuable pieces, scheduling is the more efficient use of premium dollars.
The math changes if you own many low-value items that together exceed the sublimit. In that case, a blanket floater or a higher sublimit endorsement may be more cost-effective than scheduling dozens of individual pieces. A licensed agent can run the numbers for both approaches. InsuranceShopping.com connects consumers with agents who can compare scheduled coverage options and explain the trade-offs, and you can also use broader resources like InsuranceAdvisers to review policy structures before you commit.
Steps to Schedule Jewelry and Valuables
The process is straightforward but requires preparation. Before you call an insurer, gather documentation and decide which items are worth scheduling. Not every piece needs its own schedule; focus on items that exceed the sublimit or that you would struggle to replace out of pocket. The following steps outline a practical approach.
- Inventory your valuables. List each item with a description, purchase date, purchase price, and current estimated value. Photograph each piece from multiple angles and include any certificates or receipts.
- Get appraisals for high-value items. Use a qualified appraiser and request a written appraisal that includes the details insurers need. Ask the appraiser to note the replacement cost, not just the resale value.
- Compare scheduled coverage quotes. Ask your current insurer and at least one alternative for quotes on scheduled personal property coverage for jewelry and valuables. Compare premiums, deductibles, covered perils, and whether worldwide coverage is included.
- Review the policy language. Confirm how claims are paid (agreed value vs. replacement cost), whether there is a deductible, and what exclusions apply. Ask about any requirements for reappraisal or inventory updates.
- Update your schedule annually. Add new purchases, remove items you no longer own, and update values based on new appraisals. Keep copies of all documents with your insurance records.
After the policy is in force, store your inventory and appraisals in a safe place, ideally a fireproof safe or a cloud-based folder. If you move or travel frequently, confirm that your schedule follows your belongings. Some policies cover items worldwide, while others limit coverage to the United States and Canada.
Common Mistakes to Avoid
Even homeowners who buy scheduled coverage sometimes run into problems at claim time. One frequent mistake is underinsuring an item because the appraisal is outdated. Another is failing to list a new purchase; most policies give you a short window (often 30 days) to add newly acquired items, but you must report them and pay the additional premium. A third mistake is assuming that a schedule covers everything. Items in storage, items used for business, and items that are damaged through normal wear may fall outside the policy.
It also pays to read the fine print on "pairs and sets." If you schedule a pair of earrings and lose one, some policies pay only the value of the lost earring, while others pay for the pair or require you to replace both. Similarly, if a ring is damaged, the insurer may pay to repair it rather than replace it, and the repair might not restore the item to its original condition. Ask your agent how these scenarios are handled before you buy.
Finally, do not cancel your scheduled coverage just because you have not filed a claim. The value of the coverage is the peace of mind it provides, and claims are unpredictable. If premiums rise, shop around; competition among insurers is often strong for scheduled jewelry coverage, and a different carrier may offer better terms for the same items.
Frequently Asked Questions
Does scheduled coverage replace my homeowners policy?
No. Scheduled personal property coverage is an endorsement or a separate policy that works alongside your homeowners insurance. Your base policy continues to cover your home and other belongings, while the schedule adds broader, higher-limit protection for specific items.
Can I schedule items without an appraisal?
Some insurers allow scheduling without a formal appraisal for items below a certain value, often $1,000 to $2,000. Above that threshold, an appraisal or a detailed receipt is usually required. The requirements vary by carrier, so ask before you assume.
What happens if I sell or give away a scheduled item?
You should notify your insurer and remove the item from the schedule to avoid paying premiums for property you no longer own. If you replace it with a similar item, you can often substitute the new item on the schedule, subject to the insurer's approval and any change in value.
Is theft the only covered peril?
No. Scheduled coverage typically covers theft, accidental loss, mysterious disappearance, fire, water damage, and other risks. It is broader than the base policy, but exclusions still apply, so review the policy language carefully.
Scheduled personal property coverage for jewelry and valuables is not about being overly cautious; it is about matching your insurance to the things you actually own. Standard policies are designed for average households, and their sublimits reflect that. If your jewelry box or safe holds items worth more than a few thousand dollars, a schedule gives you full value, broader protection, and fewer surprises at claim time. Start with an inventory, get a current appraisal, and compare quotes from more than one insurer. The effort you put in now can save you a painful financial lesson later.