Diminished Value Claim After a Car Accident Explained
A diminished value claim after a car accident explained: recover the resale loss your repaired car still carries. Call (833)-214-6397 for guidance.
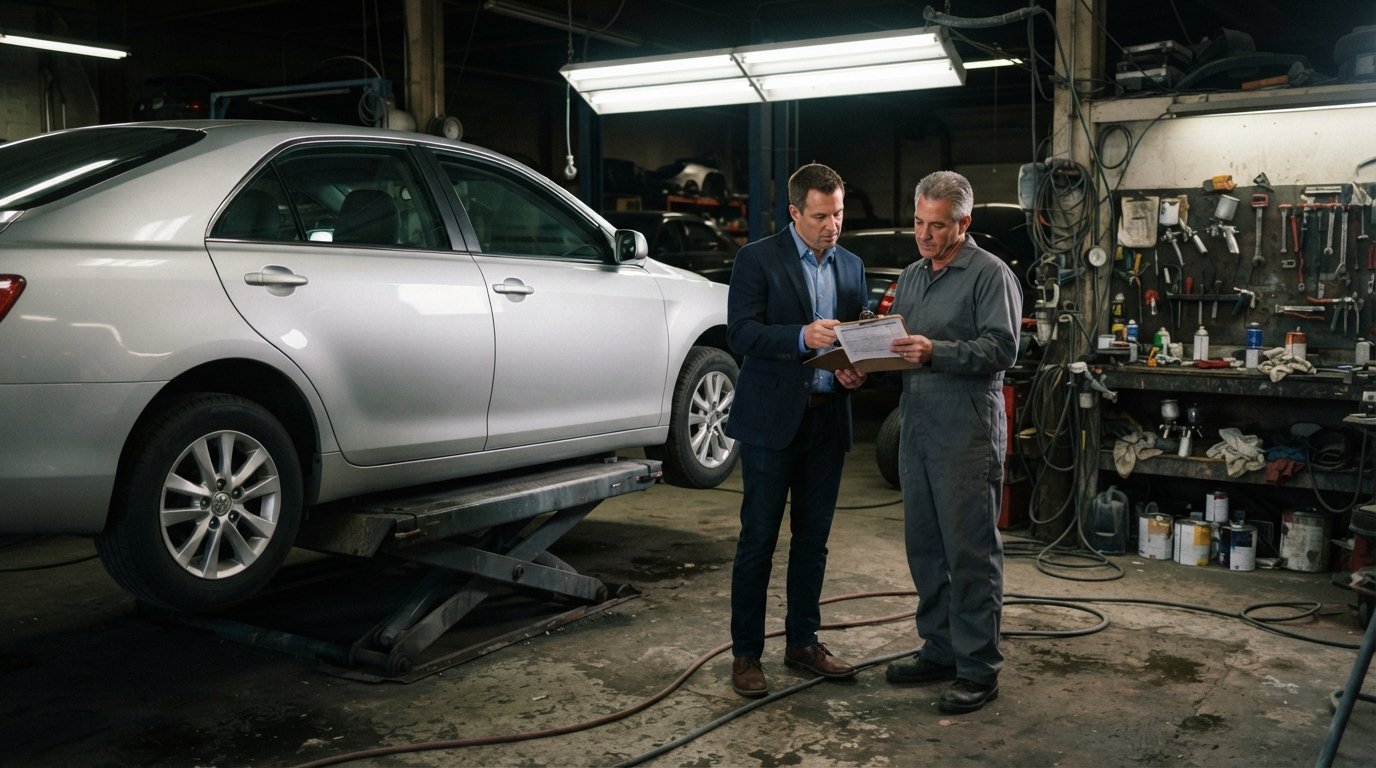
A car that has been repaired after a collision is never quite the same, at least not in the eyes of a future buyer. Even when the body shop does flawless work, a vehicle with a documented accident history typically sells for less than an identical model with a clean record. That gap between pre-accident market value and post-repair market value is called diminished value, and in many states you can file a diminished value claim after a car accident to recover it. This guide explains how the process works, who pays, what evidence you need, and how to push back when an insurer lowballs your claim.
What Diminished Value Means and Why It Matters
Diminished value is the loss in a vehicle's resale or trade-in value that remains after all collision damage has been repaired. It is not the cost of the repairs themselves; those are covered under the property damage portion of an auto claim. Instead, diminished value compensates you for the fact that your car now carries an accident history on its vehicle history report, which makes it less attractive to dealers, private buyers, and even some lenders. For a newer or higher-end vehicle, that stigma can translate into thousands of dollars of lost value.
There are three commonly recognized types of diminished value. Immediate diminished value is the difference in value before and after repairs, measured at the moment the car is fixed. Inherent diminished value is the ongoing loss caused by the accident history itself, even after a perfect repair. Repair-related diminished value covers additional loss caused by substandard or incomplete repairs. Most consumer claims focus on inherent diminished value, because it is the loss that persists no matter how good the body shop was.
Why does this matter for you? Because insurance settlements often cover only visible damage. If you accept a repair check without raising diminished value, you may be leaving money on the table. A successful diminished value claim can recover the difference between what your car was worth before the crash and what it is worth now, and that money can be used toward a future down payment, a replacement vehicle, or simply to offset the financial hit of owning a car with a blemished history.
Which States Allow Diminished Value Claims
Diminished value recovery is governed by state law, and the rules vary widely. Some states explicitly recognize diminished value as a recoverable damage in third-party claims, meaning you can pursue the at-fault driver's insurer for the loss. Other states allow it only in limited circumstances, and a few have rules that make first-party diminished value claims (against your own insurer) difficult or impossible under standard policy language. Because of this patchwork, the first practical step in any diminished value claim after a car accident is to confirm what your state permits.
Georgia is often cited as one of the most claimant-friendly states because its courts have recognized diminished value as a form of recoverable damage, and it has a specific framework for first-party claims under certain policy provisions. States like Florida, Texas, and Washington have also seen successful diminished value arguments, while some other states restrict recovery or require you to show specific proof of loss. If you are unsure where your state stands, a conversation with a licensed agent or a consumer rights resource can save you weeks of dead ends.
It also helps to understand that state rules can affect both the theory of recovery and the practical process. In some states, you must file against the at-fault party's liability insurer; in others, you may be able to pursue your own carrier under collision or uninsured motorist coverage, depending on policy language. Knowing the correct target from the start prevents your claim from being bounced between adjusters who each say the other one should handle it.
Filing Against the At-Fault Driver's Insurer vs. Your Own
The most common path for a diminished value claim is a third-party claim against the at-fault driver's liability insurer. In this scenario, you are not the policyholder; you are the claimant. The at-fault insurer owes a duty to its insured to pay reasonable damages, and in states that recognize diminished value, that can include your economic loss. The advantage is that you are not tapping your own coverage or risking your own premiums. The disadvantage is that the other insurer has no contractual obligation to you, which can make negotiations slower and more adversarial.
Filing against your own insurer is sometimes possible, but it depends heavily on your policy language and state law. Some policies exclude diminished value explicitly, while others may cover it under collision or uninsured motorist provisions. If you file first-party, you may have a contractual right to appraisal or arbitration if you and the insurer disagree on the amount. That procedural lever can be valuable, but it only exists if your policy and state rules support it.
In practice, many claimants start with the at-fault insurer because that is where liability clearly lies. If that insurer denies the claim or disputes the amount, you can evaluate whether your own policy offers a better route. Before you decide, review your declarations page and any endorsements, and consider whether your state treats diminished value as a mandatory part of third-party liability. A well-organized claim file, including photos, repair records, and a professional appraisal, will make either path easier to pursue.
How to Get an Independent Diminished Value Appraisal
An independent appraisal is often the backbone of a credible diminished value claim. Insurance adjusters frequently rely on formula-based estimates that undervalue the loss, so a detailed, vehicle-specific appraisal gives you a counterweight. Look for an appraiser who specializes in diminished value and who uses recognized methodologies, such as comparable sales analysis or a structured calculation that accounts for your vehicle's make, model, mileage, and accident severity. Ask for a written report that explains the methodology and provides a dollar figure you can present to the insurer.
Before you hire anyone, gather the basics: your repair estimate and final invoice, photos of the damage before and after repairs, your vehicle's clean pre-accident history, and current market listings for similar vehicles. A good appraiser will use these materials to establish a pre-loss value and a post-repair value. Expect the process to take anywhere from a few days to a couple of weeks, and expect to pay a fee, often a few hundred dollars. That fee is sometimes recoverable as part of your damages, but not always, so clarify the appraiser's terms upfront.
Be wary of appraisers who promise a specific dollar amount before reviewing your documents or who use a one-size-fits-all formula without inspecting the vehicle. A credible report will be transparent about assumptions and will withstand scrutiny from an adjuster. If you are working with a licensed agent or a consumer resource, ask whether they can refer you to a reputable appraiser in your state. The quality of the appraisal often determines whether your claim is taken seriously or dismissed as a negotiating tactic.
Evidence That Strengthens a Diminished Value Claim
Insurers evaluate diminished value claims on documentation, not emotion. The stronger your evidence, the harder it is for an adjuster to brush you off. Start with a complete repair file: the original estimate, supplemental estimates, the final invoice, and photos of the damage at every stage. Then add proof of your vehicle's pre-accident condition, such as maintenance records, a pre-accident inspection, and listings for comparable vehicles with clean histories. If your car is a specialty or high-value model, include any documentation that supports its market niche.
A professional appraisal is the centerpiece, but supporting evidence matters too. Collect current market data showing what similar vehicles sell for with and without accident history. If you have received a dealer trade-in quote that reflects the accident, include it. If your vehicle history report now shows the accident, include that as well, because it demonstrates the stigma that buyers will see. Keep everything organized in a single file with a cover sheet summarizing your claim amount and the basis for it.
Here is a quick checklist of materials that commonly strengthen a diminished value claim:
- Repair estimates, supplements, and final invoices
- Before-and-after photos of the damage and repairs
- Vehicle maintenance records and pre-accident condition documentation
- Independent diminished value appraisal report
- Comparable market listings and dealer trade-in quotes
Once you have this package, present it to the adjuster with a short cover letter that states the amount you are claiming and why. Keep the tone factual and professional. If the insurer responds with a low offer, you can use the same evidence to support an appeal or a negotiation. For a broader view of how to protect your claim from the first day after a crash, see this car accident insurance checklist, which walks through the steps that keep your documentation strong.
Why Insurers Dispute Diminished Value and How Appeals Work
Insurers dispute diminished value claims for several reasons. Some adjusters rely on internal formulas that produce low numbers, while others argue that a proper repair restores full value or that your state does not recognize the claim. In third-party claims, the at-fault insurer may also argue that it owes nothing beyond the repair cost because its contract is with its own policyholder, not with you. These arguments are not always correct, but they can be effective if you are unprepared.
If your claim is denied or undervalued, the appeal process usually starts with a written response that addresses the insurer's specific objections. Point to your appraisal, your documentation, and any state law or policy language that supports recovery. Ask for the adjuster's methodology in writing, and request a supervisor review if the response is generic. In first-party claims, your policy may give you a right to appraisal or arbitration, which can be a powerful tool when negotiations stall. In third-party claims, you may need to escalate to the insurer's claims manager or, in some cases, pursue the matter in small claims court.
Patience and persistence matter. Many diminished value claims are resolved through a series of offers and counteroffers rather than a single decision. Keep a written log of every call, email, and letter, and do not accept a final payment until you understand whether it resolves the diminished value portion of your claim. If you are navigating multiple insurance issues at once, a resource like InsuranceAdvisers can help you compare coverage options and understand how different policies interact, while InsuranceShopping.com can connect you with licensed agents who work with auto claims every day.
Practical Steps to File a Diminished Value Claim
Filing a diminished value claim after a car accident is a process, not a single letter. The order in which you do things can affect whether the insurer takes you seriously. Start by confirming your state's rules and identifying the correct insurer to pursue. Then document everything, get your appraisal, and submit a clear, organized demand. If the insurer pushes back, appeal with evidence rather than argument.
Here is a straightforward sequence you can follow:
- Confirm that your state recognizes diminished value claims and identify the responsible insurer.
- Complete all repairs and gather your repair estimates, invoices, and photos.
- Obtain an independent diminished value appraisal from a qualified expert.
- Submit a written demand package to the adjuster with your evidence and claimed amount.
- Negotiate or appeal in writing if the offer is low, and escalate if necessary.
Each step builds on the last, so avoid skipping ahead. For example, submitting a demand before repairs are complete can weaken your claim because the insurer can argue the final value is unknown. Likewise, appealing without a written record of the original denial leaves you with less leverage. If you are unsure about your state's rules or your policy language, a licensed agent can help you interpret the details and avoid common mistakes.
Common Mistakes That Weaken Diminished Value Claims
One of the most common mistakes is accepting a repair settlement without reserving the right to pursue diminished value later. Once you sign a release, you may give up your ability to claim additional losses. Read every document carefully and ask whether the release covers only the repair cost or all property damage, including diminished value. If the language is unclear, ask for clarification in writing before you sign.
Another mistake is relying on a generic online calculator instead of a vehicle-specific appraisal. Insurers see formula-based claims every day and often discount them. A detailed report that accounts for your car's specific history, mileage, and market position is far more persuasive. Similarly, failing to document the pre-accident condition of your vehicle can undermine your claim, because the insurer may argue that some of the loss existed before the crash.
Finally, do not let the process drag on without follow-up. Many states have statutes of limitations for property damage claims, and evidence can become harder to gather over time. Set reminders to check in with the adjuster, and keep copies of everything you send and receive. If you feel overwhelmed, remember that you do not have to navigate the process alone. InsuranceShopping.com is an informational and connection service that can help you find licensed agents who understand auto claims, and it does not underwrite or issue policies itself. With the right documentation and a clear strategy, a diminished value claim after a car accident can be a recoverable loss rather than an unavoidable one.