Smart Home Devices and Home Insurance Discounts
Smart home devices and home insurance discounts can lower your premium while preventing costly water, fire, and theft claims. Call (833)-214-6397 for guidance.
By Ophelia Crane
Homeowners spend thousands of dollars on smart home technology each year, often with the hope that these devices will make their properties safer and their lives easier. What many do not realize is that the same technology can also reduce their home insurance premiums. Insurers are increasingly recognizing that connected devices, from water leak sensors to smart smoke detectors, can prevent costly claims before they happen. Understanding how smart home devices and home insurance discounts work together can put real money back in your pocket while protecting your most valuable asset.
How Insurers View Smart Home Technology
Insurance companies operate on risk. When a homeowner installs devices that reduce the likelihood of a covered loss, the insurer's exposure drops, and many carriers are willing to share that savings through premium credits. The key is understanding which devices insurers actually recognize and how they categorize them. Not every gadget on the market carries weight with underwriters. A smart speaker that plays music and answers trivia questions will not impress an adjuster, but a monitored water shutoff valve absolutely will.
Most major carriers now have formal programs or internal guidelines for protective device credits. These credits typically fall into three broad categories: water damage prevention, fire and smoke detection, and security and theft deterrence. Water damage alone accounts for a significant portion of homeowner claims each year, which is why leak detection systems have become one of the most valuable smart investments from an insurance perspective. Similarly, monitored smoke and carbon monoxide detectors can qualify for credits because they alert emergency services faster than traditional alarms.
The specific discount amount varies widely by carrier, state, and the overall risk profile of the home. Some insurers offer flat annual credits, while others apply a percentage reduction to the premium. In many cases, the discount is modest, perhaps between two and ten percent, but it compounds over time. More importantly, the devices themselves can prevent a claim that would otherwise cost tens of thousands of dollars and potentially lead to a non-renewal or a surcharge. When you compare home insurance quotes, it helps to ask each carrier directly about their protective device credits rather than assuming they are all the same.
Which Device Categories Insurers Commonly Recognize
Not all smart devices are treated equally. Insurers tend to favor technology that directly addresses the perils covered in a standard homeowners policy. The three categories that consistently earn recognition are water leak detection, smoke and fire monitoring, and security systems. Within each category, there are specific features that matter more than others.
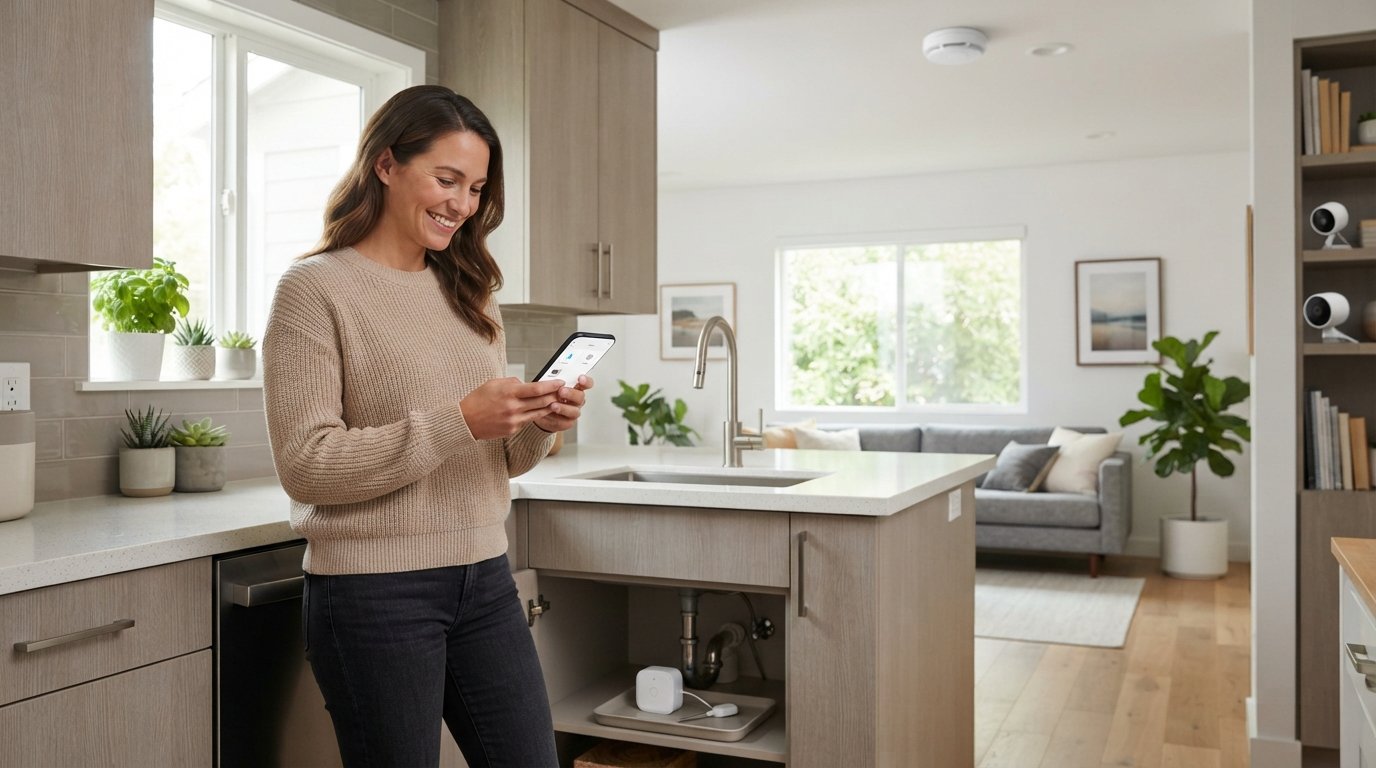
- Water leak and shutoff systems: Devices that detect moisture and automatically shut off the water supply, such as those from Moen, Flo by Moen, and Phyn, are highly valued. They prevent burst pipe damage and slow leaks that can rot wood and promote mold.
- Monitored smoke and carbon monoxide detectors: Smart detectors that send alerts to a monitoring center or your phone, like Nest Protect or Kidde Smart, often qualify for credits because they reduce fire damage severity.
- Security and burglary deterrents: Professionally monitored alarm systems, smart door locks, video doorbells, and security cameras can earn discounts by reducing theft risk and providing evidence in claims.
Beyond these core categories, some insurers also recognize smart garage door controllers, temperature sensors that prevent frozen pipes, and even smart lighting that creates the appearance of occupancy. The common thread is that the device must actively reduce the chance of a covered loss or minimize the damage when a loss occurs. A device that simply adds convenience, like a smart coffee maker, will not move the needle on your premium.
It is also worth noting that insurers may distinguish between professionally monitored systems and self-monitored ones. A self-monitored water sensor that sends a phone alert is helpful, but a system that automatically shuts off the water main without human intervention is far more valuable to an insurer. When documenting your devices for a discount, be specific about the capabilities, not just the brand name.
How to Ask About Protective Device Credits on a Policy
Many homeowners never ask about discounts simply because they do not know they exist. Insurance agents and customer service representatives are not always proactive about mentioning every possible credit, especially if the policy was purchased online or through a third party. The responsibility often falls on you to start the conversation. The good news is that asking is straightforward, and the potential savings make it worth the effort.
Start by reviewing your current policy declarations page and any endorsements. Look for line items labeled "protective device credit," "smart home discount," or similar language. If you do not see one, call your insurer or agent and ask directly. A useful script is: "I have installed a monitored water leak detection system with automatic shutoff and smart smoke detectors. Do you offer a protective device credit for these, and what documentation do you need?" This approach signals that you are informed and serious about maximizing your discounts.
If your current carrier does not offer a credit for your devices, that is valuable information. It may be worth shopping around. Some insurers specialize in homes with smart technology and actively compete for that business. When you request a quote, mention your devices upfront so the agent can apply any available credits from the start. You can also use online comparison tools to see how different carriers stack up. For a broader look at how shopping around can pay off, our guide on auto insurance discounts San Diego illustrates the same principle: the same risk profile can produce very different quotes depending on the carrier.
Keep in mind that discounts are not guaranteed and vary by state regulations. Some states require insurers to file their discount programs with the department of insurance, while others give carriers more flexibility. Even if a discount is not available, the devices may still qualify you for a better rate tier or make your home more attractive to insurers who are cautious about water damage claims.
Documenting Installation for a Potential Discount
Insurers will not take your word for it. To apply a smart home discount, they typically require proof of installation and sometimes proof of ongoing monitoring. The documentation process is simple but must be done correctly to avoid delays or denials. Gathering the right paperwork before you call can streamline the entire process.
What you need depends on the device and the insurer, but common requirements include:
- Receipts or invoices showing the purchase and professional installation of the devices.
- Photos of the installed devices, including serial numbers or model numbers where visible.
- Monitoring contract or activation confirmation for professionally monitored systems.
- App screenshots showing the device is connected and functioning within the smart home ecosystem.
Once you have these items, submit them through your insurer's preferred channel, whether that is an online portal, email, or your agent. Follow up after a week or two to confirm the discount has been applied. If it has not, ask for a written explanation. Sometimes the issue is a simple coding error, but other times it may be that your specific device model is not on the approved list. In that case, you can ask whether a different model would qualify or whether the insurer plans to update its list.
It also helps to keep a dedicated folder, digital or physical, for your smart home documentation. When you renew your policy or shop for new coverage, you will have everything ready to go. This is especially useful if you switch carriers, because the new insurer will want to verify your devices from scratch. A well-organized record saves time and ensures you never miss out on a credit you deserve.
How Early Detection Reduces Claim Severity and Loss of Use Costs
The financial argument for smart home devices goes far beyond the premium discount. The real savings come from preventing or minimizing a loss in the first place. Consider a slow water leak behind a washing machine. Without a sensor, that leak might go unnoticed for weeks, soaking drywall, warping floors, and creating the conditions for mold. By the time you discover it, the repair bill could easily reach five figures, and you may need to move out during remediation. That triggers loss of use coverage, which pays for temporary housing, meals, and other living expenses, all of which drive up the total claim cost.
A smart water leak sensor detects the moisture within minutes and can automatically shut off the water supply. You get an alert on your phone, and you can address the problem before it becomes a catastrophe. The difference in claim severity is dramatic. Insurers know this, which is why they are willing to offer discounts. They would rather give you a small credit than pay a massive claim.
The same logic applies to fire and security. A monitored smoke detector can alert the fire department while you are away, potentially saving the structure. A security system with cameras can deter burglars or help recover stolen property. In each case, the device reduces the duration and extent of the loss, which directly reduces the insurer's payout. Lower payouts mean lower premiums across the board, and individual homeowners who take proactive steps often see the benefit in their own rates.
It is also worth considering the indirect costs. A major claim can lead to higher premiums at renewal, difficulty switching insurers, and even a non-renewal notice. By preventing severe losses, smart devices protect your insurability as well as your home. That long-term stability is often worth more than the immediate discount.
Choosing the Right Devices for Insurance Savings
If your goal is to maximize both protection and potential discounts, focus on devices that address the most common and costly perils. Water damage, fire, and theft are the big three. Start with a monitored water shutoff system, add smart smoke and carbon monoxide detectors, and consider a professionally monitored security system. These three categories cover the majority of insurer-recognized credits and deliver the greatest risk reduction.
When evaluating specific products, look for features like automatic shutoff, cellular backup, and professional monitoring. These features make the device more reliable and more attractive to insurers. Also check whether the device integrates with a central hub or app, because some insurers prefer systems that can be verified remotely. If you are building a smart home from scratch, plan your device ecosystem with insurance in mind. A little forethought can pay off for years.
Finally, remember that discounts are just one piece of the puzzle. The best approach is to combine smart technology with a well-structured policy from a reputable carrier. Take time to compare home insurance options, ask about all available credits, and review your coverage annually. For additional tools and resources to compare policies and connect with licensed agents, you can visit QuoteComparison to explore side-by-side quotes. With the right devices and the right policy, you can protect your home and your wallet at the same time.