Welcome to Medicare Visit and Enrollment Period Explained
Understand what the welcome to Medicare visit and enrollment period involve, including deadlines and penalties. Call (833)-214-6397 for expert help.
By Kaia Bellmont
Turning 65 is a milestone, but it also comes with a stack of paperwork, deadlines, and decisions that can feel overwhelming. Among the most common questions new beneficiaries ask is: what is the Welcome to Medicare visit and enrollment period, and why does it matter? Understanding both the preventive visit and the enrollment window is the key to avoiding late penalties, maximizing your benefits, and starting your Medicare journey on the right foot. This guide breaks down the essentials so you can move forward with confidence.
The Welcome to Medicare Preventive Visit: What It Is and What It Covers
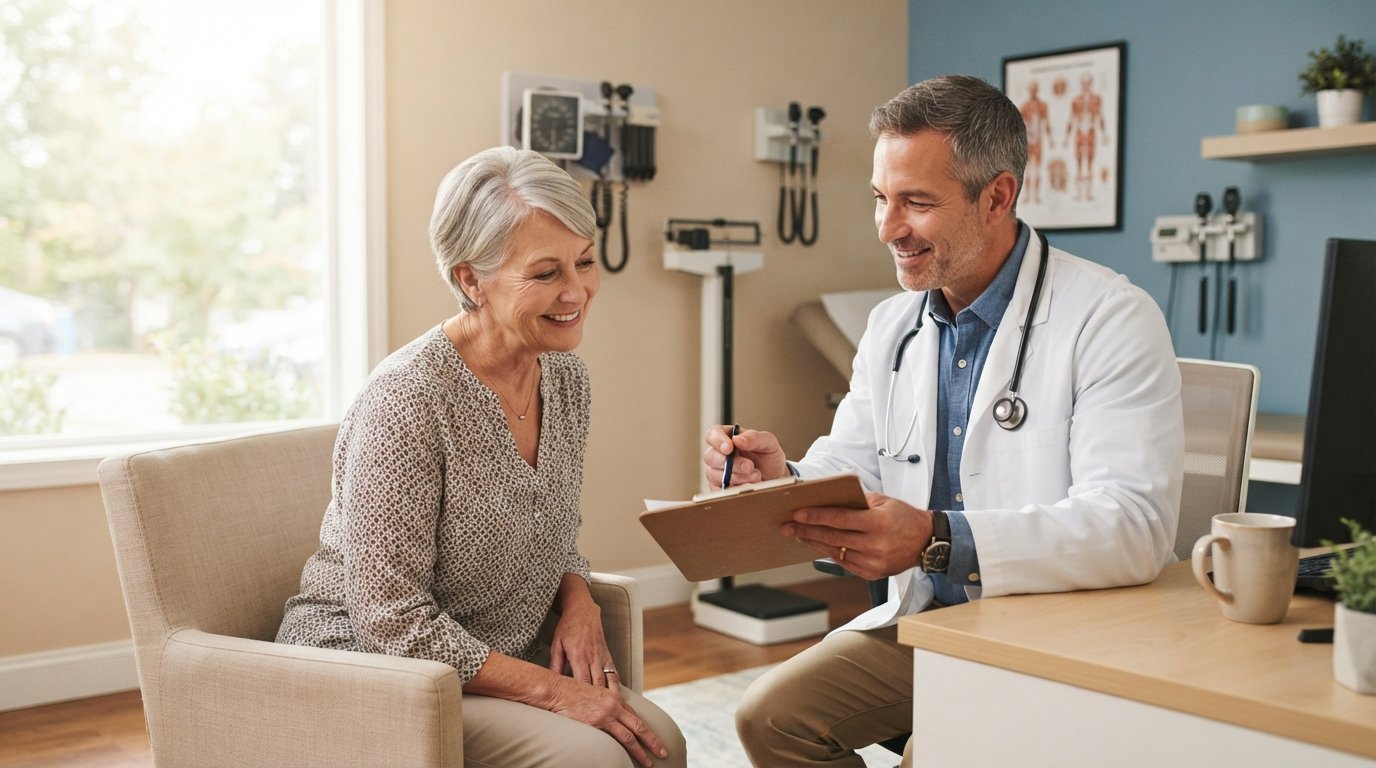
The Welcome to Medicare preventive visit is a one-time, no-cost appointment available to anyone with Medicare Part B. It is not a full physical exam, and it is not a substitute for ongoing care. Instead, it is a focused review designed to catch potential health risks early and set you up with a personalized prevention plan. You must schedule this visit within the first 12 months of enrolling in Part B. The visit itself is free, but any follow-up tests, treatments, or referrals you receive afterward may be subject to standard Part B cost-sharing (deductibles and coinsurance).
During the visit, your doctor or qualified health professional will review your medical and family history, check your height, weight, and blood pressure, and calculate your body mass index. They will also screen for cognitive impairment and depression, and discuss your options for preventive services like cancer screenings and vaccines. You will leave with a written plan that outlines which screenings and lifestyle changes are right for you, along with referrals to specialists or community resources if needed. The goal is to create a roadmap for staying healthy, not to diagnose or treat existing conditions.
It is important to note that the Welcome to Medicare visit is different from the annual wellness visit. The Welcome visit happens only once, within your first year on Part B. The annual wellness visit is a recurring appointment you can have every 12 months afterward. Both are free, but they serve different purposes: the Welcome visit is an introductory assessment, while the annual wellness visit is an ongoing check-in to update your prevention plan. If you miss the 12-month window for the Welcome visit, you cannot get it later, but you can still schedule an annual wellness visit.
To get the most out of your Welcome to Medicare visit, prepare a list of your current medications, any chronic conditions, and your family health history. Write down questions you want to ask, such as which screenings you need or how to manage a specific risk factor. Bring your list to the appointment and take notes. This proactive approach ensures you and your doctor cover everything important and that you leave with a clear understanding of your next steps. Remember, this visit is a tool to empower you, not a hurdle to clear.
The Initial Enrollment Period: Your First Window to Sign Up
Your Initial Enrollment Period (IEP) is a seven-month window that starts three months before the month you turn 65 and ends three months after your birthday month. For example, if you turn 65 in July, your IEP runs from April 1 through October 31. During this time, you can enroll in Medicare Part A (hospital insurance) and Part B (medical insurance). If you are already receiving Social Security benefits, you will be automatically enrolled in Parts A and B, and your card will arrive in the mail. If not, you must actively sign up through the Social Security Administration.
The timing of your enrollment matters because it affects when your coverage begins. If you enroll during the three months before your birthday month, your coverage starts on the first day of your birthday month. If you enroll during your birthday month, coverage starts the first day of the following month. If you enroll in the three months after your birthday month, your coverage start date is delayed, and you may face gaps in coverage. That is why experts recommend signing up early in your IEP, especially if you have no other creditable coverage.
For many newly eligible beneficiaries, this is also the time to consider Medicare Advantage (Part C) or a Medigap supplement. If you want to enroll in a Medicare Advantage plan, you can do so during your IEP or during the annual Medicare Open Enrollment period (October 15 to December 7). However, if you are newly eligible, your IEP gives you a guaranteed opportunity to enroll in a Medicare Advantage plan without going through medical underwriting. Similarly, if you want a Medigap policy, your best chance to buy one without answering health questions is during your Medigap Open Enrollment Period, which starts the month you are 65 and enrolled in Part B and lasts for six months.
To help you navigate these overlapping windows, our guide on Medicare enrollment periods in 2026 breaks down each period and what you can do during it. Understanding the differences between the IEP, the General Enrollment Period, and special enrollment periods can save you from costly mistakes. For now, focus on your IEP: it is your primary window to get covered without penalties.
Deadline Rules and Late Enrollment Penalties
Missing your IEP can trigger late enrollment penalties that last for as long as you have Medicare. For Part B, the penalty is 10 percent of the standard premium for each 12-month period you could have enrolled but did not. This penalty is added to your monthly premium for as long as you have Part B. For Part A, most people qualify for premium-free Part A based on their work history, but if you do not, the penalty is also 10 percent for twice the number of years you delayed enrollment. There is also a Part D late enrollment penalty if you go 63 days or more without creditable prescription drug coverage after your IEP ends.
There are exceptions to these penalties if you have creditable coverage through an employer or union. If you or your spouse is still working and you have health insurance through that job, you may be able to delay Part B without penalty. However, you must confirm that your employer coverage is considered creditable by Medicare. You will need to enroll in Part B during a Special Enrollment Period (SEP) that begins when your employment or coverage ends. The SEP lasts for eight months after you lose employer coverage, but it is safer to enroll before the coverage ends to avoid gaps.
If you are still working and have employer coverage, you should also check whether your employer requires you to enroll in Medicare at 65. Some employers require it, while others do not. If your employer coverage is primary and you delay Medicare, you should still enroll in Part A (if it is premium-free) because it can help cover hospital costs. Part B can be delayed if your employer coverage is creditable. Always speak with your benefits administrator to understand your specific situation.
If you miss your IEP and do not have creditable coverage, you can enroll during the General Enrollment Period (January 1 to March 31 each year). However, your coverage will not start until July 1, and you will likely face late penalties. The best strategy is to enroll on time. Set a reminder three months before your 65th birthday and gather your documents, including your birth certificate, Social Security card, and proof of any current health coverage.
When to Sign Up If You Still Have Employer Coverage
Many people continue working past age 65 and have health insurance through their employer or their spouse's employer. In this situation, you may be able to delay enrolling in Medicare Part B without penalty, provided your employer coverage is based on current employment and is considered creditable. The key is to coordinate your Medicare enrollment with your employer coverage so you do not end up with gaps or unnecessary premiums. Here is a simple framework to follow:
- If your employer has 20 or more employees: Your employer coverage is likely primary, and you can delay Part B without penalty. You should still enroll in Part A (if premium-free) because it can help with hospital costs. When you retire or lose coverage, you will have an eight-month Special Enrollment Period to sign up for Part B.
- If your employer has fewer than 20 employees: Medicare is primary, and you should enroll in Parts A and B during your IEP to avoid penalties. Your employer coverage may become secondary. Speak with your employer to confirm how coverage coordinates.
- If you have COBRA or retiree coverage: These are not considered creditable employer coverage for delaying Medicare. You should enroll in Medicare during your IEP to avoid penalties.
It is also important to consider the cost of delaying Part B. If you have a Health Savings Account (HSA) and are contributing to it, you cannot contribute once you enroll in Medicare. You should stop HSA contributions six months before you enroll in Medicare to avoid tax penalties. If you plan to delay Part B, you can continue contributing to your HSA, but you must ensure you are not receiving Social Security benefits, as that would automatically enroll you in Part A and disqualify you from HSA contributions.
Always communicate with your employer's HR department and, if needed, a licensed insurance agent to confirm your options. The rules can be complex, and a wrong move could cost you in penalties or lost coverage. A quick conversation can save you thousands of dollars over time.
Checking Plan Availability by ZIP Code Before Choosing
Medicare Advantage and Part D plans vary significantly by location. A plan that is available in one county may not be available in the next. That is why it is essential to check plan availability by ZIP code before you make a decision. The Medicare Plan Finder on Medicare.gov allows you to enter your ZIP code and see all the plans available in your area, along with their premiums, deductibles, and coverage details. You can also filter by plan type, drug coverage, and star ratings.
When comparing plans, consider more than just the premium. Look at the total out-of-pocket costs, including copays for doctor visits, hospital stays, and prescriptions. Check whether your doctors and preferred pharmacies are in the plan's network. If you have ongoing health needs, make sure the plan covers the specialists and treatments you require. Also, review the plan's star rating, which reflects its quality and customer satisfaction. A low premium plan may end up costing more if it does not cover your medications or doctors.
For a broader comparison of insurance options beyond Medicare, you can use resources like QuoteComparison to explore quotes for auto, home, health, life, and Medicare coverage. This can be especially helpful if you are transitioning into retirement and need to review all your insurance policies. However, for Medicare-specific plan comparisons, stick with Medicare.gov or work with a licensed agent who can walk you through the options in your ZIP code.
If you are considering a Medigap policy, you should also check availability by ZIP code. Medigap plans are standardized by letter, but not all plans are offered in every state, and premiums vary. You can compare Medigap plans using online tools or by contacting your State Department of Insurance. Remember that Medigap Open Enrollment is a one-time window, so it is worth researching your options before you turn 65.
First Steps to Compare Options with a Licensed Agent
Working with a licensed insurance agent can simplify the process of choosing a Medicare plan. Agents can help you understand the differences between Original Medicare, Medicare Advantage, and Medigap, and they can check plan availability in your area. They can also help you avoid late enrollment penalties by ensuring you enroll during the right window. To get started, follow these steps:
- Gather your information: Collect your Medicare card (if you have one), a list of your doctors and prescriptions, and your ZIP code. This will help the agent find plans that fit your needs.
- Set up a phone or in-person appointment: Many agents offer free consultations. Be clear about your priorities, such as low premiums, drug coverage, or access to specific specialists.
- Ask about plan availability: Have the agent confirm which plans are available in your ZIP code and explain the differences in coverage and costs.
- Review the Summary of Benefits: For each plan you are considering, ask for the Summary of Benefits and Coverage. This document outlines what is covered and what you will pay.
- Enroll during the right period: If you are newly eligible, your IEP is the best time to enroll. If you are still working, coordinate with your employer. The agent can guide you through the enrollment process.
Before you speak with an agent, write down your questions. Ask about the plan's network, prior authorization requirements, and how the plan handles referrals. If you travel frequently, ask about urgent care and emergency coverage outside your home area. A good agent will listen to your needs and present options from multiple carriers, not just one. They should also disclose how they are compensated, which is often a commission from the insurance company, at no cost to you.
If you prefer to research on your own, you can use the comparison tools on InsuranceShopping.com to request quotes from licensed agents in your area. The site connects you with agents who can provide personalized guidance. Remember that InsuranceShopping.com is not an insurer and does not endorse or guarantee any specific plan; it is an informational resource that connects you with licensed professionals. Always verify the credentials of any agent you work with and confirm that they are licensed in your state.
Enrolling in Medicare does not have to be a headache. By understanding the Welcome to Medicare visit, knowing your enrollment periods, and using the right tools, you can make informed decisions that protect your health and your wallet. Take the time to review your options, ask questions, and get help when needed. Your future self will thank you.